
Quick Summary
Introduction
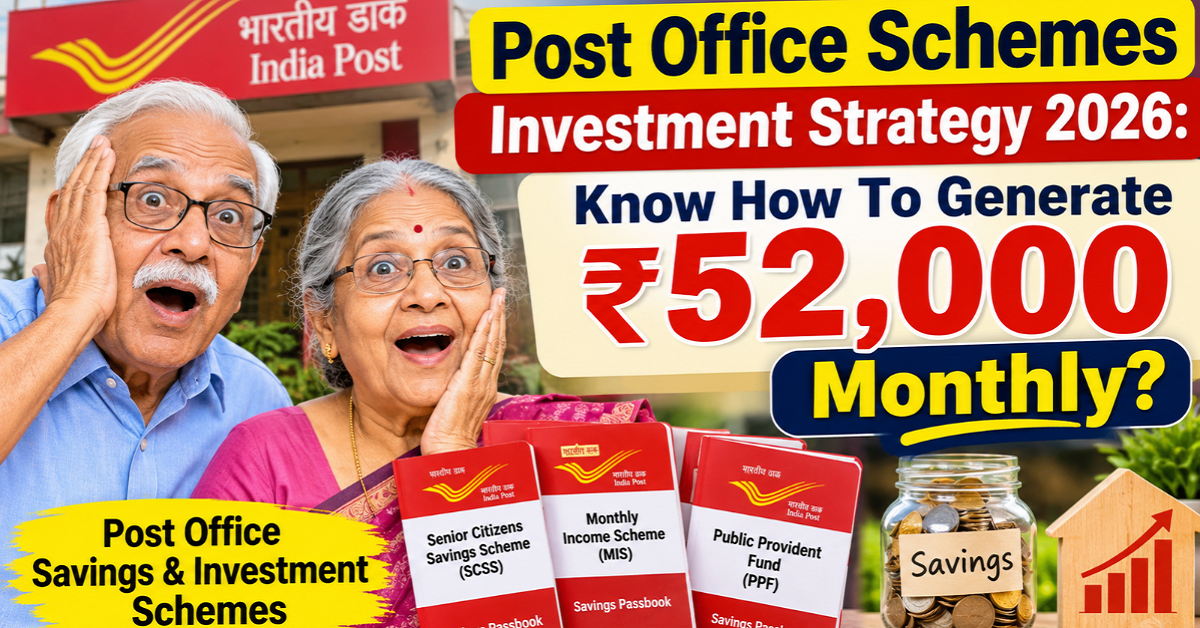
Senior citizens and retirees always looks for investment options that can provide regular income without exposing their savings to significant market fluctuations. Two popular choices from the Post Office are the Senior Citizens Savings Scheme (SCSS) and the Post Office Monthly Income Scheme (MIS).
Both the schemes SCSS and MIS are government-backed savings options where SCSS is designed mainly for senior citizens, offering quarterly interest payments, while MIS provides monthly interest income to eligible investors.
Table Of Content
Key Takeaways
- Post Office SCSS and MIS can help senior citizens and retirees earn regular income from their savings.
- SCSS is mainly for individuals aged 60 years and above, while MIS is available to eligible adults of any age.
- Both schemes have a tenure of five years.
- SCSS offers 8.2% annual interest, payable quarterly, where MIS offers 7.4% annual interest, payable monthly.
- SCSS allows investment up to ₹30 lakh per individual, while MIS allows ₹9 lakh for a single account and ₹15 lakh for a joint account.
- SCSS deposits qualify for Section 80C deduction under the old tax regime. MIS does not offer this benefit.
- TDS may apply to SCSS interest, while MIS interest is not subject to TDS.
- Both schemes have specific withdrawal restrictions and penalties for closing accounts before maturity.
Who Can Invest in SCSS and MIS?
| Eligibility | SCSS | MIS |
| Age limit | An individual whose age is 60 years or above. | Available to eligible adults of any age. |
| Early Retirees | Retired civilian employees aged 55–59 and defence retirees aged 50–59 may qualify under specific conditions. | No special retirement condition. |
| Minor accounts | Not available to minors | Minors whose age is 10 or above can open an account, but for younger minors - a guardian can manage accounts |
| Joint Account | Yes with Spouse | Joint up to 3 adult person |
Note
- Both the schemes are eligible only for resident individual.
- Special conditions for SCSS: Eligible early retirees generally need to invest within three months of receiving retirement benefits.
Interest Rates
| Feature | SCSS | MIS |
| Interest Rate | 8.2% p.a | 7.4% p.a |
| Credit Date | April 1, July 1, October 1, January 1 | Exact After 30 days |
| Payout | Quarterly | Monthly |
Deposit Limits, Tenure and Tax Benefits
| Particulars | SCSS | MIS |
| Minimum Deposit | ₹1,000 | ₹1,000 |
| Maximum deposit | ₹30 lakh | ₹9 lakh for single, ₹15 lakh for Joint up to 3 person |
| Tenure | 5 years | 5 years |
| Extension | Allowed in 3-year blocks. | It cannot be extended beyond 5 years. |
| Section 80C | Tax Benefit Available under old tax regime | Not available |
| TDS | Yes @10% under 194A or 393(1)[Sl.5(ii) | No TDS |
| How To Avoid TDS? | You can submit Form 121 | Not available |
Know More in Details - Form 121 Income Tax: New Single TDS Declaration for All Eligible Taxpayers
Premature Closure Rules
| SCSS | MIS |
| Zero interest if closed before 1 year | Cannot close before 1 year |
| 1.5% of the principal amount will be deducted as a penalty if closed between 1-2 years | 2% deducted from principal amount if closed between 1-3 years |
| Closed after 2 years, 1% of the deposit will be deducted. | After 3 years, 1% of the deposit will be deducted. |
Explore in Details
How to Earn Around ₹26,050 Monthly By investing in This Two Scheme?
If you are a senior citizen having ₹39 lakh in your account, you can combine SCSS and MIS to generate different streams of interest income.
| Particulars | SCSS (₹) | MIS (₹) |
| Investment Amount | 30,00,000 | 9,00,000 |
| Yearly Interest Rate | 8.20% | 7.40% |
| Interest Amount in 5 Years | 12,30,000 | 3,33,000 |
| Annual Interest | 246000 | 66,600 |
| Monthly Interest Amount | 20500 | 5550 |
Here,
- Total investment: ₹39 lakh
- Total annual interest: ₹3,12,600
- Average monthly equivalent: ₹26,050
Also Check Out - Senior Citizen Age Above 60 Years: Must Check These 3 Important Things in November 2026
How To Generate Around ₹52,100 Monthly?
Suppose a retired couple has around ₹80 lakh in bank account, which is their entire life saving. If they invest ₹30 lakh in separate SCSS accounts and invest ₹9 lakh each in MIS account, the total investment would be ₹78 lakh.
| Particulars | SCSS (₹) | MIS (₹) |
| First person | 30,00,000 | 9,00,000 |
| Second person | 30,00,000 | 9,00,000 |
| Total Investment Amount | 60,00,000 | 18,00,000 |
| Yearly Interest Rate | 8.20% | 7.40% |
| Interest Amount in 5 Years | 24,60,000 | 6,66,000 |
| Annual Interest | 4,92,000 | 1,33,200 |
| Monthly Interest Amount | 41,000 | 11,100 |
Combining the interest (₹41000 + ₹11100), the household would earn ₹52,100 monthly.
Note - Before investing you must keep in mind that MIS provides monthly payments, while SCSS provides quarterly payments. So, you should plan your household budget around the actual payment dates rather than expecting ₹52,100 every month.
Also Read - Income Tax For Senior Citizens For FY 2026-27
Conclusion
If you are a retired individual and seeking regular income after retirement, Senior Citizens Savings Scheme (SCSS) and Post Office Monthly Income Scheme (MIS) can be a useful combination. Before investing, you must check the latest interest rates, eligibility conditions, withdrawal rules and tax implications. The real secret is not just earning regular income, but choosing the right combination of schemes to make your savings work smarter for you.











 CAclubindia
