Introduction
GSTR-9 is the annual return that eligible registered taxpayers must file under Section 44 of the Central Goods and Services Tax (CGST) Act, 2017. It provides a consolidated summary of GST transactions, including outward supplies, inward supplies, input tax credit (ITC), tax paid and other relevant details for a financial year.
For FY 2025-26, taxpayers should understand the applicable late fee structure before filing their annual returns. Late fees are calculated based on the aggregate turnover of the taxpayer and the number of days of delay.
The government has introduced different late fee slabs to provide relief to small and medium-sized taxpayers.
GSTR-9 Due Date for FY 2025-26
The statutory due date for filing GSTR-9 for FY 2025-26 is 31 December 2026, unless extended by the Government through a notification.
Taxpayers should complete their annual return filing within the prescribed time to avoid additional late fees.
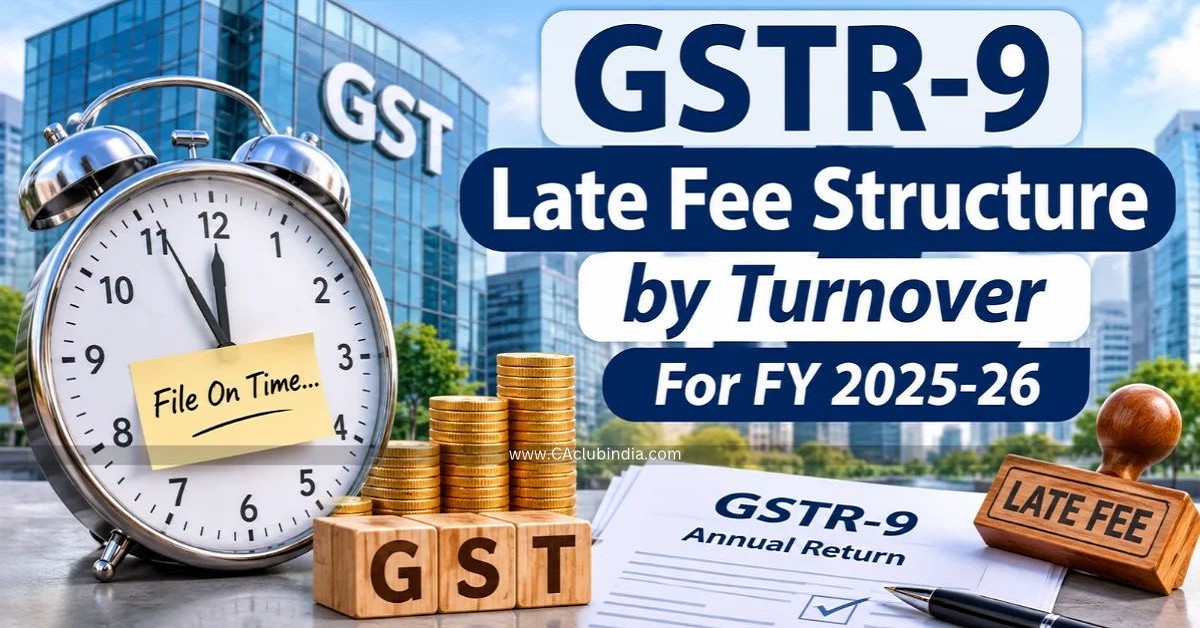
GSTR-9 Late Fee Structure by Turnover for FY 2025-26
The late fee for delayed filing of GSTR-9 is governed by Section 47(2) of the CGST Act, read with Notification No. 07/2023–Central Tax dated 31 March 2023.
The applicable turnover-wise late fee structure is as follows:
| Aggregate Turnover | Late Fee per Day (CGST + SGST) | Maximum Late Fee |
| Up to ₹5 crore | ₹50 (₹25 + ₹25) | 0.04% of State/UT turnover |
| Above ₹5 crore and up to ₹20 crore | ₹100 (₹50 + ₹50) | 0.04% of State/UT turnover |
| Above ₹20 crore | ₹200 (₹100 + ₹100) | 0.50% of State/UT turnover |
Important: The maximum late fee is subject to the applicable statutory limits. The CGST and SGST components are calculated separately.
Also Read - GSTR-9 Due Date For FY 2025-26: Latest Update
Explanation of Turnover-Wise Late Fees
Taxpayers with turnover up to ₹5 crore
Taxpayers having aggregate turnover of up to ₹5 crore are liable to pay a late fee of ₹50 per day for delayed filing of GSTR-9.
- CGST: ₹25 per day
- SGST: ₹25 per day
- Maximum combined late fee: 0.04% of turnover in the relevant State or Union Territory.
Taxpayers with turnover above ₹5 crore and up to ₹20 crore
Taxpayers falling within this turnover category are liable to pay ₹100 per day.
- CGST: ₹50 per day
- SGST: ₹50 per day
- Maximum combined late fee: 0.04% of turnover in the relevant State or Union Territory.
Taxpayers with turnover above ₹20 crore
For taxpayers having aggregate turnover exceeding ₹20 crore, the applicable late fee is ₹200 per day.
- CGST: ₹100 per day
- SGST: ₹100 per day
- Maximum combined late fee: 0.50% of turnover in the relevant State or Union Territory.
GSTR-9 Late Fee Calculation Examples
Let us understand the late fee calculation with practical examples.
Example 1: Aggregate turnover of ₹3 crore
Assume a taxpayer files GSTR-9 30 days after the due date.
| Particulars | Amount |
| Late fee per day | ₹50 |
| Number of delayed days | 30 |
| Total late fee | ₹1,500 |
| Applicable maximum limit | ₹12,000 |
| Late fee payable | ₹1,500 |
Example 2: Aggregate turnover of ₹10 crore
Assume a taxpayer delays filing by 60 days.
| Particulars | Amount |
| Late fee per day | ₹100 |
| Number of delayed days | 60 |
| Total late fee | ₹6,000 |
| Applicable maximum limit | ₹40,000 |
| Late fee payable | ₹6,000 |
Example 3: Aggregate turnover of ₹25 crore
Assume a taxpayer delays filing by 45 days.
| Particulars | Amount |
| Late fee per day | ₹200 |
| Number of delayed days | 45 |
| Total late fee | ₹9,000 |
| Applicable maximum limit | ₹1,25,000 |
| Late fee payable | ₹9,000 |
The examples assume that the entire turnover is attributable to one State or Union Territory. Actual maximum late fee must be calculated using the turnover in the relevant State or Union Territory.
Important Points About GSTR-9 Late Fees
Taxpayers should keep the following points in mind:
- Late fees are calculated for each day of delay after the prescribed due date.
- Both CGST and SGST components are applicable for taxpayers registered under the respective laws.
- The maximum late fee depends on the applicable turnover-based limit.
- Late fees must be paid through the electronic cash ledger and cannot be discharged using input tax credit.
- Filing GSTR-9 does not automatically eliminate any additional tax liability identified during reconciliation.
- Taxpayers should reconcile GSTR-1, GSTR-3B, GSTR-2B and books of accounts before filing the annual return.
Is GSTR-9C Also Required?
FORM GSTR-9C is a reconciliation statement required for taxpayers whose aggregate turnover exceeds ₹5 crore during the financial year.
For applicable taxpayers, GSTR-9C must be self-certified and furnished along with GSTR-9.
As clarified by CBIC Circular No. 246/03/2025-GST dated 30 January 2025, where GSTR-9C is applicable, the annual return is considered complete only when both GSTR-9 and GSTR-9C are furnished.
Late fee is calculated for the delay in furnishing the complete annual return, rather than separately for each form.
Who Is Required to File GSTR-9?
Generally, regular taxpayers registered under GST are required to file GSTR-9, subject to applicable exemptions.
The Government has exempted taxpayers with aggregate turnover up to ₹2 crore from filing GSTR-9 for FY 2024-25 onwards, subject to the relevant notification.
The exemption and applicability should be checked before filing the annual return.
Explore more in details - GSTR 9 Applicability For FY 2025-26: Check Who Must File and Who Is Exempt?
How to Avoid GSTR-9 Late Fees?
Taxpayers can avoid unnecessary late fees by following these steps:
- Reconcile annual sales with GSTR-1.
- Verify tax payments reported in GSTR-3B.
- Reconcile ITC with GSTR-2B.
- Review tax liability and input tax credit differences.
- Verify amendments, credit notes and debit notes.
- Prepare GSTR-9 and GSTR-9C, wherever applicable, before the due date.
- Complete filing before 31 December 2026, unless the due date is officially extended.
Conclusion
The GSTR-9 late fee structure for FY 2025-26 varies according to the aggregate turnover of the taxpayer. The applicable combined late fee ranges from ₹50 to ₹200 per day, subject to the prescribed maximum limits.
Taxpayers should review their annual GST records, reconcile their returns and file GSTR-9 within the due date to avoid additional compliance costs.
Stay updated with GST notifications, annual return requirements and tax compliance developments to ensure timely and accurate GST filing.
FAQs
1. What is the late fee for GSTR-9 for FY 2025-26?
The late fee depends on the taxpayer's aggregate turnover:
- Up to ₹5 crore: ₹50 per day.
- Above ₹5 crore and up to ₹20 crore: ₹100 per day.
- Above ₹20 crore: ₹200 per day.
These amounts include CGST and SGST components and are subject to prescribed maximum limits.
2. Is GSTR-9 mandatory for taxpayers having turnover below ₹2 crore?
Taxpayers having aggregate turnover up to ₹2 crore are exempted from filing GSTR-9 for FY 2024-25 onwards, subject to the applicable government notification. The applicable exemption should be checked for FY 2025-26 before filing.
3. How is the maximum late fee for GSTR-9 calculated?
The maximum combined late fee is calculated as follows:
- Turnover up to ₹5 crore: 0.04% of turnover in the relevant State or Union Territory.
- Turnover above ₹5 crore and up to ₹20 crore: 0.04% of turnover in the relevant State or Union Territory.
- Turnover above ₹20 crore: 0.50% of turnover in the relevant State or Union Territory.
4. Is GSTR-9 late fee calculated on aggregate turnover or State-wise turnover?
The applicable daily late fee slab is determined based on aggregate turnover for the financial year. However, the maximum late fee is calculated based on turnover in the relevant State or Union Territory.
5. Can GSTR-9 late fees be paid using Input Tax Credit (ITC)?
No. Late fees must be paid through the electronic cash ledger. Input Tax Credit cannot be used to discharge the late fee liability.







 CAclubindia
