Section 185 of Companies Act 2013: Restrictions on Director Loans


Quick Summary
Section 185 of the Companies Act 2013 generally prohibits companies from providing loans, advances, guarantees, or securities to their directors, holding company directors, directors' relatives, or business partners. However, there are specific exceptions. Loans to managing or full-time directors are permitted if they align with employee service conditions or are approved by a special resolution. Companies can also provide loans, guarantees, or securities in their ordinary course of business, provided the interest rate is at least as high as current government security yields.

Section 185 of Companies Act 2013 prohibits companies from giving loans. According to Section 184(1) of the Act, a company may not directly or indirectly make an advance loan, make an advance loan that is expressed by a book debt, give a guarantee or security in conjunction with any borrowed money -

  • To its Director
  • To its holding company's Director
  • To Director's Relatives
  • To the business partner, if the Director is a partner
  • To the partnership firm in which the company's Director or holding company is Partner.

Exceptions of Section 185: Providing Loans To its Directors

1.Companies that provide business loans to its Managing Directors or full time Directors are required to do so with the following terms:

  • Conditions of service provided to all of their workers, or
  • In accordance with a plan approved by special resolution.

2.Companies offering loans , guarantees and securities in the regular course of business charge interest that is at least as high as the current yield on government securities with terms of one year, three years, five years or ten years.

Remuneration to Director u/s 197
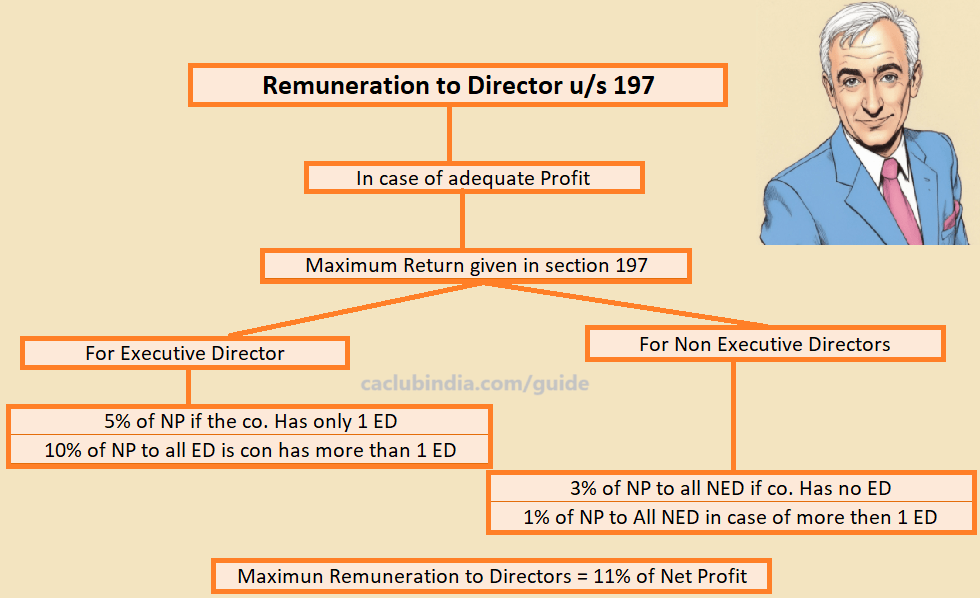
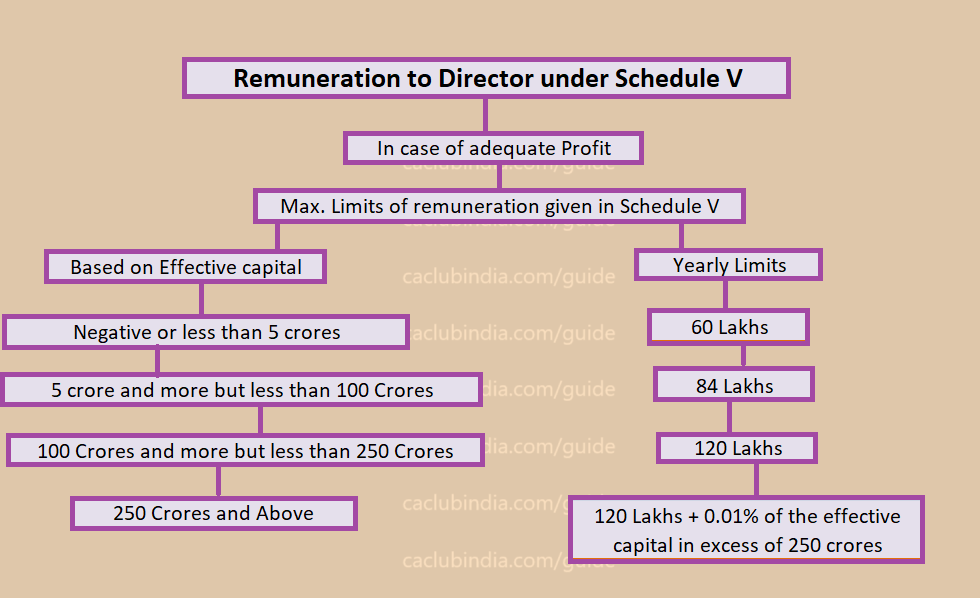
Remuneration to Director under Schedule V
Penalty Provisions

Penalties may attract if a company contravenes the provisions of Section 185 of Companies Act 2013 regarding loans, guarantees, or securities to directors or related parties:

  • Company: Fine of Rs 5 lakhs to Rs 25 lakhs.
  • Director/Recipient: Fine of Rs 5 lakhs to Rs 25 lakhs or imprisonment up to 6 months, or both.

Click here to know more about Remuneration of Directors.


About the Author

pro badge

Finance Professional

I write about Income Tax, GST, TDS, RBI updates, government schemes, and personal finance in India. My focus is on simplifying complex tax and compliance topics into easy-to-understand guides that help readers stay updated with the latest financial rules, investment options, and regulatory changes.

Comments :

Related Articles


Loading


Popular Articles


CCI Pro

CCI Articles

submit article


Company
08 October 2026
Account Executive

Elite Taxation

New Delhi

CA Foundation

View Details
Company
07 October 2026
Senior Account Manager

Amplio Invest

Mumbai

M.Com

View Details
Company
Featured 03 October 2026
Accountant

A P Lodha and Associates

Jalna

B.Com

View Details
Company
ARTICLESHIP 28 September 2026
Junior Accountant

J S P M & Associates LLP

Pune

B.Com

View Details
Company
ARTICLESHIP 30 September 2026
CA Article Assistant

CA Suraj Garg & Associates

New Delhi

CA Final

View Details
Company
30 September 2026
Senior Accounts Executive

Codeboard Technology

Chennai

MBA

View Details
Company
26 September 2026
Chartered Accountant

pushpganga ventures

Pune

CA

View Details
Company
Featured 21 September 2026
Consultant - Reporting

Finrep Advisors LLP

Mumbai

CA

View Details