 Poojitha Raam Vinay
The Ministry of Finance notifies small savings rates every quarter. For the October–December 2026 quarter, rates were left unchanged for the tenth quarter in a row:
- SCSS: 8.2% per annum, paid quarterly
- NSC (VIII Issue): 7.7% per annum, compounded annually and paid at maturity
For both schemes, the rate on the day you invest is locked for the full five-year term. A later rate cut or hike does not affect your existing deposit, which makes the timing of your purchase relevant only at the point of investing.
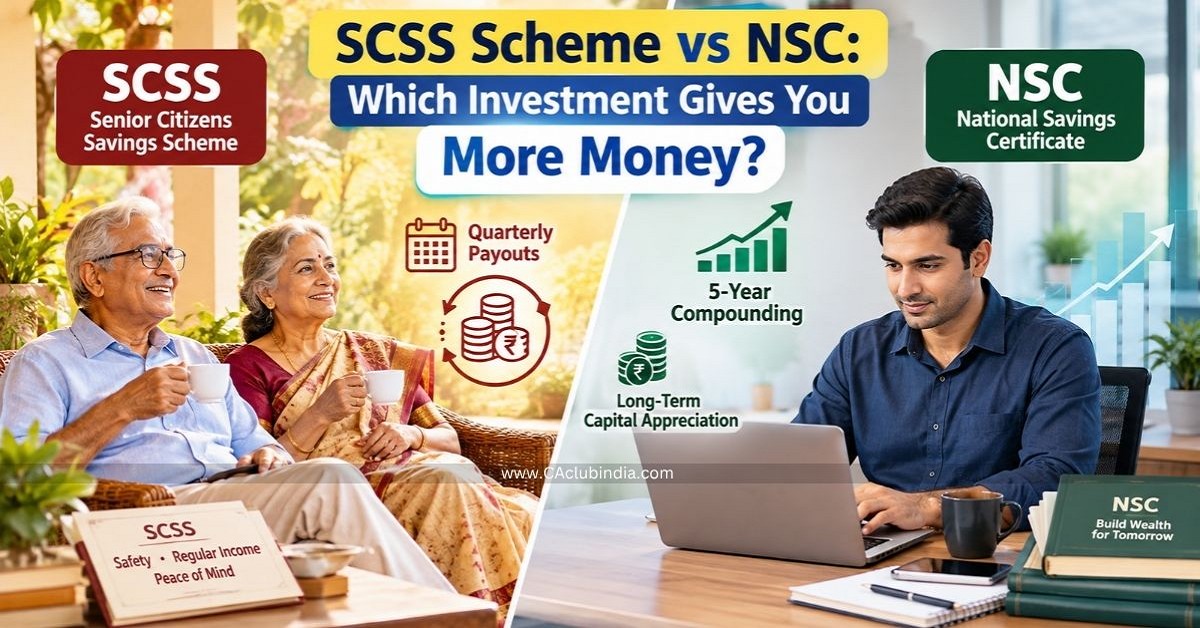
SCSS vs NSC Side by Side
| Feature | SCSS | NSC (VIII Issue) |
| Interest rate (Oct–Dec 2026) | 8.2% p.a. | 7.7% p.a. |
| Who can invest | Age 60+; 55–60 if retired under superannuation or VRS; 50–60 for retired defence personnel | Any resident adult; minors through a guardian |
| Tenure | 5 years, extendable once by 3 years | 5 years |
| Minimum investment | ₹1,000 (in multiples of ₹1,000) | ₹1,000 |
| Maximum investment | ₹30 lakh | No limit |
| How interest is paid | Quarterly payout to your account | Compounded yearly, paid at maturity |
| Tax on interest | Taxable at slab rate when received | Taxable at slab rate every year on accrual |
| TDS | Yes, above the senior citizen TDS threshold | No TDS |
| Section 80C deduction | Yes (old regime), up to ₹1.5 lakh | Yes (old regime), up to ₹1.5 lakh |
| Premature exit | Allowed after 1 year with a penalty | Generally not allowed |
| Safety | Government of India backed | Government of India backed |
NRIs and HUFs cannot invest in either scheme. Joint SCSS accounts are allowed only with a spouse.
The takeaway: NSC can show a bigger lump sum than SCSS, but only because compounding happens automatically inside NSC. SCSS has the higher rate; to turn that into a bigger pile you must reinvest the payouts yourself. If you need the income, SCSS delivers more per rupee of capital. If you do not need income, a disciplined reinvestment of SCSS payouts overtakes NSC, while a lazy one does not.
Also Read - Senior Citizen Saving Scheme with 5 New Rules
Post-Tax Returns by Tax Slab
Both schemes are taxable, so what you keep depends on your slab. The table below uses the slab rate plus 4% health and education cess. For NSC, the yearly tax on accrued interest is assumed to be paid from your pocket, as there is no TDS. The post-tax yield is the effective annual return on ₹10 lakh over five years.
| Slab (with 4% cess) | SCSS post-tax yield | NSC post-tax yield | SCSS net interest, 5 yrs (payouts not reinvested) | NSC net interest, 5 yrs |
| Nil tax | 8.20% | 7.70% | ₹4,10,000 | ₹4,49,034 |
| 5% (5.2%) | 7.77% | 7.30% | ₹3,88,680 | ₹4,25,684 |
| 10% (10.4%) | 7.35% | 6.90% | ₹3,67,360 | ₹4,02,334 |
| 20% (20.8%) | 6.49% | 6.10% | ₹3,24,720 | ₹3,55,635 |
| 30% (31.2%) | 5.64% | 5.30% | ₹2,82,080 | ₹3,08,935 |
How to read this: at every slab, SCSS gives a higher post-tax yield than NSC. The gap is about 0.3 to 0.5 percentage points. The last two columns show the rupee interest over five years when SCSS payouts are simply spent, which is why NSC looks larger there. Compare the yield columns for like-for-like returns, and the rupee columns for the cash you actually hold at the end if you do nothing with the payouts.
One more point: tax at the 30% slab takes a large bite from both. A senior with little taxable income, such as a pensioner within the exemption or rebate limit, keeps nearly the entire 8.2% from SCSS, which is where this scheme is hardest to beat.
Tax Treatment
Section 80C deduction
Both SCSS deposits and NSC purchases qualify for the deduction of up to ₹1.5 lakh a year under the old tax regime (the corresponding provision applies under the Income-tax Act, 2025, effective 1 April 2026). It is not available if you opt for the new tax regime, which is the default. At the 30% slab with cess, a full ₹1.5 lakh deduction saves up to ₹46,800 of tax, which effectively adds to the return of the year you invest.
For NSC, interest for the first four years is treated as reinvested and also qualifies for the deduction, within the same ₹1.5 lakh cap. Check that you are not double counting with PPF, EPF, life insurance premiums or tuition fees, which share that ceiling.
TDS
- SCSS: The post office or bank deducts TDS on interest once it crosses the senior citizen threshold (₹1 lakh a year following the Budget 2025 change). On a ₹30 lakh deposit, annual interest is ₹2,46,000, so TDS applies. If your total income is below the taxable limit, you can submit Form 15H to avoid it.
- NSC: No TDS. But the interest is still taxable every year, so remember to report the accrued interest in your return even though you will not see the money until maturity.
Thresholds and section numbers have moved with the new Income-tax Act, so verify the current provisions before filing.
Premature closure and liquidity
SCSS can be closed after one year. A deduction of 1.5% of the deposit applies if you close after one year but before two years, and 1% after two years. Closing within the first year earns no interest, and any interest already paid is recovered from the principal.
NSC is far less flexible. Premature encashment is generally not allowed, with exceptions such as the holder's death or a court order. You can, however, pledge the certificate to a bank as security for a loan.
If you may need the money before five years, SCSS is the safer pick of the two. If you will not touch it, this difference matters less.
Who should choose which?
| Your situation | Better fit | Why |
| Retiree who needs regular income | SCSS | Higher rate and ₹20,500 per ₹10 lakh every quarter |
| Senior in a low or nil tax bracket | SCSS | Keeps most of the 8.2% |
| Senior with more than ₹30 lakh to place | SCSS first, NSC for the excess | SCSS is capped; NSC has no limit |
| Below 60 and not eligible for SCSS | NSC | It is the only one of the two you can buy |
| Wants growth without handling payouts | NSC | Compounds automatically, one lump sum at maturity |
| Old-regime taxpayer chasing 80C | Either | Both qualify; pick on eligibility and cash flow |
| May need cash early | SCSS | Allows exit after one year |
Common mistakes to avoid
- Forgetting NSC interest is taxable every year. Many investors report it only at maturity and receive a notice.
- Comparing only the headline rate. A quarterly payout and a compounding certificate are not like for like.
- Ignoring the ₹30 lakh SCSS cap when planning a large retirement corpus.
- Skipping Form 15H when income is below the taxable limit, which locks money in TDS until refund.
- Assuming 80C applies in the new regime. It does not.
FAQs
Which is better, SCSS or NSC?
On rate, SCSS: 8.2% against 7.7%. SCSS also pays quarterly income and allows an early exit. But it is open only to seniors and capped at ₹30 lakh, so for most investors NSC is the only choice of the two.
What are the current SCSS and NSC interest rates?
For October to December 2026, SCSS earns 8.2% and NSC earns 7.7%. Rates have been unchanged for ten consecutive quarters, and the rate on your investment date stays fixed for the five-year term.
Can someone below 60 invest in SCSS?
Generally no. Those aged 55 to 60 who retired under superannuation or VRS, and retired defence personnel aged 50 to 60, can open an account within the prescribed time after receiving retirement benefits. NRIs and HUFs are not eligible.
Is the interest on SCSS and NSC taxable?
Yes, for both, at your slab rate. SCSS interest is taxed when received. NSC interest is taxed every year on accrual even though it is paid only at maturity.
Is TDS deducted on SCSS and NSC?
SCSS interest attracts TDS above the senior citizen threshold (₹1 lakh a year after Budget 2025), and eligible seniors can submit Form 15H. NSC has no TDS, so you pay the tax yourself.
Do SCSS and NSC qualify for Section 80C?
Yes, both qualify for up to ₹1.5 lakh under the old regime. The deduction is not available under the new regime. At a 30% slab with cess, the saving is up to ₹46,800.
What is the maximum investment in SCSS and NSC?
SCSS: ₹30 lakh per investor. NSC: no upper limit, though 80C relief is capped at ₹1.5 lakh.
Can I close SCSS or NSC before maturity?
SCSS can be closed after one year with a 1.5% or 1% deduction. NSC generally cannot, except in cases such as death or a court order. NSC can be pledged for a loan.







 CAclubindia
