 Shivangi Goswami
Have you received a large cash payment, deposited cash into your bank account, bought or sold property, or withdrawn a substantial amount from the bank? If so, you may be wondering:
"Can the Income Tax Department question me about this cash transaction?"
The short answer is yes, it can. However, a large cash transaction is not automatically illegal, and crossing a reporting threshold does not mean you have done anything wrong.
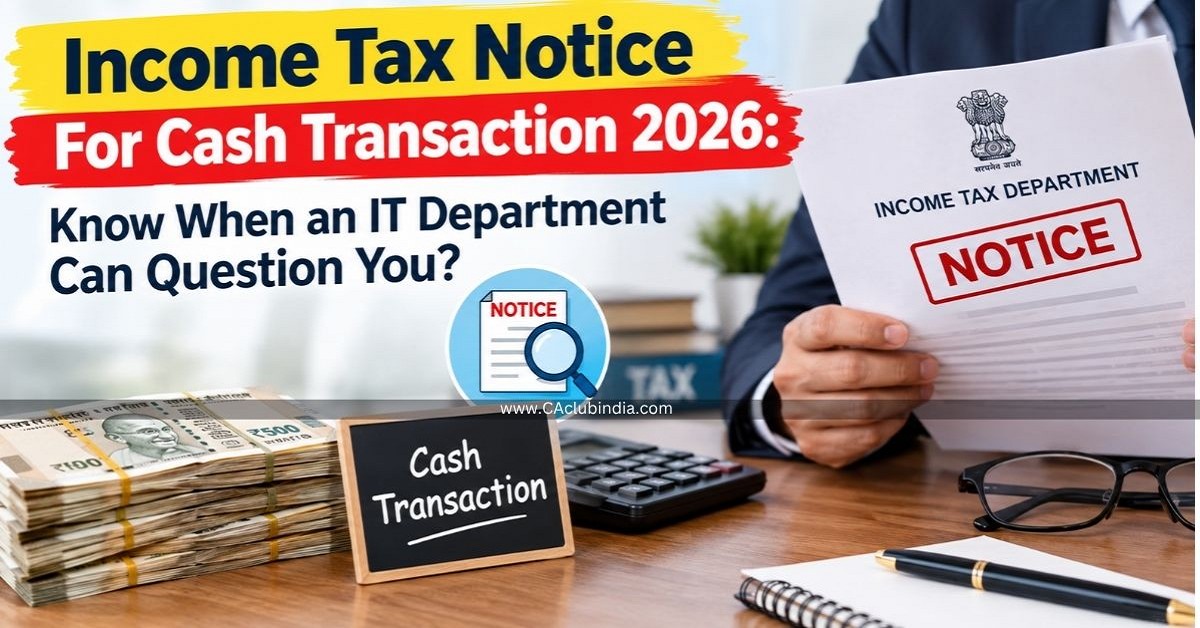
What has changed is how visible these transactions are. In 2026, banks, financial institutions, registrars and other reporting entities share specified financial information with the tax authorities through the Statement of Financial Transactions (SFT) framework. This information feeds into the department's data systems and may appear in your Annual Information Statement (AIS). Tax law also restricts certain cash transactions.
A Cash Deposit Is Not Automatically a Tax Problem
Depositing ₹12 lakh in your savings account does not automatically mean you will receive a tax notice.
Banks must report cash deposits that add up to ₹10 lakh or more in a financial year across your savings and other non-current accounts. The test is the annual total, not a single deposit: ten deposits of ₹1 lakh each are treated the same as one deposit of ₹10 lakh. For current accounts, the reporting threshold is ₹50 lakh in a financial year. SFT reporting does not mean the amount is taxable income.
Related Guide:
PAN Requirement
Under the Income-tax Rules, 2026, which took effect on 1 April 2026, you must quote your PAN when your cash deposits or withdrawals add up to ₹10 lakh in a financial year across your accounts. The earlier trigger of ₹50,000 in a single day no longer applies.
For example, if you withdraw ₹8 lakh and later redeposit the same money, you can explain the deposit using your bank records. Similarly, genuine business receipts, agricultural income or proceeds from a disclosed asset sale are not taxable merely because they were received in cash.
The real problem arises when you cannot explain the source of the cash.
When Can the Department Question Your Cash?
A cash transaction may become relevant for verification where there is a mismatch or an unusual pattern, such as:
- Cash deposits substantially exceeding the income or turnover disclosed in your ITR
- Bank deposits not matching the cash book or books of account
- Cash sales not matching reported turnover
- Differences between GST turnover and income-tax records, where GST applies
- SFT/AIS information not reconciled with the return
- Large cash withdrawals followed by cash redeposits without a satisfactory explanation
- Substantial cash activity inconsistent with your disclosed business or financial profile
In short, cash transactions attract attention when they are large, unusual or difficult to explain.
Cash deposits don't match your income
If you declare an income of ₹6 lakh but deposit ₹22 lakh in cash, the department may ask where the money came from. If it is genuine savings, business income, an asset sale or another legitimate source, keep documents to support it.
The transaction appears in SFT/AIS
Certain high-value transactions are reported to the tax department, including:
- Cash deposits totalling ₹10 lakh or more in a financial year in savings or specified noncurrent accounts
- Cash deposits or withdrawals totalling ₹50 lakh or more in a financial year in current accounts
- Certain high-value cash payments and property transactions of ₹30 lakh or more.
Being reported does not automatically make a transaction taxable.
You receive ₹2 lakh or more in cash
Section 269ST of the Income-tax Act, 1961 (Section 186 of the Income-tax Act, 2025) generally restricts receiving ₹2 lakh or more in cash:
- from one person in a day,
- for a single transaction, or
- for transactions related to one event or occasion.
The penalty can be 100% of the amount received, subject to the law and its exceptions.
You take or repay large cash loans
Cash loans, deposits and certain advances of ₹20,000 or more are generally restricted under Section 269SS (Section 185 of the new Act) and Section 269T (Section 188 of the new Act). So even if a ₹5 lakh loan from a friend is not taxable income, accepting or repaying it in cash can still create a compliance problem.
Businesses can lose deductions
Under Section 40A(3) (Section 36 of the new Act), a business that pays more than ₹10,000 in cash to one person in a day can lose the deduction for the entire payment, not just the excess, unless a prescribed exception applies. The limit is ₹35,000 for payments to transporters for goods carriages. For example, paying a supplier ₹15,000 in cash in one day can make the whole ₹15,000 non-deductible. Genuine expenses can therefore become non-deductible if paid in cash incorrectly.
Large cash withdrawals can attract TDS
Under Section 194N (now covered by Section 393 (3), Table Sl. No. 5 of the new Act), banks may deduct TDS when cash withdrawals cross prescribed limits. Generally, the threshold is ₹1 crore for those who have filed their returns in recent years and ₹20 lakh for non-filers. TDS on a cash withdrawal does not mean the withdrawn money is taxable income.
The biggest risk is not using cash itself. It is using cash without a clear source, purpose or proper records, or without complying with the applicable limits.
Also Read - TDS Rules on Cash Withdrawals 2026
The Most Serious Issue: Can You Explain the Source?
This is where cash transactions become genuinely risky.
Section 69A (Section 104 of the new Act) allows unexplained money, bullion, jewellery or other valuable assets to be treated as income if the taxpayer cannot satisfactorily explain their nature and source. Such income is taxed at a special flat rate under Section 115BBE (Section 195 of the new Act), with no deduction for expenses and no set-off of losses.
The rate depends on when the income arose:
- Up to 31 March 2026 (old Act): 60% tax, plus a 25% surcharge and 4% cess, which works out to about 78% in total, along with a possible 10% penalty on the tax.
- From 1 April 2026 (new Act): The Finance Act, 2026 reduced the base rate to 30%, which works out to about 39% including surcharge and cess.
However, the lower rate is not a free pass. If the Assessing Officer, rather than you, identifies the income, the penalty can go up to 200% of the tax under the misreporting provisions (Section 439 of the new Act), and the earlier standalone 10% penalty has been removed.
Declaring the income yourself in your return generally avoids the misreporting penalty, though the special tax still applies.
That is why, for a large cash deposit, the most important document is often not the deposit slip but the evidence showing where the cash came from and why it was received.
Final Takeaway
The Income Tax Department's approach to cash is becoming increasingly data-driven. But the lesson for taxpayers is not "never use cash." It is:
Never let a significant cash transaction exist without a clear, credible and documented trail.
Check your AIS, reconcile your bank accounts, maintain proper books, and keep invoices, sale agreements, withdrawal records, loan documents and other supporting evidence safe.
Remember, an SFT entry is only a data point, not a finding of tax evasion. Likewise, a tax notice is an opportunity to explain a transaction, not automatically a finding of wrongdoing. The taxpayers who stay safest in 2026 will not necessarily be those who never handle cash. They will be those who can confidently answer one simple question: "Where did this money come from?" and back that answer with clear, credible documents.







 CAclubindia
