 CA. Keshav Kumar
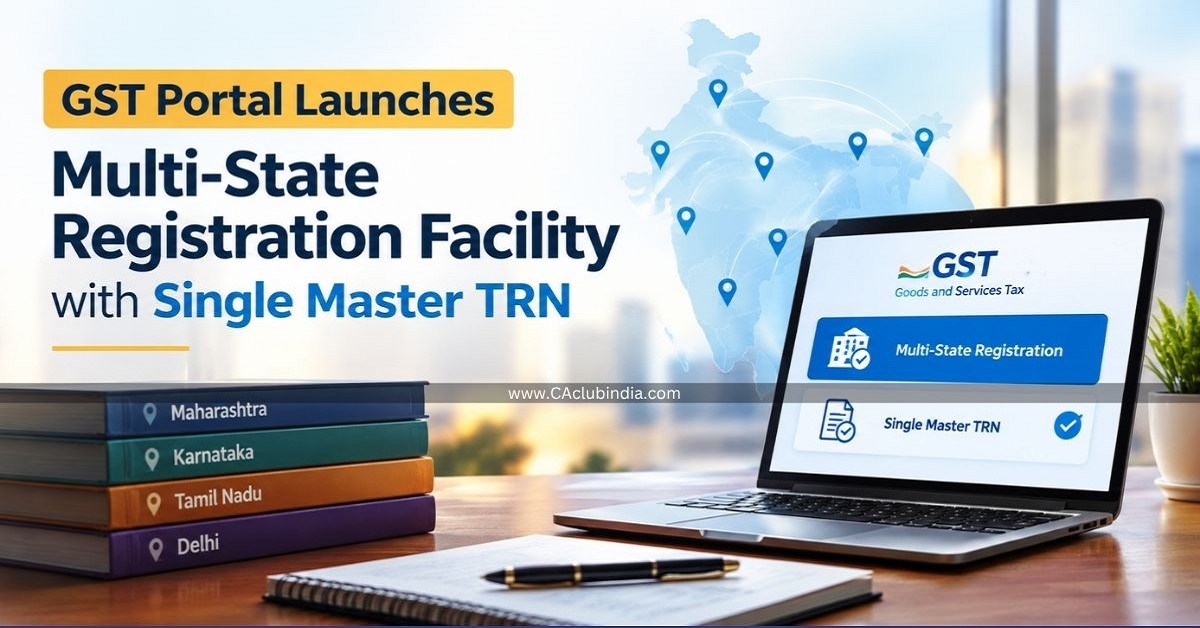
With effect from 1 October 2026, the home page of the GST Common Portal carries a third option, "Multi-State Registration", beside "Register" and "Login". Through it, an applicant holding one PAN can initiate registration applications for several States and Union Territories in a single sitting. The applicant enters the common particulars once, receives one Master Temporary Reference Number (Master TRN), and on its submission receives a separate TRN for each State or Union Territory selected.
The facility alters the manner in which applications are initiated. It does not alter the law of registration. Each State or Union Territory continues to have its own application in FORM GST REG-01, its own scrutiny by the jurisdictional officer, and its own GSTIN. No notification, circular or GSTN advisory describing the facility was available on the official portals at the time of writing, and the position stated here is therefore confined to what the portal itself displays and to the existing statutory framework.
Statutory position: registration is State-specific
Registration under GST attaches to the State or Union Territory from which a taxable supply is made, not to the PAN. The consequence is that one legal entity holds as many registrations as the States from which it supplies. The provisions that produce this result are set out below.
|
Provision |
Substance |
|---|---|
|
Section 22(1), CGST Act, 2017 |
A supplier is liable to be registered in the State or Union Territory from where the taxable supply is made, once aggregate turnover exceeds the prescribed threshold. |
|
Section 24 |
Specified categories are liable to registration irrespective of turnover. |
|
Section 25(1) |
Application is to be made in every State or Union Territory in which the person is so liable, within thirty days of becoming liable. |
|
Section 25(2) and Rule 11 |
A single registration is granted in a State or Union Territory; a person with multiple places of business in one State may obtain a separate registration for each. |
|
Section 25(4) and 25(5) |
Each registration of the same person is treated as a distinct person, and establishments in different States are treated as establishments of distinct persons. |
|
Rule 8, CGST Rules, 2017 |
Part A of FORM GST REG-01 captures PAN, mobile number, e-mail address and State or Union Territory; on validation and OTP verification a TRN is generated for completing Part B. |
|
Rules 9 and 10 |
The proper officer verifies the application, may seek clarification in FORM GST REG-03, and grants the registration certificate in FORM GST REG-06. |
Two features of this framework matter for the present discussion. First, the State or Union Territory is declared in Part A itself, so that under Rule 8 one Part A yields one TRN for one State. Secondly, the distinct person rule in Section 25(4), read with paragraph 2 of Schedule I, makes supplies between two registrations of the same entity taxable even without consideration.
The procedure until 30 September 2026
An entity requiring registration in several States had to begin a fresh application for each of them through Services > Registration > New Registration. Every application required the legal name, PAN, e-mail address and mobile number to be entered afresh, followed by a separate OTP verification and a separate TRN.
An entity entering five States thus keyed in the same Part A particulars five times and tracked five unconnected TRNs. Under the standard registration flow, a TRN remains available for fifteen days, after which the draft application lapses. The exercise was repetitive rather than difficult, but it was a recurring source of mismatched particulars across applications of the same PAN.
How the Multi-State Registration facility works
The facility consolidates the Part A stage for all the States selected and then hands over to the ordinary State-wise process. It is reached from the "Multi-State Registration" button on the portal home page, which opens the page at reg.gst.gov.in/registration/msr. The sequence displayed on the portal is as follows.
- The applicant category is shown as "Taxpayer" and is not editable; the facility is at present confined to normal taxpayers.
- The States and Union Territories in which registration is sought are chosen from a multi-select list.
- The legal name of the business as per PAN, the PAN, the e-mail address and the mobile number are entered once.
- The e-mail address and mobile number are verified through OTP.
- A single Master TRN is generated for the entire set of States selected.
- On submission of the Master TRN, the system generates a State-specific TRN for each State or Union Territory selected.
- Each State-specific TRN is then used to complete and submit that State's application, into which the common profile particulars are carried.
The portal states one condition expressly: several States and Union Territories may be selected, but only one registration can be applied for in a particular State or Union Territory under one Master TRN. An entity requiring a second registration within the same State under the proviso to Section 25(2) cannot, therefore, obtain it through the same Master TRN.
By way of illustration, a company with its principal place of business in Delhi that proposes to open warehouses in Haryana, Maharashtra and Karnataka selects the three States in one flow. It receives one Master TRN, then three State-specific TRNs, and, upon approval of each application, three GSTINs.
|
Particulars |
Earlier procedure |
Multi-State Registration |
|---|---|---|
|
Initiation |
Separate application for each State |
One flow with all States selected |
|
Entry of PAN, legal name, e-mail, mobile |
Repeated for each State |
Entered once |
|
OTP verification |
For each application |
Once, at the common stage |
|
Reference number |
One TRN per application, unconnected |
One Master TRN, followed by State-specific TRNs |
|
Part B, documents and verification |
State-wise |
State-wise |
|
Registrations granted |
One GSTIN per State |
One GSTIN per State |
What the facility does not change
The facility is not a centralised or single registration. Section 25 has not been amended, and the portal continues to issue a separate GSTIN for every State or Union Territory. The following therefore remain exactly as before.
- Separate applications. Each State-specific TRN leads to an independent Part B, requiring the principal place of business in that State, the nature of possession of the premises and supporting documents, the goods or services to be supplied, and the authorised signatory.
- Aadhaar authentication. Rule 8(4A) continues to apply, including biometric-based Aadhaar authentication and document verification at a GST Suvidha Kendra where the applicant is so identified.
- Independent scrutiny. Each application is processed by the proper officer of the State concerned under Rule 9. One application may be approved while another attracts a notice in FORM GST REG-03 or is rejected in FORM GST REG-05.
- Post-registration obligations. Each GSTIN carries its own returns, payment of tax, records and furnishing of bank account details under Rule 10A.
- Distinct person consequences. Stock transfers between the registrations are taxable supplies under Schedule I, and credit of common input services is to be distributed through the Input Service Distributor mechanism under Section 20.
A TRN, whether Master or State-specific, is a reference to a draft application. It is neither an acknowledgement of a filed application nor a registration, and no supply can be made on its strength.
Points awaiting official clarification
The functionality has been deployed on the portal without an accompanying advisory or user manual, and several operational questions cannot be answered from the screen alone.
|
Point |
Position at present |
|---|---|
|
Validity of the Master TRN |
Not stated. The fifteen-day life of an ordinary TRN should not be assumed to apply to the Master TRN or to run afresh for each State-specific TRN. |
|
Other categories of applicant |
The category is locked to "Taxpayer". Casual taxable persons, non-resident taxable persons, tax deductors, tax collectors and other categories remain on the regular route. |
|
Entities already holding a GSTIN |
The portal does not indicate whether an existing registrant adding further States is treated differently from a first-time applicant. |
|
Extent of auto-population |
The common profile is carried into the State applications; which Part B fields are pre-filled, and whether they are editable, is to be seen application by application. |
|
Aadhaar authentication |
It is unclear whether authentication of the same promoters and authorised signatory is required once or separately for each State application. |
|
Simplified registration under Rule 14A |
Whether the option under Rule 14A can be exercised within State applications generated through a Master TRN is not specified. |
|
Addition or removal of a State |
Whether the selection can be modified after the Master TRN is generated is not specified. |
Until GSTN issues an advisory, these points are best resolved by reference to what the portal permits at each step, with screenshots retained.
Practical considerations before using the facility
The ease of selecting several States at once should not lead to registrations that the law does not require. Section 22 fastens liability on the State from where the supply is made. Customers located in another State do not, by themselves, call for registration there; a place of business from which supplies are made does.
The following points deserve attention before the Master TRN is generated.
- Readiness of every State. Proof of the principal place of business, consent or lease documents and the authorised signatory's particulars should be in hand for each State selected, since the State-specific TRNs are generated together.
- Accuracy of common particulars. The legal name, PAN, e-mail address and mobile number flow into every State application. An error at the common stage is replicated across all of them.
- Thirty-day limit. The period under Section 25(1) runs separately for each State from the date liability arises there. Initiating the applications together does not extend it.
- Parallel timelines. Notices in FORM GST REG-03 carry their own reply period in each State. A tracker of TRN, ARN, officer queries and due dates for every State is advisable.
- Consequences of an avoidable registration. Every additional GSTIN brings periodic returns, annual return obligations and the distinct person rule. Cancellation under Section 29 is a separate proceeding with its own final return.
- Systems readiness. Invoicing series, e-invoice and e-way bill enablement, and ISD and cross-charge arrangements should be planned State-wise before the registrations become effective.
Where only one additional State is required, the regular "Register" route remains available and is unaffected.
Conclusion
The Multi-State Registration facility is a procedural improvement at the Part A stage. It removes repetitive data entry and links the State-wise applications of one PAN through a Master TRN. It does not centralise registration, reduce the number of GSTINs, or relax documentation and verification in any State.
Entities expanding into several States may use it to initiate their applications together, provided each State's documents are ready and the liability to register there has been examined. The operational details recorded above as unsettled should be revisited once GSTN publishes its advisory.
References
- Central Goods and Services Tax Act, 2017: Sections 20, 22, 24, 25 and 29; Schedule I, paragraph 2
- Central Goods and Services Tax Rules, 2017: Rules 8, 9, 10, 10A, 11 and 14A; FORM GST REG-01, REG-03, REG-05 and REG-06
- GST Common Portal, Multi-State Registration page: reg.gst.gov.in/registration/msr, live from 1 October 2026
Disclaimer: This article is intended for general information and academic discussion only. It is based on the provisions of law and the functionality available on the GST Common Portal as on the date of writing, both of which are subject to change. It does not constitute professional advice or opinion. Readers should refer to the relevant statutory provisions, notifications and official advisories, and obtain specific advice, before acting on any matter discussed here. The views expressed are personal to the author.
You have reached your daily limit of 2 Free Articles
Subscribe to CCI PRO for unlimited access
Why Upgrade to CCI PRO?
- No Ads
- WhatsApp Community
- Daily E-Newsletter
- Unlimited Articles Access
- Profile Visitors
- Link Social Profiles
- Featured Job Posts
- Pro Badge
- Expert GST Guidance
- Unlimited Forum Replies
- Download Content in PDF
Already a PRO member? Login here for an ad-free experience. 011-411-70713







 CAclubindia
