
Opening your email and seeing a message from the Income Tax Department can be stressful.
Many taxpayers assume the worst. In reality, a large share of today's income tax notice cases are system-generated. They arise when the income or tax credit in your return does not match the data the department already holds.
This guide explains how to read such a notice, what to do within the time limit, and which mistakes make a simple mismatch more expensive than it needs to be.
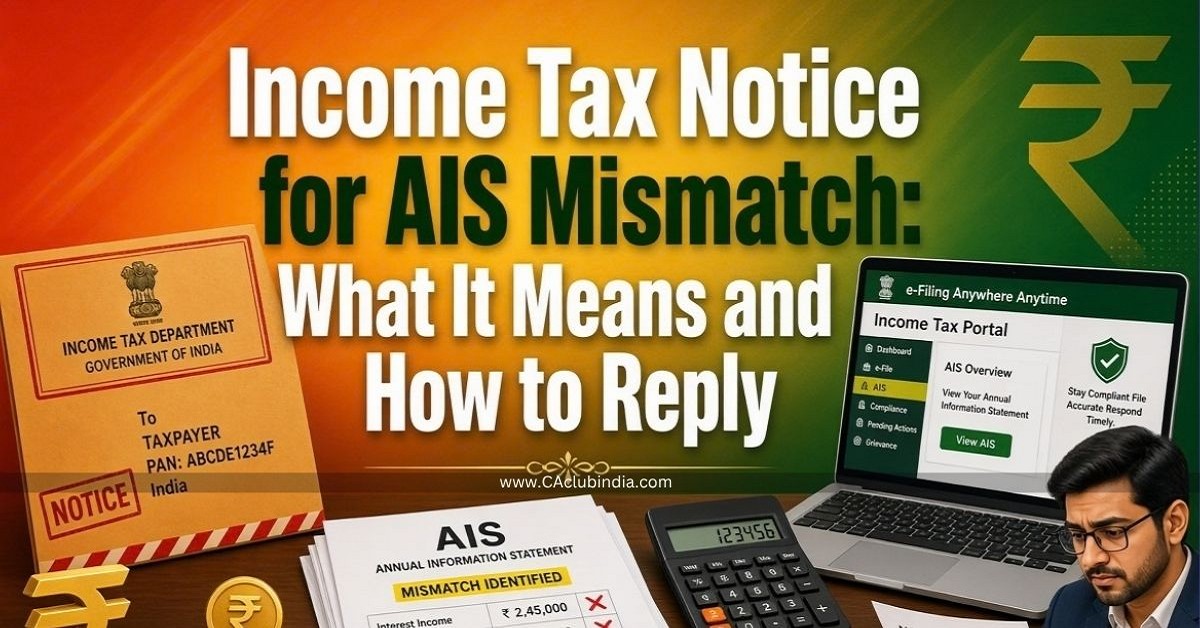
Why Are Income Tax Notices Increasing?
Banks, employers, deductors, brokers and registrars report your transactions to the department. This data appears in your Annual Information Statement (AIS) and Taxpayer Information Summary (TIS) , along with Form 26AS. When you file your return, the system compares it with this data.
If something does not match, for example interest income shown in AIS but missing from your ITR, the system flags it. The flag may be an honest oversight, a reporting error by the deductor, or a genuine difference that needs explaining.
Intimation, Notice or Scrutiny: Know the Difference
These terms are often mixed up, so start here.
- Intimation under Section 143(1): This is the result of processing your return. It is a communication, not an accusation. It may show a refund, a demand or no change.
- Proposed adjustment under Section 143(1)(a): Before making an adjustment that increases your liability, the system gives you a chance to respond. This is where most AIS and TDS mismatches appear.
- Notice under Section 143(2): This signals a detailed scrutiny of the return and needs a more careful, document-backed response.
- Other notices: These include inquiry notices under Section 142(1), reassessment-related notices and demand notices. Each has its own time limit and procedure.
Reading the section number on the first page tells you how serious the matter is and how much time you have.
Which law applies? For FY 2025-26 (AY 2026-27), the Income-tax Act, 1961 still applies, so these section numbers are valid for your current return. From FY 2026-27 onwards, the Income Tax Act 2025 applies, with new numbering. Always check the year mentioned in the notice.
Common Reasons for an AIS or TDS Mismatch
- Interest income not reported. Savings, fixed deposit or other interest in AIS that is missing from the ITR.
- Dividend or other income omitted. Small amounts are easy to forget.
- TDS credit mismatch. The TDS you claimed does not match Form 26AS or the deductor's filing
- Wrong figures from Form 16. Salary or deduction details differ from the employer's data.
- Incorrect deduction or exemption claims. Claims without matching documentation can be adjusted.
- High-value transactions. Large cash deposits, property deals or investments that appear in AIS but are not explained in the return.
What to Do When You Receive an Income Tax Notice
Step 1: Do not panic, and do not ignore it
Read the notice fully. Note the section, the assessment year, the response deadline and the exact mismatch.
Step 2: Verify it is genuine
Fake notices and phishing emails do exist. A genuine notice appears on your e-filing account under your pending actions. Do not click unknown links, and do not share passwords or OTPs. If in doubt, log in to the official portal directly and check.
Step 3: Match the data
Compare your ITR with AIS, TIS, Form 26AS and Form 16. Find out whether the department is right, the data is wrong, or both of you are partly right.
Step 4: Reply within the time limit
For a proposed adjustment under Section 143(1)(a), you generally have 30 days from the notice date to respond. Log in to the e-filing portal, go to Pending Actions, open e-Proceedings, and review the adjustment. You can then agree or disagree with each mismatch.
If you do not respond in time, the return is processed with the proposed adjustments, and the demand follows.
Step 5: Support your reply with proof
If you disagree, attach evidence. Examples include TDS certificates, bank statements, interest workings, deduction proofs or a corrected deductor statement.
Step 6: Consider a correction route if needed
- Revised return: If you made a genuine omission or error and the time limit permits, a revised return under Section 139(5) may be possible.
- Rectification: If the department's processing contains an apparent mistake, you can request a rectification through the portal.
- Updated return (ITR-U): If the revised-return window has closed, an updated return under Section 139(8A) is available within 48 months from the end of the relevant assessment year. It comes with additional tax of 25% to 70% of tax and interest, depending on when it is filed. It cannot be used to reduce your tax or increase a refund. Use it only after taking professional advice.
Step 7: Pay if the demand is correct
If you agree with a demand, pay through the portal and record the response. Delay can add interest.
Common Mistakes and How to Avoid Them
- Ignoring the notice. Silence means automatic adjustment and a demand you could have contested.
- Replying without checking AIS and 26AS. A wrong response creates a second problem.
- Agreeing with everything by default. Some AIS entries are incorrect. You can give feedback on the entry and provide proof.
- Missing the 30-day window.Calendar the deadline the day you receive the notice.
- Uploading unclear or incomplete documents. A reply without proof is rarely accepted.
- Confusing an intimation with scrutiny. Panicking over a routine adjustment, or underestimating a scrutiny notice, are both costly errors.
- Falling for fake notice emails. Do not share credentials with unverified senders.
- Filing ITR-U in a hurry. The additional tax can be significant. Compare all options first.
How to Avoid Notices in the First Place
- Review your AIS and TIS before filing, not after.
- Reconcile interest, dividend, rent and professional receipts with your return.
- Check TDS credits against Form 26AS and Form 16.
- Report exempt income where required.
- Keep proof of large transactions ready.
- File early, so that you have time for corrections.
Key Takeaways
- Many income tax notice cases are data-matching issues, not accusations.
- Know whether you hold an intimation, a proposed adjustment or a scrutiny notice.
- For Section 143(1)(a), you generally have 30 days to respond through e-Proceedings.
- Always compare the notice with AIS, TIS, Form 26AS and Form 16 before replying.
- Support your reply with documents.
- Revised return, rectification and ITR-U are options, but each has conditions and costs.
- Review AIS before you file to prevent most notices.
Frequently Asked Questions
1. Is an income tax notice always a sign of tax evasion?
No. Many notices are automated and arise from mismatches between your return and the data reported by banks, employers and others.
2. How long do I have to reply to a Section 143(1)(a) notice?
Generally, 30 days from the date of the notice, through the e-Proceedings section of the e-filing portal.
3. What happens if I do not reply?
The return is processed with the proposed adjustments, and a demand may be raised.
4. Can I file a revised return after receiving a notice?
In some cases, yes, if the return is eligible and the time limit permits. Your CA can confirm whether this applies to your return.
5. What is ITR-U and when should I use it?
It is an updated return under Section 139(8A), allowed within 48 months from the end of the relevant assessment year, with additional tax of 25% to 70%. It is a later-stage option, not a first response.
6. How do I know a notice is genuine?
Log in to the official e-filing portal yourself and check your pending actions. Do not rely on links or attachments in unverified emails or messages.








 CAclubindia
