Introduction
Tax planning is an important part of managing personal and family finances. In India, a Hindu Undivided Family (HUF) can be a useful tax-planning structure for eligible Hindu families, including Jain, Sikh, and Buddhist families under the applicable legal framework.
One of the main advantages of an HUF is that it is treated as a separate taxable entity under income tax law. This means eligible income belonging to the HUF may be taxed separately from the personal income of its members.
However, an HUF does not automatically reduce everyone's tax liability. The actual benefit depends on the source of income, ownership of assets, applicable tax regime, available deductions, and compliance with income tax provisions.
In this article, we explain HUF income tax benefits in 2026, the applicable tax slabs, eligible deductions, legal tax-saving strategies, and important precautions to consider before forming an HUF.
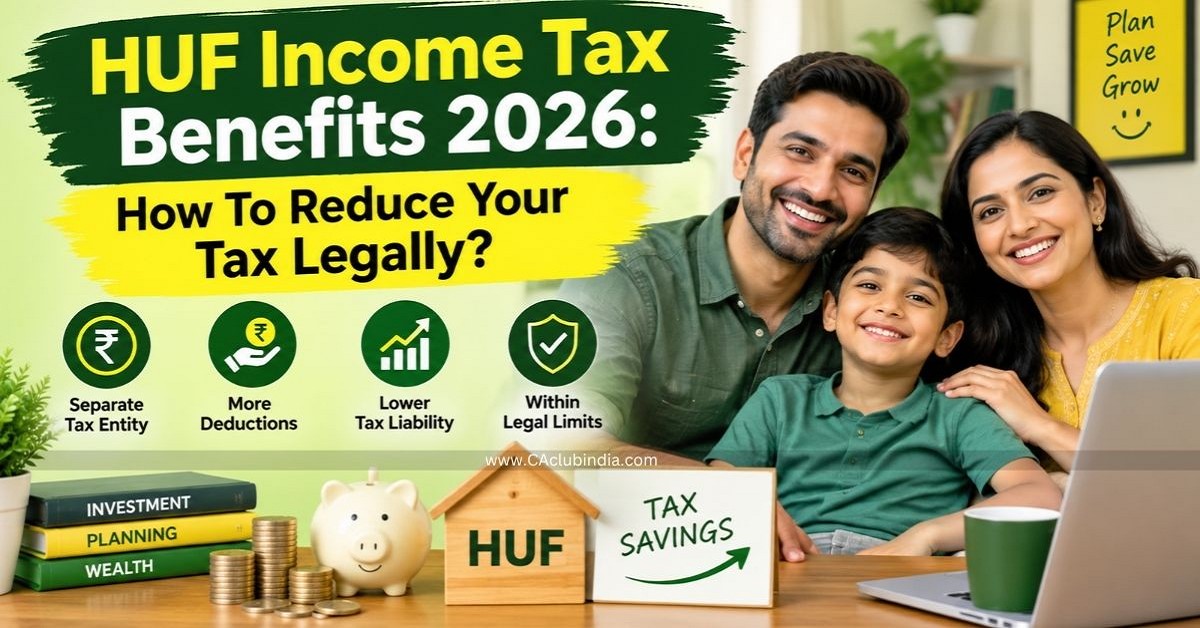
What Is an HUF?
A Hindu Undivided Family, commonly known as an HUF, is a family unit recognised under Indian law. It can consist of family members who hold property or other assets as part of the HUF.
An HUF can own property, maintain a bank account, earn income, and file an income tax return in its own name through its authorised representative, generally the Karta.
For income tax purposes, an HUF is treated separately from its individual members when the income genuinely belongs to the HUF.
For Example
Suppose a family owns ancestral property that legally belongs to the HUF and earns rental income from it. Subject to the applicable legal and tax provisions, this rental income may be assessed in the hands of the HUF rather than being combined with a member's personal salary income.
Key HUF Income Tax Benefits in 2026
1. Separate Income Tax Assessment
The primary benefit of an HUF is its separate tax identity.
An eligible HUF can earn income from sources such as:
- Rental income from HUF-owned property.
- Interest earned on investments belonging to the HUF.
- Capital gains from the sale of HUF-owned assets.
- Business income earned by the HUF, subject to applicable conditions.
Because the HUF is assessed separately, its eligible income is not automatically added to the personal taxable income of the Karta or other members. This may help families organise and manage their tax liabilities more efficiently.
2. Separate Basic Exemption Limit
An HUF is eligible for its own basic exemption limit under the applicable tax regime.
- Under the old tax regime, the general basic exemption limit for an HUF is ₹2.5 lakh. Under the new tax regime applicable from Assessment Year 2026–27, the general nil-rate slab extends to ₹4 lakh.
- This separate exemption is relevant only when the income genuinely belongs to the HUF. It cannot be used to transfer personal salary or other income into the HUF merely to reduce tax.
3. Potential Tax Savings on Family Property
Families holding ancestral or jointly owned property may benefit from appropriate ownership and income-tax planning.
If property belongs to the HUF under applicable law, rental income and eligible capital gains may be taxable in the HUF's hands.
For Example
If an HUF earns ₹6 lakh in annual rental income, the taxable amount must be calculated after considering applicable deductions, such as eligible municipal taxes and the statutory deduction under the house-property provisions.
The final tax liability depends on the nature of the property, the available deductions, and the tax regime selected.
4. Eligible Deductions Under the Old Tax Regime
An HUF may claim certain deductions under the old tax regime if it satisfies the specific conditions prescribed by law.
Depending on the circumstances, these may include:
- Section 80C deductions for eligible investments or payments made by the HUF, subject to the applicable aggregate limit.
- Section 80D deductions for eligible health insurance premiums covering HUF members.
- Section 80DD deductions for qualifying expenditure or deposits relating to a dependent with a disability.
- Other deductions available to HUFs under the relevant provisions of the Income-tax Act.
These deductions are not universally available for every payment made by an individual family member. The person making the payment, the ownership of the funds, and the statutory conditions must be checked carefully.
5. Separate Financial and Investment Records
An HUF can maintain its own bank account, books of account where required, investment records, and tax documents.
Keeping these records separate from the personal finances of family members helps establish the genuine ownership of income and assets.
It also makes tax-return preparation, financial reporting, and future family property management easier.
HUF Income Tax Slabs for 2026
For Assessment Year 2026–27, corresponding to Financial Year 2025–26, the new tax regime is the default regime for HUFs. The HUF may opt for the old regime subject to the applicable rules.
New Tax Regime: HUF Tax Slabs
| Taxable Income | Tax Rate |
| Up to ₹4,00,000 | Nil |
| ₹4,00,001–₹8,00,000 | 5% |
| ₹8,00,001–₹12,00,000 | 10% |
| ₹12,00,001–₹16,00,000 | 15% |
| ₹16,00,001–₹20,00,000 | 20% |
| ₹20,00,001–₹24,00,000 | 25% |
| Above ₹24,00,000 | 30% |
Health and Education Cess, generally 4%, is added to the income tax payable. Surcharge may also apply at higher income levels.
Important: The Section 87A rebate available to eligible resident individuals is not available to an HUF. Therefore, an HUF cannot claim the individual rebate simply because its income is within ₹12 lakh.
Old Tax Regime: HUF Tax Slabs
| Taxable Income | Tax Rate |
| Up to ₹2,50,000 | Nil |
| ₹2,50,001–₹5,00,000 | 5% |
| ₹5,00,001–₹10,00,000 | 20% |
| Above ₹10,00,000 | 30% |
The old regime may be worth evaluating when the HUF has substantial eligible deductions. The new regime may be more suitable when deductions are limited. Always compare the final tax payable under both regimes before making a decision.
Also Read - Income Tax Slab Rate For FY 2025-26 (AY 2026-27)
How to Reduce HUF Income Tax Legally?
1. Identify Genuine HUF Income
The first step is to identify income that legally belongs to the HUF.
Examples may include income from ancestral property belonging to the HUF, eligible gifts received by the HUF, and income from investments purchased using genuine HUF funds.
Personal salary earned by a member cannot simply be treated as HUF income.
2. Maintain a Separate HUF Bank Account
Open a bank account in the HUF's name and use it for genuine HUF transactions.
Maintain records of:
- Initial capital and the source of funds.
- Gifts and inherited assets.
- Investment purchases and sales.
- Rental receipts and property-related expenses.
- Interest income and other receipts.
These documents help establish that the income belongs to the HUF rather than to an individual member.
3. Evaluate Eligible Deductions
Under the old tax regime, check whether the HUF qualifies for deductions such as Section 80C, Section 80D, and Section 80DD.
For instance, an eligible health insurance premium paid from HUF funds may qualify for a deduction under Section 80D, subject to the statutory conditions and limits.
Do not assume that all investments, medical expenses, or insurance premiums paid by family members can be claimed by the HUF.
4. Review Property Ownership Before Transferring Assets
Before transferring property or investments to an HUF, examine the legal ownership, tax consequences, and source of the asset.
Transferring an individual's self-acquired property to an HUF may trigger clubbing provisions under Section 64(2), which can cause income from the transferred property to be included in the transferor's taxable income.
Therefore, transferring personal assets to an HUF does not necessarily create tax savings.
5. Plan Gifts and Inheritances Carefully
An HUF may receive eligible gifts and inheritances, but the tax treatment depends on the donor, relationship, nature of the transfer, and applicable statutory provisions.
Gifts received from specified relatives may qualify for exemption under the relevant provisions. Other gifts may be taxable, subject to applicable exceptions and thresholds.
Maintain gift deeds, inheritance documents, bank statements, and other supporting evidence wherever appropriate.
6. Compare the Old and New Tax Regimes
Calculate the HUF's tax liability under both regimes before choosing the old regime where an option is available.
The old regime may be advantageous when the HUF has sufficient eligible deductions. The new regime may be beneficial when the HUF has fewer deductions and prefers the concessional slab rates.
For HUFs with business or professional income, the rules governing the option to switch regimes require particular attention.
7. File the HUF Income Tax Return Correctly
An HUF should report its actual income, eligible deductions, taxes paid, and other required information accurately.
Select the appropriate income tax return form based on the HUF's sources of income and the eligibility conditions for the relevant assessment year.
Keep supporting documents, reconcile tax credits, and pay advance tax where applicable.
Example: How an HUF May Help With Tax Planning
Suppose a family has ₹6 lakh in annual rental income from property that genuinely belongs to its HUF.
Assume, purely for illustration, that the HUF qualifies for a ₹1.8 lakh deduction under the applicable house-property rules.
The computation would be:
| Particulars | Amount |
| Annual rental income | ₹6,00,000 |
| Illustrative eligible deduction | ₹1,80,000 |
| Taxable house-property income | ₹4,20,000 |
Under the new tax regime for AY 2026–27, assuming no other income or adjustments, the tax on ₹4.2 lakh would be ₹1,000 before cess, because only ₹20,000 falls in the 5% slab.
The tax after 4% cess would be ₹1,040, subject to applicable rounding rules.
This example illustrates how an HUF's separate tax assessment may work. It does not establish that forming an HUF will always reduce a family's total tax. The outcome depends on ownership, the alternative tax treatment, and any tax that would otherwise arise.
How to Create an HUF in India?
The usual steps for establishing and documenting an HUF include:
- Prepare an HUF declaration: Record the HUF's name, Karta, members, and other relevant details.
- Apply for a separate PAN: Submit the required application and supporting documents.
- Open an HUF bank account: Follow the bank's documentation requirements.
- Document the source of funds: Maintain evidence for inherited property, gifts, and other assets belonging to the HUF.
- Maintain separate accounts: Record income, expenditure, investments, and other transactions independently.
- File the income tax return: Report the HUF's taxable income and claim only eligible deductions.
An HUF's legal existence and the ownership of its assets depend on the applicable law and facts. A declaration, PAN, or bank account alone does not make an individual's income or assets HUF property.
Common HUF Tax Planning Mistakes to Avoid
Avoid these common mistakes while using an HUF for tax planning:
- Treating personal salary as HUF income without a valid legal basis.
- Transferring personal assets without checking clubbing provisions.
- Claiming deductions without supporting documents.
- Mixing personal and HUF funds in the same account.
- Assuming that an HUF is automatically tax-free up to ₹12 lakh.
- Failing to compare the old and new tax regimes.
- Ignoring applicable return-filing, advance-tax, and record-keeping requirements.
Incorrect reporting may lead to additional tax, interest, penalties, or other consequences under the applicable law.
Is an HUF Suitable for Every Family?
No. An HUF is not suitable for every taxpayer.
It may be worth evaluating when a family genuinely owns ancestral property, has identifiable HUF assets, or earns income that legally belongs to the HUF. However, families whose income mainly consists of personal salaries and individual investments may receive limited benefits from creating an HUF solely for tax savings.
Consider the legal implications, family arrangements, compliance costs, and long-term ownership consequences before establishing one.
Conclusion
HUF income tax benefits in 2026 can be useful for eligible families that own property or other assets belonging to a Hindu Undivided Family. Separate tax assessment, eligible deductions under the old regime, and structured management of family assets may support effective tax planning.
However, an HUF is not a shortcut for converting personal income into tax-free income. The source and ownership of income, clubbing provisions, applicable tax regime, and documentation must all be considered.
Before creating an HUF or transferring assets, evaluate the potential tax savings against the legal and compliance implications. A properly documented and legally compliant approach is the best way to reduce tax liability.
FAQs
1. Is income earned from ancestral property taxable in an HUF?
Income from ancestral property may be taxable in the HUF's hands when the property legally belongs to the HUF. The ownership structure and applicable legal provisions must be examined before determining the tax treatment.
2. Can an HUF invest in mutual funds and fixed deposits?
Yes. An HUF can generally invest in eligible mutual funds, fixed deposits, and other permitted financial instruments using its own funds.
3. Does transferring personal property to an HUF reduce tax?
Not necessarily. Section 64(2) of the Income-tax Act contains clubbing provisions that may cause income from assets transferred by an individual to an HUF to remain taxable in the individual's hands. Obtain appropriate tax advice before transferring assets.
4. Which tax regime is better for an HUF in 2026?
The new tax regime may be suitable when the HUF has limited deductions. The old regime may be beneficial when substantial eligible deductions are available. Calculate the tax under both regimes before deciding.
5. How can an HUF be created in India?
The usual steps include preparing an HUF declaration, obtaining a separate PAN, opening an HUF bank account, documenting the source of funds and assets, maintaining separate financial records, and filing income tax returns as required.
6. Is an HUF completely tax-free up to ₹12 lakh?
No. The ₹12 lakh Section 87A rebate threshold applies to eligible resident individuals under the relevant conditions, not to HUFs. An HUF's tax liability must be calculated using the applicable HUF tax slabs and provisions.
7. Is creating an HUF beneficial for everyone?
No. An HUF may be useful for families with genuine HUF assets or income, but it may provide limited tax benefits to families whose income mainly consists of personal salaries and individually owned investments.







 CAclubindia
