Every parent wants to give their child a secure financial future, whether it is for higher education, career aspirations or other major milestones. The challenge is deciding where to invest. With options such as PPF, Sukanya Samriddhi Yojana (SSY), mutual funds, ULIPs and a Child Plan , choosing the right mix can feel overwhelming.
The good news is that there is no single "best" option. Each investment serves a different purpose. Understanding how they work can help you build a plan that matches your financial goals and your child's future needs.
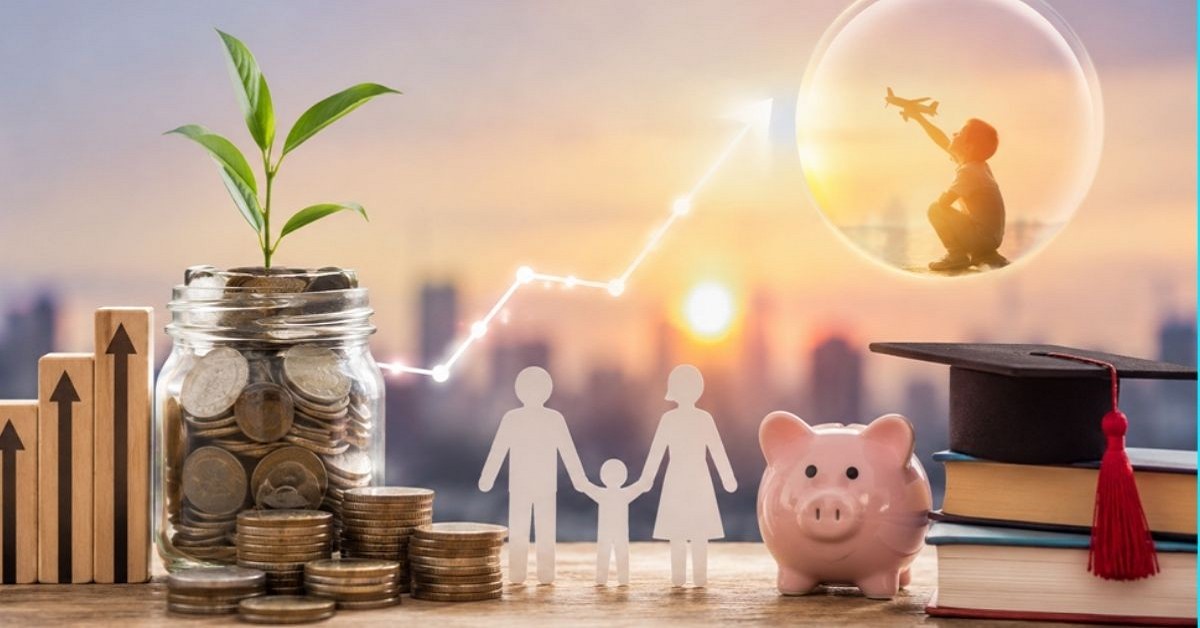
Which investment options can help build your child's future?
Parents today have access to both government-backed savings schemes and market-linked investment products. Some focus on safety, while others aim for long-term wealth creation.
The most common options include:
- Public Provident Fund (PPF) – A government-backed long-term savings scheme with stable returns.
- Sukanya Samriddhi Yojana (SSY) – Designed for a girl child, offering government-backed returns and tax benefits.
- Mutual funds – Market-linked investments can generate higher long-term returns but also carry market risk.
- ULIPs – Combine life insurance with market-linked investing in a single product.
- Child Plan – Insurance-based plans that help build a corpus for your child's future while also providing financial protection.
How does a Child Plan differ from other investment options?
A Child Plan is designed specifically to help parents create a financial corpus for their child's future while also providing life insurance protection.
Unlike investments such as PPF or mutual funds, a Child Plan combines disciplined savings with insurance. If the parent who is the life assured passes away during the policy term, the policy benefits continue according to the policy terms and conditions, helping ensure the child's financial goals remain on track.
If your priority is long-term financial security along with insurance protection, a Child Plan may complement your overall investment strategy.
Which option is suitable for different financial goals?
No single investment option is suitable for every financial goal. The right choice depends on when you need the money, the level of risk you are comfortable taking and whether you are looking for capital protection, long-term growth or insurance along with investments.
The table below provides a quick comparison.
|
Goal |
Suitable option |
|
Safe long-term savings |
PPF |
|
Saving for a girl child's future |
SSY |
|
Long-term wealth creation |
Mutual funds |
|
Investment with insurance |
ULIPs |
|
Child-focused savings with insurance |
Child Plan |
Instead of choosing only one product, many families build a diversified portfolio by combining different options based on their financial goals and risk appetite.
What factors should you compare before investing?
Before choosing an investment for your child, look beyond expected returns. The right option should match your financial goal, investment horizon and comfort with risk while offering the flexibility you may need in the future.
Before selecting an investment for your child, compare these important factors.
- Investment objective – Decide whether you need wealth creation, capital protection, insurance or a combination of these.
- Risk level – Government-backed schemes offer stability, while market-linked products involve investment risk.
- Investment horizon – Match the product with your child's future milestone, such as higher education or marriage.
- Liquidity – Check whether partial withdrawals are allowed before maturity.
- Tax benefits – Understand the tax treatment of investments and maturity proceeds wherever applicable.
- Insurance requirement – Decide whether you also need financial protection along with investments.
Should you rely on just one investment?
Usually, no. Every investment has its own strengths. Government-backed schemes provide stability, while market-linked investments offer higher growth potential over longer periods. Insurance-based solutions help protect financial goals if unforeseen events occur.
Rather than depending on a single product, many financial planners recommend combining investments based on your goals, investment horizon and risk tolerance. A diversified approach can help balance growth, safety and financial protection.
How should you decide what is right for your child?
The right investment depends on your financial situation rather than a universal formula. Consider your child's age, the number of years available before the money is needed, your monthly investment capacity, risk appetite and whether insurance protection is also important. Reviewing these factors regularly allows your investment strategy to evolve as your family's financial responsibilities change.
If you are exploring Child Plan options, you can also compare child life insurance plans offered by leading insurers through Bajaj Finance Insurance Mall to understand how insurance and long-term savings can work together.
Conclusion
Planning early gives your investments more time to grow through the power of compounding. While PPF and SSY offer stability, mutual funds and ULIPs provide market-linked growth potential, and a Child Plan combines long-term savings with financial protection.
Instead of searching for one perfect investment, focus on building a balanced strategy that reflects your financial goals, investment horizon and your child's future needs. Choosing the right combination today can help you create a stronger financial foundation for tomorrow.
You have reached your daily limit of 2 Free Articles
Subscribe to CCI PRO for unlimited access
Why Upgrade to CCI PRO?
- No Ads
- WhatsApp Community
- Daily E-Newsletter
- Unlimited Articles Access
- Profile Visitors
- Link Social Profiles
- Featured Job Posts
- Pro Badge
- Expert GST Guidance
- Unlimited Forum Replies
- Download Content in PDF
Already a PRO member? Login here for an ad-free experience. 07941056694






 CAclubindia
