 Mohd Ashraf

In corporate tax compliance, optimizing Input Tax Credit (ITC) on travel and business expenditure is a high-priority task. Air ticketing, while seemingly straightforward, features some of the most intricate Goods and Services Tax (GST) dynamics. Depending on whether a corporate traveler books directly with an airline, uses an Online Travel Agency (OTA), or relies on a corporate travel operator, the invoicing structures and ITC eligibility criteria shift dramatically.
This comprehensive guide breaks down the core booking channels, details the hidden nuances of Rule 32(3) for travel agents, and provides a scannable compliance matrix to ensure zero leakage of tax credit.
1. Direct Booking via Airline: The Single Principal Model
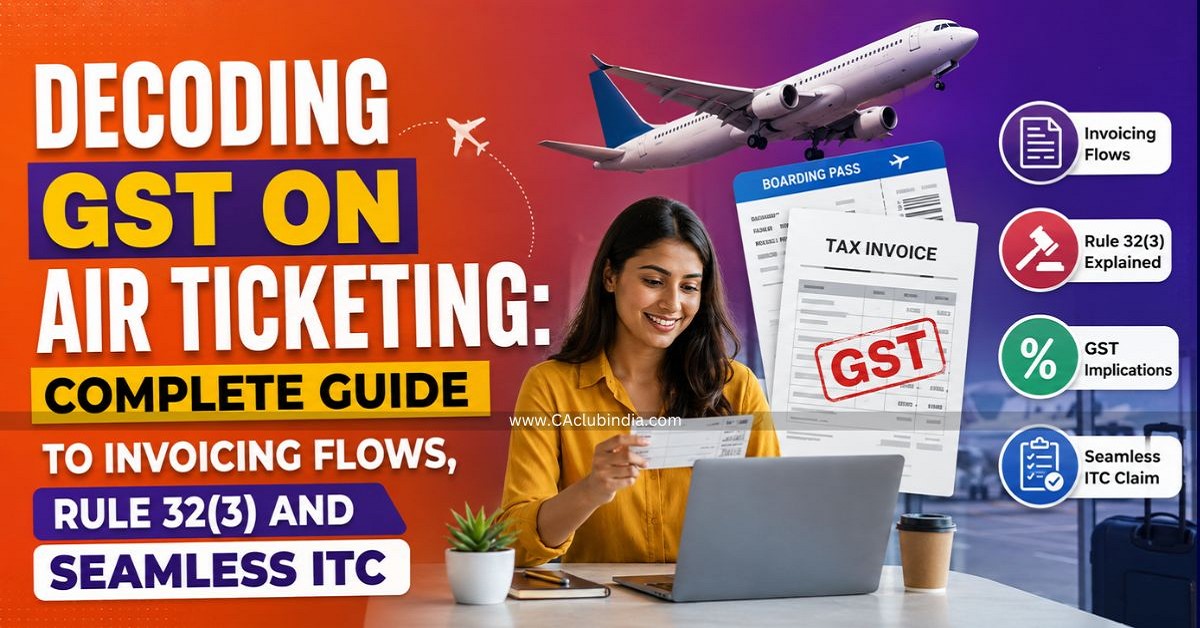
When an enterprise books tickets directly through an airline's official website, portal, or application, the airline operates as the sole principal supplier of service. This represents the cleanest and most direct transaction flow for tax departments.
- Invoicing Flow: The airline generates a single, consolidated tax invoice issued directly to the corporate client.
- ITC Impact: The tax credit appears cleanly under the airline's GSTIN. As long as the company's GSTIN and corporate address are updated at the time of booking, the credit reflects seamlessly in the corporate GSTR-2B , making reconciliation effortless.
2. OTA Portals: The Intermediary Split-Invoice Model
Online Travel Agencies (OTAs) such as MakeMyTrip or Akbar Online act as digital intermediaries. While they display standard airline inventory, they introduce their own operational service charges, leading to a dual-layered invoicing setup.
- Invoicing Flow: The corporate buyer receives a split invoicing structure . The airline issues the main ticket invoice mapping the standard flight tax, while the OTA issues a completely separate invoice for its platform convenience or booking fees.
- Tax on Fee: While the flight component maintains its standard rate based on cabin class, the OTA's convenience fee attracts a flat 18% GST under Service Accounting Code (SAC) 998551.
- ITC Impact: To prevent credit loss, the corporate tax team must track and claim two separate lines of credit in their GSTR-2B: one from the airline for the core transport service, and one from the OTA platform for the facilitation service. Both invoices must explicitly feature the corporate buyer's GSTIN.
3. Third-Party Agents & Corporate Operators: Pure Agent vs. Rule 32(3)
Traditional travel agents and corporate travel management companies deploy distinct commercial frameworks depending on their master service agreements. Understanding these mechanisms is crucial to auditing travel bills.
A. The Pure Agent Model
Under this arrangement, the travel agent acts strictly as an intermediary passing through actual airline costs.
- The agent passes on the exact airline fare and explicitly tacks on a separate line item labeled "Service Charge".
- GST at 18% is levied strictly on that specific service charge.
- ITC Compliance: To claim full ITC on the core flight value, the agent must ensure that the actual airline-generated invoice is mapped directly to the corporate buyer's GSTIN, rather than the agency's internal tax profile.
B. GST on "Basic Faire" Option (Rule 32(3))
When travel agents operate via integrated airline commission networks where margins are embedded within the ticket value, they can opt for a special valuation mechanism under Rule 32(3) of the CGST Rules . Instead of paying tax on actual margins, they pay GST on a fixed, predefined "deemed value":
- Domestic Travel: Value is calculated as 5% of the basic fare.
- International Travel: Value is calculated as 10% of the basic fare.
- The standard 18% GST rate is then applied strictly to this small fraction. For instance, on a domestic ticket, this creates an effective tax rate of approximately 0.9% of the basic fare (5% × 18% = 0.9%).
Comprehensive GST Breakup Matrix for Air Ticketing
|
Booking Channel |
Component Type |
Taxable Base |
Applicable GST Rate |
SAC Code |
ITC Eligibility |
|
Direct Airline |
Ticket Fare (Economy) |
Base Fare + Fuel |
5% |
996425 |
Yes (On Input Services) |
|
Direct Airline |
Ticket Fare (Business) |
Base Fare + Fuel |
18% |
996425 |
Yes (Full Credit) |
|
OTA Portal |
Flight Ticket Component |
Base Fare + Fuel |
5% or 18% (by cabin) |
996425 |
Yes (Via Airline Invoice) |
|
OTA Portal |
Platform / Convenience Fee |
Flat Fee per seat |
18% |
998551 |
Yes (Via OTA Invoice) |
|
Offline Travel Agent |
Flight Ticket Component |
Base Fare + Fuel |
5% or 18% (by cabin) |
996425 |
Yes (If mapped to corporate GSTIN) |
|
Offline Travel Agent |
Booking Service Charge |
Out-of-pocket fee |
18% |
998551 |
Yes (Via Agent Invoice) |
|
Offline Travel Agent |
Commission Value |
Deemed 5% of Basic Fare (Domestic) / 10% (Intl.) |
18% on Deemed Value |
998551 |
Yes (For the corporate buyer) |







 CAclubindia
