Overview
In this special Diwali edition of the Arjuna-Krishna dialogue, understand the key GST changes introduced following the 57th GST Council meeting. Effective from 1st November 2026, the changes cover GST rates on electric vehicle passenger transport, revised definitions of Goods Transport Agency (GTA), reverse charge mechanism (RCM) on specified waste and scrap purchases, TDS obligations under Section 51, restrictions on vehicle detention under Section 129, and the minimum ₹10,000 threshold for issuing GST show cause notices. The article explains these important amendments through familiar Diwali firecracker analogies, helping taxpayers, businesses, transporters and tax professionals understand their new compliance responsibilities.
Arjuna (Fictional Character): Krishna, Diwali is at the doorstep. Homes are lit with diyas, markets are full of sweets, and children are busy bursting firecrackers. But taxpayers are saying that the GST Council has also burst its own firecrackers just before Diwali. What are these new GST firecrackers?
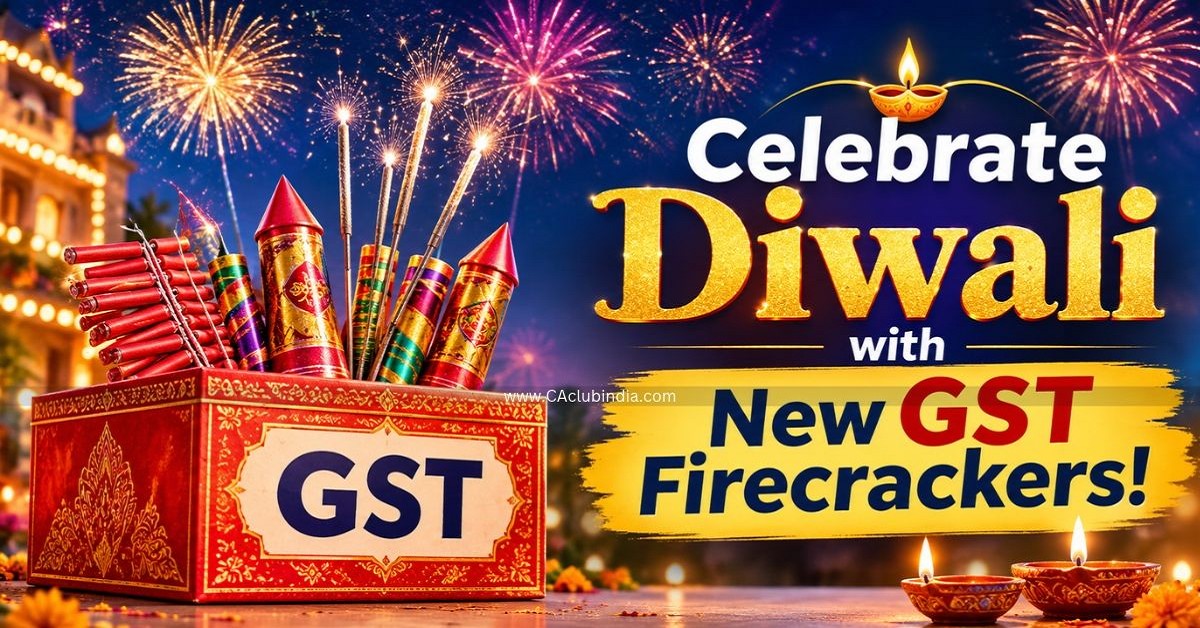
Krishna (Fictional Character): Arjuna, just as every Diwali brings new varieties of crackers into the market, the Government has also lit a fresh set of GST firecrackers this year. On the recommendations of the GST Council in its 57th meeting held on 8th October 2026, the Government issued some of the notifications dated 27th October 2026, effective from 1st November 2026, and CBIC issued Instruction No. 02/2026-GST dated 30th October 2026. Some of these crackers bring relief, and some bring fresh compliance. Let us light them one by one, so that every taxpayer celebrates this Diwali safely.
Arjuna (Fictional Character): Krishna, what about the “Bhuichakri”, the ground spinner that keeps rotating on the ground like a wheel? Is there anything in GST that is moving on wheels this Diwali?
Krishna (Fictional Character): Yes Arjuna! Notification No. 06/2026 has brought transport service by electric vehicles onto the GST road. From 1st November 2026, two new entries have been inserted, transport of passengers by any electrically operated vehicle, and renting of any electrically operated vehicle designed to carry passengers. Both apply where the cost of battery charging is included in the price charged from the customer.
Such operators now get an option. They can charge GST at 5% without taking input tax credit or charge 18% with full input tax credit.
Arjuna (Fictional Character): Krishna, and what about the “ Full Jadi ”, which sparkles quietly in the hand without any noise? Is there a quiet change in GST as well?
Krishna (Fictional Character): Arjuna, the same Notification No. 06/2026 carries a quiet but important change in definitions. First, the definition of “ goods transport agency” excluded an electronic commerce operator by whom, or through whom, services of local delivery are provided. From 1st November 2026, these exclusions have been removed, and GTA now simply means any person who provides service in relation to transport of goods by road and issues a consignment note, by whatever name called. So e-commerce operators doing local delivery also falls under GTA.
Second, a new definition of “electrically operated vehicle” has been inserted. It means a road vehicle which runs solely on electrical energy derived from an external source or from one or more batteries fitted to it, and it specifically includes E-bicycles.
Arjuna (Fictional Character): Krishna, what about the “Garland Crackers”, where one cracker sets off the next in a long chain? Is there a similar chain in GST?
Krishna (Fictional Character): Absolutely Arjuna! Notification No. 04/2026 and Notification No. 07/2026, both effective from 1st November 2026, work like a garland that covers the waste and scrap chain from both ends.
Under Notification No. 04/2026, reverse charge mechanism now applies when a registered person purchases the following goods from an unregistered person: used cooking oil, waste and scrap of plastics, waste and scrap of tyres, and electrical and electronics waste and scrap. The registered buyer must pay the GST under RCM, just as is already being done for metal scrap.
Under Notification No. 07/2026, where the same goods are purchased from a registered supplier, the registered buyer must deduct TDS under section 51 of the CGST Act. So the chain is complete, an unregistered supplier means RCM, and a registered supplier means TDS.
Arjuna (Fictional Character): Krishna, and the "Atom Bomb", the loudest cracker that shakes the entire street? Is there anything in GST with such a big impact?
Krishna (Fictional Character): Yes, Arjuna! Instruction No. 02/2026 is that Atom Bomb. A vehicle can be stopped only on specific intelligence, authorised in writing by an officer not below the rank of Joint Commissioner. The officer can act under section 129 only if the supplier or recipient is in his State or Union territory; otherwise, he must let the vehicle go and only inform the jurisdictional officer.
However, if there is neither an e-way bill nor any document showing the origin or destination of the goods, they can be detained anywhere
Arjuna (Fictional Character): Krishna, and finally the “Lasun Bomb” , small in size but making a sharp sound. Is there any GST change about small amounts?
Krishna (Fictional Character): Yes Arjuna! Many taxpayers have received show cause notices for very small differences, and the cost of replying was often more than the tax itself. Under the same Instruction No. 02/2026-GST, the Council recommended a minimum threshold of Rs. 10,000 for issuing show cause notices under sections 73, 74 and 74A of the CGST Act. Till the amendment comes into force, CBIC has directed that show cause notices may not be issued where the amount involved is below Rs. 10,000, counting CGST, SGST, IGST, UTGST and compensation cess together.
Arjuna (Fictional Character): Krishna, what lesson should taxpayers take from these GST firecrackers?
Krishna (Fictional Character): Arjuna, firecrackers bring joy only when they are burst with care. Similarly, these changes bring relief only to those who understand them and act in time. EV operators must choose their rate option, scrap and waste buyers must set up RCM and TDS compliance from 1st November 2026, and transporters must keep their documents in order even as checks become fewer.
Remember Arjuna, Diwali is a festival of light. When every taxpayer complies with the law on time, it brings light to the business and to the nation. With compliance, it is a true Diwali; without it, the taxpayer risks a Diwali!






 CAclubindia
