Normally, GST requires computation of tax on taxable value - tax being computed as a percentage of the value of supply of goods and services. In most of the cases, the invoice value will be the taxable value.
But in case of a dealer who is engaged in providing service of exchange of foreign exchange, by converting one currency into another currency at the request of the customer and in return charging commission for the same.
Since in foreign exchange conversion transaction value of transaction is very high as compared to the commission charged for converting one currency to another, so, there are 2 methods for valuation of supply of services in relation to the purchase or sale of foreign currency, including money changing.
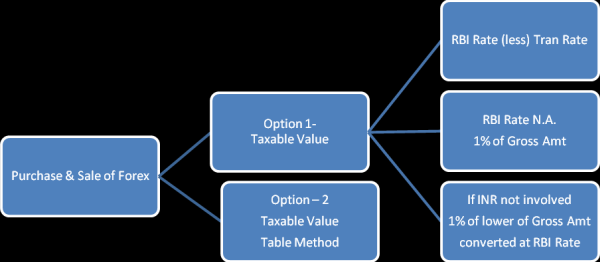
Option 1- Taxable Value
(A) for a currency, when exchanged from, or to, Indian Rupees, the value shall be equal to the difference in the buying rate or the selling rate, as the case may be, and the Reserve Bank of India reference rate for that currency at that time, multiplied by the total units of currency:
(B) Provided that in case where the Reserve Bank of India reference rate for a
currency is not available, the value shall be one per cent. of the gross amount of Indian Rupees provided or received by the person changing the money:
(C) Provided further that in case where neither of the currencies exchanged is Indian Rupees, the value shall be equal to one per cent. of the lesser of the two amounts the person changing the money would have received by converting any of the two currencies into Indian Rupee on that day at the reference rate provided by the Reserve Bank of India.
Case 1: Where one of the value exchanged is Indian Rupees
Eg. On 14th August 2020, Mr. Subhash converted USD 100 into INR 7,600 (INR 76 per USD). RBI's reference rate at the time of exchange was Rs. 75.
Now the value of supply will be: (76-75)*100 = INR 100. GST will be levied on INR 100.
If the RBI reference rate for a currency is not available the value shall be 1% of the gross amount of INR provided or received by the person who is changing the money.
In above example, if the RBI reference rate is not available then 1% of INR 7,600 i.e INR 76 will be the value of supply of service and GST will be levied on INR 76.
Case 2: Where neither of the currencies exchanged is Indian Rupee
Let's assume that USD 1000 is converted into 850 Euro. RBI reference rate at that time for USD is INR 75 per dollar, and INR 88 per POUND. In this case, neither of the currencies exchanged is Indian Rupee.
The value of supply is determined as 1% of the least amount on converting to INR. That is,
1. US Dollar converted into Indian Rupees = 1000$ * Rs 75 = Rs 75,000
2. Euro converted into Indian Rupees = 850 * Rs 88 = Rs 74,800
Value of taxable service = 1% * 74,800 = Rs 748/-
Provided also that a person supplying the services may exercise the option to ascertain the value in terms of clause (b) for a financial year and such option shall not be withdrawn during the remaining part of that financial year.
Option 2-Taxable Value-Table Method
1) Amount of currency Exchanged amount upto 1 Lakh rupees
Taxable Value - 1% of the gross amount minimum Rs. 250
2) Amount of currency exchanged exceeding one lakh rupees and up to ten lakh rupees
Taxable value - Rs. 1,000 and 0.5% of the excess gross amount over one lakh
3) Amount of currency Exchanged Amount of currency Exchanged exceeding ten lakh rupees
Taxable Value - Rs. 5,500 and 0.1% of the excess gross amount over 10 lakhs maximum Rs. 60,000
Eg: Mr. Rohan, has exchanged US $ 5,000 to INR @ Rs 74 per US $
The value of supply based on the second method will be determined as follows:
Value of currency exchanged= Rs 74* $5,000 = Rs 3,70,000
Upto Rs 1,00,000 = Rs 1,000
For Rs 2,70,000 = Rs 1,350 (0.50% * Rs2,70,000)
Value of supply =Rs 2,350








 CAclubindia
