 Shivani
Choosing lower health insurance coverage can reduce the premium, but it can also increase the amount you may need to pay yourself during a claim. The smaller the available sum insured, the sooner it may be used during major or repeated hospitalisation.
This makes it important to look beyond the immediate premium saving and understand how lower coverage can affect your overall out-of-pocket medical expenses during the policy period.
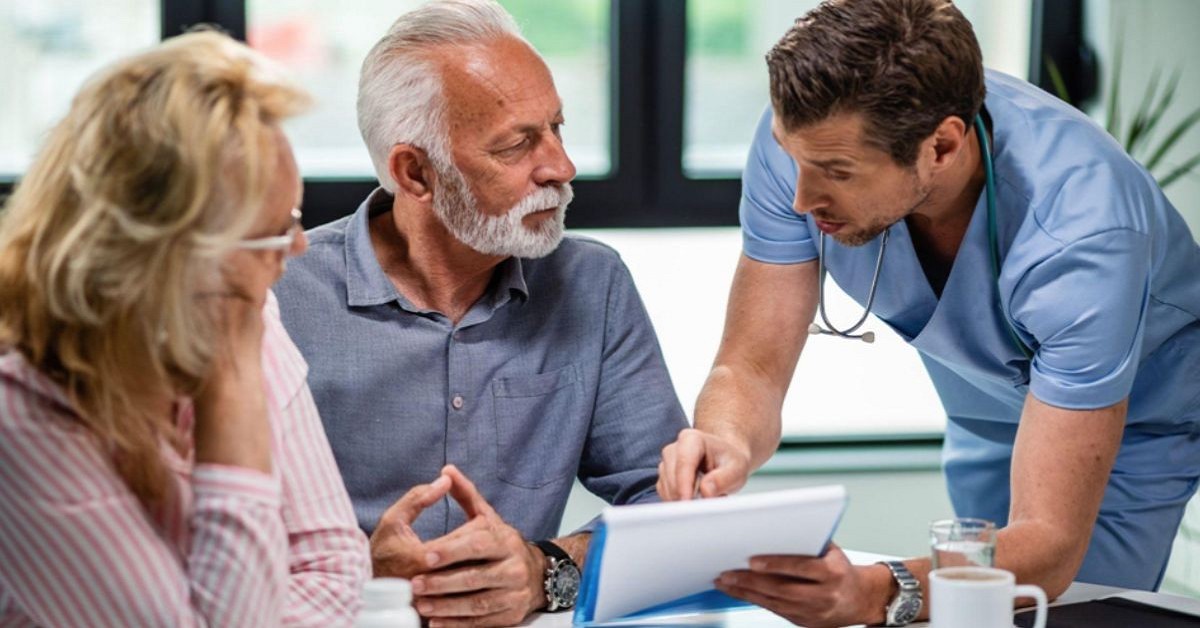
A Large Hospital Bill Can Reach the Limit Faster
With lower coverage, a major hospitalisation can use a larger share of the available sum insured. Surgery, investigations, medicines and specialist care can all form part of the same admission.
If eligible expenses go beyond the remaining cover, the balance may need to come from your own funds. A lower premium can therefore lead to higher personal spending if treatment costs exceed the policy limit.
Repeated Claims Can Leave Less Cover Available
Out-of-pocket risk can rise when more than one claim occurs in the same policy year. After the first admissible claim reduces the sum insured, a later hospitalisation may have a smaller balance available.
This can mean:
- A later claim reaches the remaining limit sooner.
- More of the bill may need personal payment.
- Savings may need to be used for treatment.
Lower Cover Can Put More Pressure on Senior Healthcare Budgets
For older adults, reducing coverage only to save on premiums needs careful thought because healthcare needs may be more frequent or complex. Families considering health insurance for senior citizens above 80 years in India should compare the premium savings with the amount they could realistically pay if the available cover is exhausted.
A smaller sum insured may suit some households, but personal savings, existing cover and healthcare needs should support that choice.
One Member Can Use Shared Family Cover Up
In a family floater, all insured members share the available sum insured. If one person has a substantial hospital claim, a smaller balance may remain for others during the same policy year.
- One major claim can use a large part of the cover.
- Another family member may have less insurance available later.
- Further treatment may require greater personal contribution.
- Lower shared coverage can therefore increase out-of-pocket exposure.
Cost Sharing Can Add to the Burden
A lower sum insured is not the only reason a policyholder may pay personally. Co-payments, deductibles, sub-limits and non-payable items can also affect the final claim amount.
When lower coverage is combined with these conditions, personal spending can rise further. Part of the bill may fall on the insured because of cost sharing, while another part may become payable if the sum insured is exhausted.
Lower Cover for Parents Can Increase Personal Spending
Choosing lower coverage for a health plan for parents may reduce the premium, but it also limits the amount available for eligible medical expenses. This can matter if either parent requires costly or repeated hospitalisation.
- A smaller cover may be exhausted sooner.
- Repeated treatment can put greater pressure on family savings.
- Co-payments or other policy conditions may add to personal expenses.
- The premium saving should therefore be considered alongside the amount the family can manage independently.
Restoration Can Help, but Conditions Matter
Restoration or refill benefits can add cover after the original sum insured has been partly or fully used, depending on the policy wording. This may reduce some pressure created by lower base coverage.
However, the trigger, eligible claims and reuse conditions can differ across policies. Lower base cover should therefore be assessed together with the exact restoration rules.
Premium Savings Should Be Compared with Possible Personal Spending
The trade-off is straightforward. Lower coverage can reduce the premium, but it transfers more financial responsibility to you once medical expenses move beyond the available insurance limit.
Before reducing cover, compare:
- The premium saved
- Emergency funds available
- Number of people sharing the cover
- Possibility of repeated hospitalisation
- Cost sharing conditions
- Restoration provisions
This gives a realistic view of affordability.
Final Thoughts
Premium savings from lower coverage can make a policy easier to maintain, but the savings may increase out-of-pocket risk during larger or repeated claims. A smaller sum insured can be exhausted faster, leave less cover for later treatment and create more pressure in a shared family policy.
The decision should therefore consider the premium reduction and how much medical expense you could comfortably manage yourself if the policy limit is reached.







 CAclubindia

