 Mitali

Quick Summary
194S TDS is applicable on the payment for the transfer of Virtual Digital Assets (which include cryptocurrencies and non-fungible tokens).
Who will be the Deductor and Deductee?
| Deductor | Deductee |
| Any person who is responsible for paying to any resident any sum by way of consideration for the transfer of a virtual digital asset is required to deduct TDS u/s 194S. | Tax required to be deducted if the amount is paid or payable to a resident person if the recipient of the consideration is a non- resident, the tax may be deductible u/s 195. |
Rate of 194S TDS
- 1% TDS on the transfer of crypto assets.
- If no PAN then TDS at 20% as per Section 206AA
- For non-filing of return, TDS at 1% (for specified payer) or 5% (for non-specified payer) as per the Section 206AB.
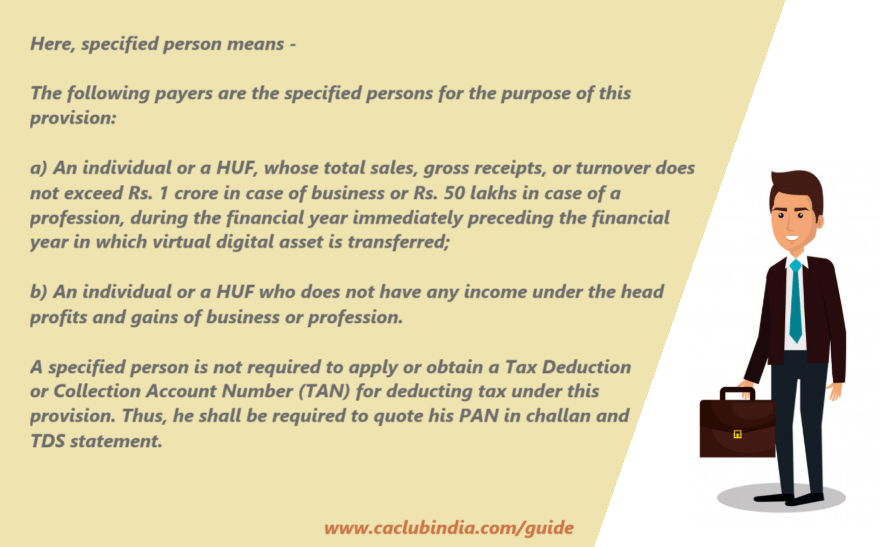
Exemption from 194S TDS
- If consideration is payable by any person (other than specified person) and its aggregate value does not exceed Rs. 10,000 during the financial year.
- If consideration is payable by any person (other than specified person) and its aggregate value does not exceed Rs. 50,000 during the financial year.
How to deposit of TDS?
- Specified Persons is required to deposit TDS via Form 26QE within 30 days of the month's end.
- Others can deposit via Challan ITNS 281 within 7 days of the month's end (March TDS by April 30).
| Category | Filing of TDS Statement | TDS Certificate |
| Specified Persons | File Form 26QE | Issue Form 16E within 15 days of filing Form 26QE. |
| Others | File Form 26Q quarterly | Issue Form 16A within 15 days of filing Form 26Q. |
Consequences on Failure to Deduct/Deposit TDS
Interest
- For non-deduction: 1% per month from due date till deduction.
- For non-deposit: 1.5% per month from deduction date till deposit.
Penalties and Prosecution
- Penalty u/s 271C or 221.
- Prosecution u/s 276B for non-deposit, unless reasonable cause is proven.
Failure to Furnish TDS Statement:
- Fee: Rs.200/day under Section 234E (capped at TDS amount).
- Penalty: Rs.10,000 to Rs.100,000 under Section 271H, or Rs.500/day under Section 272A.
Failure to Issue TDS Certificate:
Penalty applicable to Rs.500/day u/s 272A during default period.
Click Here To Know - Cryptocurrency Taxation in India







 CAclubindia

