 CA Ruby Bansal
Picking a health insurance provider is not just about comparing premiums on a website and calling it a day. You need to look at coverage, claim settlement history, hospital networks, and the fine print that most of us skip past. Get all of that right, and you will land on a provider you will not have second thoughts about later.
Quick Reads
- IRDAI makes every health insurer in India publish its claim settlement ratio each year, and this number is sitting right there on their website if you know where to look.
- A bigger cashless hospital network sounds like a small detail until you are standing at a hospital counter at 2 AM, wondering if you will have to pay out of pocket first.
- Waiting periods for pre-existing conditions are not standard across the board. They can stretch from two years to four, depending on which insurer and plan you go with.
- Room rent sub-limits do not get talked about much, but they can quietly chip away at your payout even when your sum insured looks perfectly healthy on paper.
- The majority of claim rejections happen because of incomplete disclosure at the time of buying, not because the illness itself was excluded.
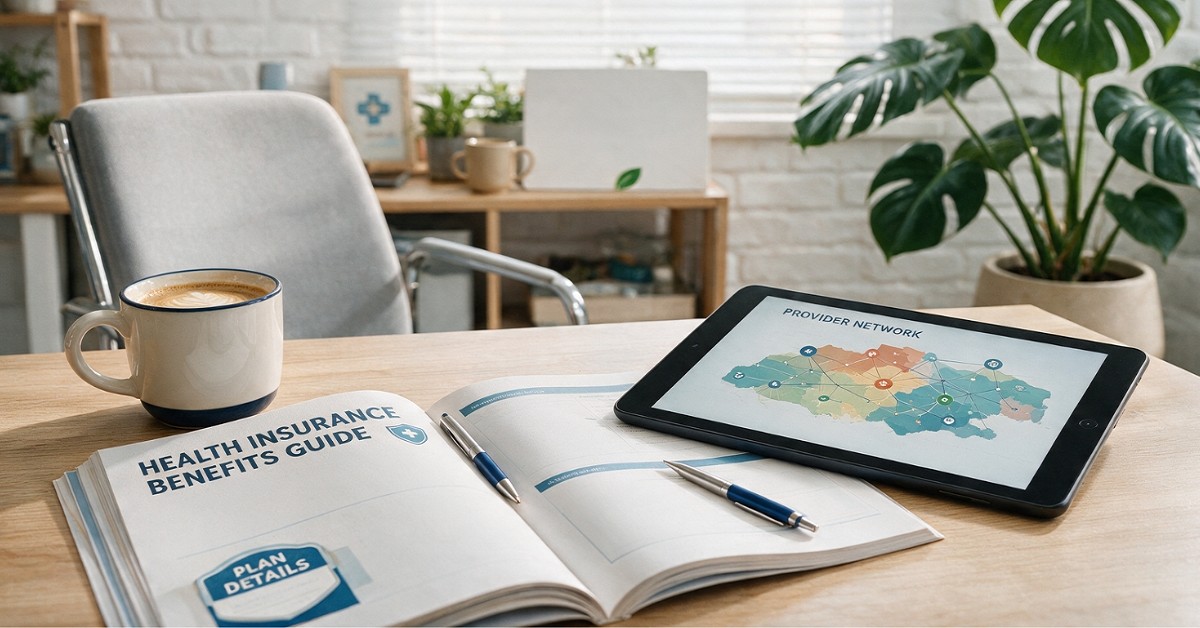
Health insurance providers today offer a wide range of plans, and choosing the right one can feel overwhelming with so many options available. Every provider claims to offer the best coverage, the fastest claims, and the widest hospital network, which makes it difficult to know who to actually trust with something this important. This decision affects how well you and your family are protected during a medical emergency, so it deserves careful thought rather than a quick pick. This blog breaks down exactly what to look for, so you can compare health insurance providers with clarity and choose one that genuinely fits your needs.
What Should You Consider When Choosing a Health Insurance Provider?
The best health insurers in India ticks several boxes at once, from how deep the coverage goes to how easy claims actually are, and once you know what matters, the whole decision gets a lot less overwhelming. Below are the main aspects you should evaluate before making your choice.
Coverage That Matches Your Life Stage
Here's the thing: a 25-year-old fresh out of college and a 55-year-old planning for retirement are not looking for the same policy, and they should not be. Your age, your family size, any existing health conditions, and even plans like starting a family all shape what kind of coverage actually makes sense for you. Just because a plan worked wonders for your colleague does not mean it will do the same for you. Everyone's situation is a little different, and your policy should reflect that.
Premium Versus Value
It is tempting to go with whatever has the lowest premium, but that is often where people end up disappointed later. Instead of only chasing a low number, take a moment to see what you are actually getting in return. Sometimes spending a bit more upfront buys you a much stronger safety net, and trust us, that difference becomes very real the day you actually need to use it.
Add-Ons That Actually Matter
Riders like maternity cover, critical illness benefits, or OPD coverage can sound optional right up until the moment you wish you had them. Take a genuine look at your lifestyle and what your next few years might look like, then choose add-ons that actually apply to your life instead of the ones that just sound impressive in a sales pitch.
How Can You Compare the Coverage Offered by Different Providers?
Comparing coverage is not really about scanning promotional material. It is about lining up the specific details that will decide what you actually get paid during a claim.
Sum Insured and Restoration Benefits
Do not just look at the big sum insured number and call it done. A lot of policies now come with restoration benefits, which basically refill your cover if it runs out within the same policy year. This one feature alone can be the difference between recovering peacefully and scrambling for funds mid-treatment.
Sub-Limits and Co-Payment Clauses
Some policies quietly cap what they will pay for things like room rent or particular treatments, even when your overall sum insured looks generous. Others slip in co-payment clauses that reduce your payout without much fanfare. It genuinely pays off to read through these clauses before you sign anything, because that is where the unpleasant surprises usually hide.
Network Hospitals Near You
Take a minute to check whether the hospitals near your home or office are actually part of the insurer's cashless network. A high sum insured does not mean much if the one good hospital near you is not even on the list, and you end up paying upfront anyway.
What Mistakes Should You Avoid When Choosing a Health Insurance Provider?
A handful of common mistakes end up costing policyholders their peace of mind, and knowing about them ahead of time can help you dodge them entirely.
- Never hide existing health conditions while buying your policy, since non-disclosure remains one of the biggest reasons claims get rejected later on.
- Do not buy a policy just because someone in your family swears by it. What worked for them might not actually fit what you need.
- Do not skip over the exclusions section, because every single plan leaves out certain treatments or conditions, and you deserve to know which ones before you need them.
- Resist the urge to pick a lower sum insured to save a little on premium, since medical costs keep climbing and a smaller cover can fall seriously short during a real emergency.
- Do not let your policy lapse by missing a renewal date, because even a brief gap can undo your accumulated benefits and reset your waiting period progress.
Conclusion
At the end of the day, choosing the right health insurance provider takes a little time and effort, but it saves you from far bigger headaches when it actually matters. Compare coverage properly, dig into claim settlement records, and actually read the fine print instead of ignoring exclusions. And if you are looking for a provider that keeps things transparent and backs it up with solid claim support, Niva Bupa health insurance policy is worth putting on your shortlist as you make your final call.







 CAclubindia
