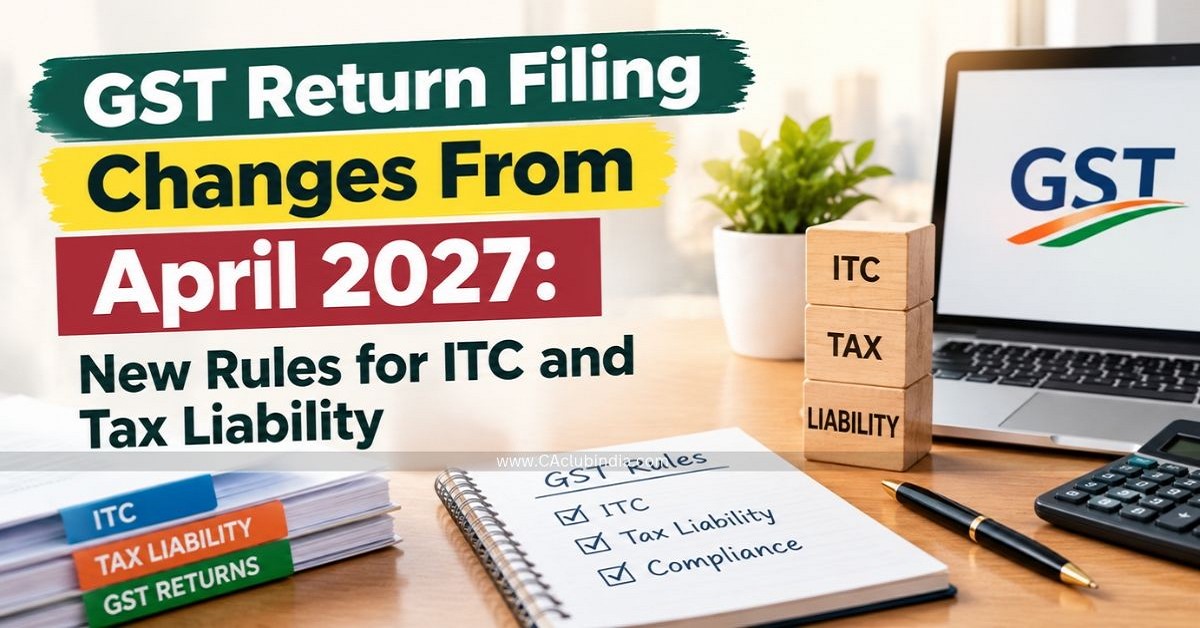
GST return filing process in India is expected to undergo significant changes from April 2027. At its 57th meeting held on 8 October 2026, the GST Council recommended a revised mechanism to improve the accuracy of tax liability reporting and Input Tax Credit (ITC) claims.
The proposed reforms focus on reducing differences between GSTR-1, GSTR-1A, the Invoice Furnishing Facility (IFF), GSTR-3B and GSTR-2B. Additional measures relating to reverse charge transactions, ITC reversals and credit reclaims are also intended to improve reconciliation and reduce system-generated notices.
These changes could make GST compliance more predictable for businesses, accountants and tax professionals. However, taxpayers should note that the recommendations require implementation through the relevant legal amendments, notifications or circulars.
When Will the New GST Return Filing Mechanism Apply?
According to Point A2 of the GST Council press release, the proposed alternative mechanism for correcting tax liability and ITC in GST returns may be brought into force starting with the April 2027 return period. The objective is to help taxpayers identify and correct reporting differences instead of allowing mismatches to result in unnecessary demand notices or system-generated intimations.
The proposed framework includes changes to return forms, new electronic statements and procedures for correcting liability and ITC reporting.
Better Reconciliation Between GSTR-1 and GSTR-3B
One of the major proposed changes is the enhancement of GSTR-1, GSTR-1A and IFF to improve reconciliation with GSTR-3B. GSTR-1 contains details of outward supplies, while GSTR-3B is used to report summary tax liability and eligible ITC. Differences between these filings can create compliance issues.
Under the recommended changes, the return system is expected to provide a better mechanism for identifying and correcting mismatches.
Example: A business reports taxable outward supplies of ₹5 lakh in GSTR-1 but accidentally reports a lower amount in GSTR-3B. The difference may create a mismatch. The proposed correction mechanism is intended to help the taxpayer align the reported liability through the prescribed process. Businesses should continue reconciling their sales registers, GSTR-1 and GSTR-3B before filing returns.
New Electronic Statement for Reverse Charge Mechanism (RCM)
The GST Council has recommended introducing Rule 86D of the CGST Rules to provide an electronic statement of tax paid under the Reverse Charge Mechanism and ITC claimed. Under RCM, the recipient is responsible for paying GST on specified supplies rather than the supplier.
The proposed electronic statement is intended to help taxpayers report RCM liability and related ITC accurately. Businesses making purchases subject to reverse charge should maintain proper records of:
- The nature and value of the underlying supply.
- The applicable reverse charge tax liability.
- GST paid under RCM.
- ITC claimed, where eligible.
- Differences between accounting records and GST returns.
Correct reporting will help reduce reconciliation errors and improve the reliability of GST records.
Mechanism to Correct Tax Liability in GSTR-3B
The Council has recommended inserting sub-rule (1A) in Rule 61 of the CGST Rules to establish a mechanism for correcting tax liability reported in GSTR-3B so that it aligns with liability declared in GSTR-1, GSTR-1A or IFF.
This is important because a mismatch between outward supply details and the summary return may lead to additional compliance work. The proposed mechanism aims to make liability corrections more systematic. Taxpayers will need to follow the procedure prescribed in the applicable rules and notifications once the reform is implemented.
Changes to Form GST DRC-03
Another proposed change concerns Form GST DRC-03, which is used for making certain voluntary payments of tax, interest, penalty and other amounts. The Council has recommended amending the form to capture details of the underlying invoice against which payment is made.
This additional information is expected to improve traceability and help tax authorities connect a payment with the relevant transaction. Businesses and tax professionals should maintain invoice-level documentation when making payments through DRC-03.
Invoice Management System (IMS) and GSTR-2B
The proposed reforms also cover the Invoice Management System. The Council has recommended a provision under Rule 60 to allow recipients, subject to specified conditions, to accept, reject or keep pending documents relating to inward supplies on the GST portal for generating the GSTR-2B ITC statement.
How could IMS help taxpayers?
- Accept: Confirm the document for the applicable ITC reporting process.
- Reject: Mark an incorrect or inappropriate document for the prescribed treatment.
- Keep pending: Defer action on a document where further verification is required, subject to the applicable conditions.
The press release specifically mentions conditions relating to the period for which a credit note may be kept pending. Taxpayers should follow the detailed rules once notified. A disciplined invoice review process can help reduce errors in purchase reconciliation and ITC claims.
New Electronic Credit Reversal and Reclaim Statement
The GST Council has recommended introducing Rule 86C to establish an Electronic Credit Reversal and Reclaim Statement on the GST portal. This statement is intended to help taxpayers report ITC reversed and subsequently reclaimed in GSTR-3B correctly.
For example, where ITC is reversed and later becomes eligible for reclaim under the applicable provisions, the taxpayer needs to maintain records that clearly connect the original reversal with the subsequent reclaim. The proposed statement is expected to make this tracking process more transparent and reduce errors in reporting. Businesses should reconcile their ITC ledgers, reversal records and reclaim entries regularly.
Correcting ITC Differences Between GSTR-3B and GSTR-2B
The Council has also recommended inserting sub-rule (1B) in Rule 61 to provide a mechanism for correcting ITC reporting in GSTR-3B so that it aligns with the ITC made available in GSTR-2B.
Taxpayers should verify purchase invoices and supplier details, ITC reflected in GSTR-2B, eligibility of the credit under GST law, ITC already claimed in GSTR-3B, reversals and subsequent reclaims, and differences arising from amendments, credit notes or missing invoices.
The proposed mechanism does not mean that every credit appearing in GSTR-2B automatically becomes eligible. The applicable statutory conditions and restrictions will continue to matter.
How Will the Proposed Changes Benefit Businesses?
- Reduced mismatch notices: Better alignment between return forms could reduce demand notices and system-generated intimations arising from reporting differences.
- Improved ITC tracking: Electronic statements for RCM and ITC reversal and reclaim should make transaction-level tracking easier.
- Better invoice reconciliation: IMS functionality can help recipients review supplier documents more systematically.
- Greater reporting accuracy: A defined correction mechanism could help businesses rectify discrepancies in liability and ITC reporting.
- Lower compliance burden: Fewer avoidable mismatches may reduce time spent on explanations, reconciliations and responding to notices.
These benefits will depend on the final rules, portal functionality and correct adoption by taxpayers.
How Should Businesses Prepare for April 2027?
- Reconcile GSTR-1, GSTR-1A, IFF and GSTR-3B for every applicable tax period.
- Compare purchase registers with GSTR-2B before claiming ITC.
- Maintain separate records for RCM liability, tax payment and eligible ITC.
- Track ITC reversals and reclaims with supporting documents.
- Review the IMS workflow and establish responsibility for accepting, rejecting or keeping invoices pending.
- Record invoice-level details for payments made through DRC-03.
- Monitor official GST notifications, circulars and amendments before changing filing procedures.
Tax professionals should also review their clients’ accounting systems and reconciliation checklists to ensure they can adapt to the revised mechanism.
Conclusion
The proposed GST return filing reforms from April 2027 aim to make tax liability reporting and ITC reconciliation more accurate and transparent. The focus is on better integration between GST returns, improved invoice management and structured correction mechanisms. Businesses should use this transition period to strengthen their accounting controls and prepare for the revised procedures. The final implementation details should be confirmed through official GST notifications and circulars.
Source: Ministry of Finance, Press Information Bureau, Recommendations of the 57th Meeting of the GST Council, dated 8 October 2026, Point A2 – Return-Related Reforms, pages 5–6.
Frequently Asked Questions (FAQs)
What are the major GST return filing changes proposed from April 2027?
The proposed changes include improved reconciliation between GSTR-1, GSTR-1A, IFF and GSTR-3B; electronic statements for RCM and ITC reversals and reclaims; and mechanisms to correct liability and ITC reporting differences.
Will the new GST return rules apply from April 2027?
The GST Council has recommended that the alternative mechanism for amending liability and ITC in GST returns be brought into force from the April 2027 return period. Final implementation depends on the relevant legal instruments.
What is the proposed change in GSTR-3B?
The Council has recommended procedures for correcting tax liability and ITC reporting so that GSTR-3B aligns with the corresponding outward supply details and ITC made available in GSTR-2B.
What is the Electronic Credit Reversal and Reclaim Statement?
It is a proposed GST portal facility under Rule 86C to help taxpayers track and correctly report ITC reversals and subsequent reclaims in GSTR-3B.
What is the proposed electronic RCM statement?
The recommended Rule 86D facility is intended to record tax paid under reverse charge and ITC claimed, helping taxpayers report the related liability and credit correctly.
Will the proposed changes eliminate all GST notices?
No. The objective is to reduce notices and system-generated intimations arising from mismatches. Notices may still arise where there are genuine tax discrepancies, ineligible ITC claims or other non-compliance.
Will ITC automatically become eligible if it appears in GSTR-2B?
No. The taxpayer must still satisfy the applicable conditions for claiming ITC under GST law.
What should businesses do before April 2027?
Businesses should improve return reconciliation, maintain invoice-level records, track RCM and ITC adjustments and follow the final notifications and portal instructions.







 CAclubindia
