Let's continue with our series on the outlook of the Capital Goods (CG) sector. Here we examine the valuations of the BSE CG Index using the popular valuation metric - PE multiple.
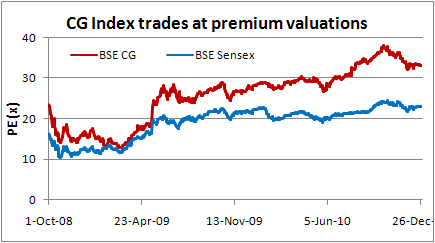
We reiterate that the BSE CG Index underperformed the Sensex in 2010. However, the interesting part is that despite the underperformance, it has remained relatively expensive. In fact, in terms of PE multiple, the BSE CG Index is more expensive than what it was at the start of the year. Today, the BSE CG Index is trading at a PE multiple of 33 as compared to its year ago level of 28. On the other hand, the Sensex is trading at a PE multiple of 23 marginally higher than the year ago PE of 22 times.
Reason behind this is that the denominator i.e. the EPS (Earnings per share) has remained flat on a YoY basis for the 9 month period from Jan-Sept 2010. However, prices have shot up. This has resulted in the PE multiple of CG Index to rise substantially. In comparison, the EPS for the Sensex companies grew by nearly 13% YoY for the same period.
Within the sector, the individual companies presented quite a volatile picture. In fact, 11 out of the 19 companies that form the index witnessed a steep decline in the bottom line.
ABB and Bharat Electronics saw substantial erosion in their profitability during 2010. The decline in EPS for them was a whopping 77% and 55% respectively. In case of Suzlon, the loss doubled for the period Jan-Sep 2010 as compared to corresponding period in the previous fiscal.
ABB was hit because of the declining revenues and profits from its power and process automation business. For the nine months ended Sept 2010, ABB's power systems division witnessed negative operatiing margins while the power products and process automation saw subdued profitability. The decline in profits was compounded by the foreclosure cost in rural electrification business and cost overruns in few large projects.
Bharat Electronics on the other hand continued to see significant contraction in margins. During Jan-Sept 2010, its net profit margins fell to single-digits. The margins have been contracting over the past 3 years from 20% in FY08 to 14% in FY10. These numbers clearly depict the declining trend in its profitability.
Suzlon's case has not been any better. We have extensively discussed it in our previous article. But there is a silver lining in all of this. These companies have a burgeoning order book which provides a good revenue visibility for the time to come. Even Suzlon has shown signs of growth with an order inflow of 400 MW during Q2FY11 and an order backlog of 693 MW from the India business as on Sept 30, 2010. At the end of Q2FY11, the group order book of Suzlon was at $5.4 bn as compared to $4.9 bn at the end of Q1FY11.
Going forward
The infrastructure sector looks promising. The planning commission has a budget of $1 trillion investment in infrastructure for the 12th five year plan (2012-2017). This is nearly twice the target of the 11th five year plan. Of this, the total investment in power sector will be around $300 bn. Again nearly double of the budgeted investment of $147.8 bn during the 11th five year plan.
Given that most of the capital goods companies cater to the power sector we feel the fortunes of the companies should witness a turnaround. However, they need to pull up their socks and take care of their execution issues. In addition to this maybe a few sob stories would continue as some businesses reel under severe cash crunch.
If these issues are resolved, it won't be surprising to see the capital goods companies amongst leading the market performers in times to come.
You have reached your daily limit of 2 Free Articles
Subscribe to CCI PRO for unlimited access
Why Upgrade to CCI PRO?
- No Ads
- WhatsApp Community
- Daily E-Newsletter
- Unlimited Articles Access
- Profile Visitors
- Link Social Profiles
- Featured Job Posts
- Pro Badge
- Expert GST Guidance
- Unlimited Forum Replies
- Download Content in PDF
Already a PRO member? Login here for an ad-free experience. 07941056694









 CAclubindia
