Dear Students / Readers,
Those who do not love to read much, can listen me on youtube, the link of which is given at the end of article.
Statutory definition of term "Income"
You all are aware of the definition of term "Income". The term "Income" has been defined under section 2(24) of the Act. This definition begins with the wordings "Income includes" and provides a huge list of various incomes. Therefore, it is an inclusive definition and not an exhaustive one. Such a definition does not confine the scope of income but leaves room for more inclusions within the ambit of term "Income".
Whether Capital Receipts would fall within the meaning of "Income"?
In common parlance, the word 'Income' covers receipts which arise with certain regularity from a definite source. Therefore, the question may arise whether the Capital Receipts which are not of recurring nature and more particularly of exceptional nature would fall within the meaning of Income?
Judicial Precedent
Hon'ble Bombay High Court had an occasion to deal with issue relating to taxability of "Capital Receipts" in case of Cadell Weaving Mill Co. (P) Ltd. Vs. Commissioner of Income Tax 116 Taxman 77wherein Court has observed as under:
"It is well settled that capital receipts do not come within the ambit of the Income Tax Act except to the extent of any capital receipt being expressly sought to be covered by the Act of the Parliament".
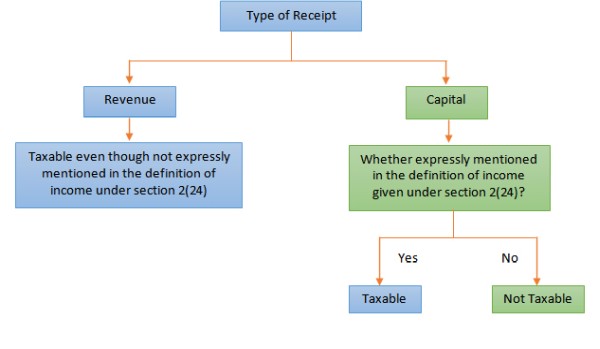
Therefore, the conclusion is that only those capital receipts would fall within the meaning of "Income" which are expressly mentioned under section 2(24) of the Act.
Capital Receipts specifically included under section 2(24)
At present, following capital receipts have been specifically included in the definition of "Income":
(a) Income by way of capital gains [Section 45]
(b) Any sum received under a Keyman insurance policy including the sum allocated by way of bonus on such policy will constitute income.
(c) Compensation on termination of employment or modification of terms of employment.
(d) Compensation or other payment due to or received by some specified person covered under section 28(ii) of the Act
(e) Any sum whether received or receivable in cash or in kind under an agreement for not carrying out any activity in relation to a business or not sharing any know-how, patent, copyright, trade mark, license, etc. [Section 28(va)]
(f) Any consideration received for issue of shares as exceeds the fair market value of the shares [section 56(2)(viib)].
(g) Any sum of money received as advance, if such sum is forfeited consequent to failure of negotiation for transfer of a capital asset [section 56(2)(ix)].
(h) Any sum of money or value of property received without consideration or for inadequate consideration by any person [section 56(2)(x)].
To Sum up,
Taxability of Revenue and Capital Receipt
Test your Knowledge
Discuss Taxability of the followings in the hands of recipients.
(a) Capital contribution received by a partnership firm
(b) Consideration received by a company for issue of shares
Do leave your replies in a "Comment Box".
All the best.
You have reached your daily limit of 2 Free Articles
Subscribe to CCI PRO for unlimited access
Why Upgrade to CCI PRO?
- No Ads
- WhatsApp Community
- Daily E-Newsletter
- Unlimited Articles Access
- Profile Visitors
- Link Social Profiles
- Featured Job Posts
- Pro Badge
- Expert GST Guidance
- Unlimited Forum Replies
- Download Content in PDF
Already a PRO member? Login here for an ad-free experience. 07941056694







 CAclubindia
