1. What is Reverse Charge?
Normally, the supplier of goods or services pays the tax on supply. In the case of Reverse Charge, the receiver becomes liable to pay the tax, i.e., the chargeability gets reversed
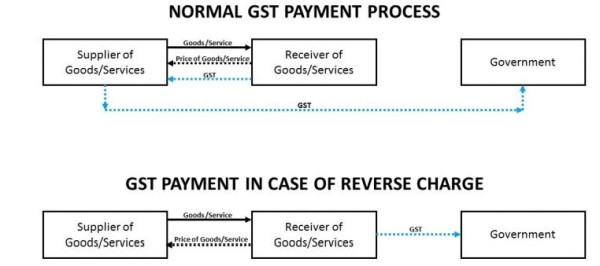
2. When is Reverse Charge Applicable?
2.1. Supply from an Unregistered dealer to a Registered dealer
An unregistered dealer cannot make interstate supplies. This means that Reverse Charge in this case will apply only in case of intra-state supply by an unregistered dealer. Only if the total supply from unregistered person exceeds Rs 5,000 in a day, then reverse charge will be applicable (Notification No.8/2017-Central Tax)
2.2. Supply of Specific Goods or Services
2.2.1. Services through an e-commerce operator
If an e-commerce operator supplies services then reverse charge will be applicable to the e-commerce operator. He will be liable to pay GST.
For example, UrbanClap provides services of plumbers, electricians, teachers, beauticians etc. UrbanClap is liable to pay GST and collect it from the customers instead of the registered service providers.
If the e-commerce operator does not have a physical presence in the taxable territory, then a person representing such electronic commerce operator for any purpose will be liable to pay tax. If there is no representative, the operator will appoint a representative who will be held liable to pay GST.
2.2.2. Supply of certain goods and services specified by CBEC
CBEC has issued a list of goods and a list of services on which reverse charge is applicable
3. Characteristics Of Reverse Charge
3.1 What happens if the receiver of goods and/or services is required to pay tax under Reverse Charge but is not a registered dealer?
All persons who are required to pay tax under reverse charge have to register for GST irrespective of the threshold.
Threshold: Turnover in a financial year exceeds Rs 20 lakhs (Rs 10 lakhs for North eastern and hill states)
3.2 Is Input Tax Credit allowed under Reverse Charge?
Tax paid on reverse charge basis will be available for input tax credit if such goods and/or services are used, or will be used, for business. The recipient (i.e., who pays reverse tax) can avail input tax credit.
3.3. How to determine Time of Supply under Reverse Charge?
Time Of Supply in case of Goods
In case of reverse charge, the time of supply shall be the earliest of the following dates:
(a) the date of receipt of goods OR
(b) the date of payment* OR
(c) the date immediately after THIRTY days from the date of issue of invoice by the supplier
If it is not possible to determine the time of supply under (a), (b) or (c), the time of supply shall be the date of entry in the books of account of the recipient.
Time Of Supply in case of Services
In case of reverse charge, the time of supply shall be the earliest of the following dates:
(1) The date of payment** OR
(2) The date immediately after SIXTY days from the date of issue of invoice by the supplier
If it is not possible to determine the time of supply under (1) or (2), the time of supply shall be the date of entry in the books of account of the recipient.
3.4. Details to be mentioned in the Tax Invoice by the Supplier
The supplier must mention in his tax invoice if the tax is payable on reverse charge
GSTN NUMBER
INVOICE NUMBER, INVOICE DATE
SEGREGATION OF GST(IGST, CGST, SGST)








 CAclubindia