What are the Income Tax slab rates for AY 2020-21?


Quick Summary
For Assessment Year 2020-21, resident individuals with a total income under Rs 5 Lakhs are eligible for a full tax rebate under Section 87A, meaning no tax is payable. For incomes above this threshold, specific tax rates apply, with provisions for marginal relief. It's important to note that opting for lower tax rates may require foregoing certain deductions and exemptions, such as those related to SEZ units, additional depreciation, or specific business expenditures.

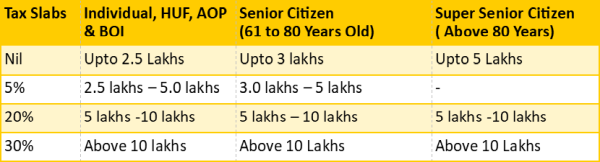
Is the Total Income (Income after deductions) of resident INDIVIDUAL less than Rs 5 Lakhs?

If YES, No Tax Payable for Resident Individual. Eligible for full tax rebate u/s 87A. And if No, Then tax rates are as follows-
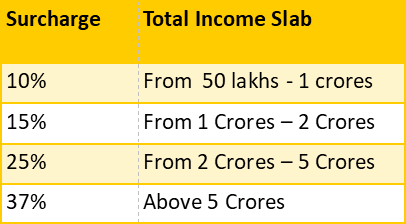
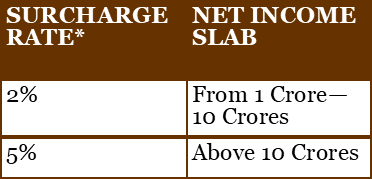
  • The Surcharge shall be subject to Marginal Relief
  • Higher Rate of Surcharge i.e. 25% & 37% shall not apply on capital gains arising on sale of equity share in a company or a unit of an equity oriented fund or a unit of a business trust liable for securities transaction tax

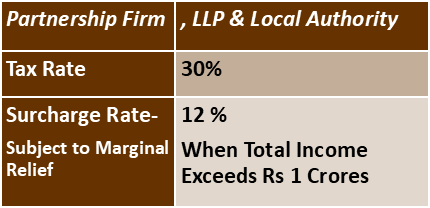
Partnership Firm & LLP & Local Authority 
Domestic Company
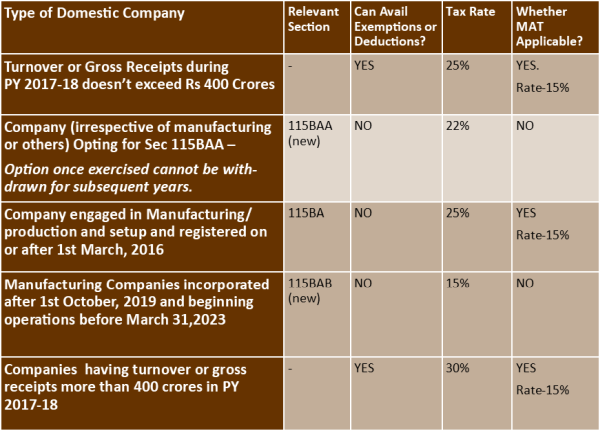
Exemptions or Deductions that need to be foregone for claiming lower rate of tax-
AY 2020-21 Income Tax Slabs and Rates

• 10AA [SEZ units],

• 32(1)(iia) [additional depreciation qua new plant and machinery @ 20%/ 30%],

• 32AD [15% on new assets in undertaking set up in specified backward areas in Andhra Pradesh, Bihar, Telangana, and West Bengal]

• 33AB [specified percentage of amounts deposited with Tea/ Coffee/ Rubber Board]

• 33ABA [specified percentage of amounts deposited in Site Restoration Account]

• 35(1)(ii)/(iia), 35(2AA) or 35(2AB) [specified deduction for scientific research]

• 35AD [expenditure on specified business]

• 35CCC [expenditure on agricultural extension project]

• 35CCD [expenditure on skill development project]

• Part C of Chapter VIA except section 80JJAA or 80LA or 80M of the Act (such as 80IA/IB/IC/ID/IE etc.)

• set-off of any brought forward losses to the extent such loss relates to deductions mentioned above. Such losses would also not be allowed to be carried forward to subsequent years.
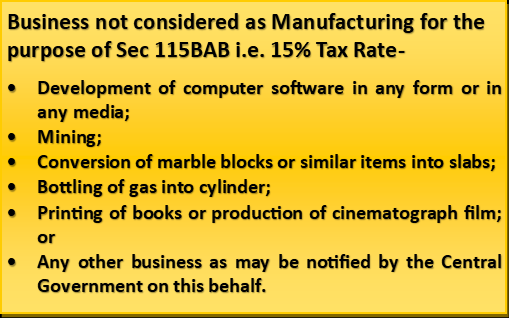
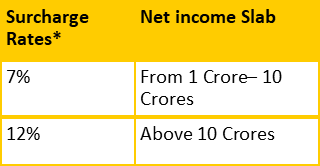


* subjected to Marginal Relief

Foreign Company 
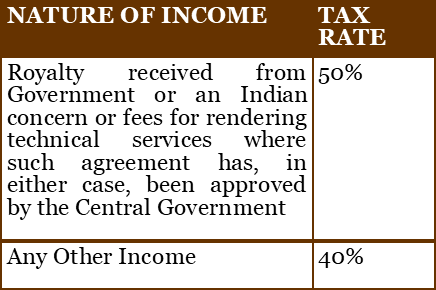

&
*Subject to Marginal Relief


About the Author

Chartered Accountant

Experience Chartered Accountant with a wide exposure in the field of accounting, company law,finance and other allied domains. I also like to venture into research. Blessed with a questioning mind, I am also passionate about writing and communicating about the dynamic changes in law of our country

Comments :

Related Articles


Loading


Popular Articles


CCI Pro

CCI Articles

submit article


Company
26 September 2026
Chartered Accountant

pushpganga ventures

Pune

CA

View Details
Company
12 October 2026
AUDIT , ACCOUNTS AND TAXATION

KDSS

New Delhi

B.Com

View Details
Company
08 October 2026
Accounts and Tax Associate

POOJA R TELI & CO

Pune

CA Inter

View Details
Company
ARTICLESHIP 28 September 2026
Junior Accountant

J S P M & Associates LLP

Pune

B.Com

View Details
Company
05 October 2026
Senior Accountant

Vision IT Peripherals Pvt Ltd

Mumbai

B.Com

View Details
Company
ARTICLESHIP 23 October 2026
CA Articleship / Article Assistant

M N Rao & Associates LLP

Vijayawada

CA Inter

View Details
Company
06 October 2026
Assistant Manager - Audit and Compliance

Ravi K Jain & Co

Noida

Others

View Details
Company
ARTICLESHIP 17 October 2026
Articled Assistant

RRPM & Associates LLP

Chennai

CA Inter

View Details