GST Taxability on Buy 1 Get 1 Free, Gifts & Free Samples
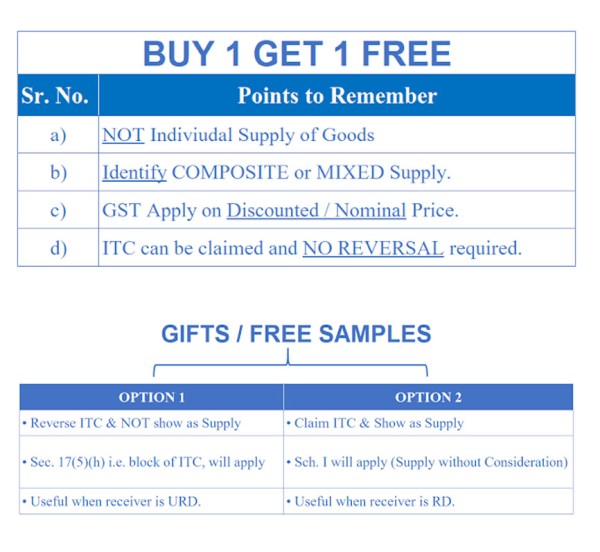
A) GST Taxability on Buy 1 Get 1 Free goods.
- The supply should NOT be considered as
=> 1 Item for consideration and
=> Another for free.
- It is NOT individual supply of Free Goods.
- It should be considered as Single Price for Entire Supply.
- Taxability depends on whether it is: -
=> Composite Supply (i.e. Naturally Bundled), or
=> Mixed Supply (i.e. Not Naturally Bundled)
- If it is Composite Supply then GST Rate of Principal Goods will apply to whole supply.
=> Eg. Mobile Rate is 18% then 18% will also apply on Mobile Charger too.
- If it is Mixed Supply then Highest Rate among all goods/services will apply to whole supply.
=> Eg. Toothbrush (18%) given along with packet of Tea (5%), higher rate i.e. 18% GST will apply on whole supply.
- What if Goods sold at: -
=> Discounted Price (Eg. Rs.200 off on Purchase of Rs.1,000/-) or at
=> Nominal Price (Eg. Buy a Mobile and you'll get Powerbank at Nominal Price of Rs.100)
- The GST will apply on Discounted or Nominal Price as the case may be.
- Input Tax Credit can be claimed on all type of transactions and no reversal of ITC required on Free, Discounted or Nominal Price goods.
B) GST Taxability on Gifts & Free Samples.
There are 2 Options in this case: -
OPTION 1: Reverse the ITC and Not show transaction as Supply.
As we are not showing it as supply, there will be no implication of GST (i.e. GST will not be charged)
Further, Sec 17(5)(h) states, the ITC claimed will be blocked and reversed, if Goods are: -
- Lost,
- Stolen,
- Destroyed,
- Written Off,
- Disposed off by way of Gift or Free Samples,
Thus we need to also reverse the ITC already claimed on goods given as gifts or free samples.
This will be beneficial if the receiver is Unregistered Dealer (as he cannot avail ITC if shown as supply by supplier)
OPTION 2: Claim the ITC and Show transaction as Supply.
- Sch. I cover activities that are to be treated as supply even if made without consideration.
- It states that "Permanent transfer of Business Assets where ITC has been availed on such assets"
- Incase of Gifts and Free Sample there is permanent transfer of business asset (i.e. Stock) and on which ITC availed
- Therefore, if we want to avail ITC, it will be considered as Supply under Sch. I.
- Thus, GST will be applicable on value defined as per valuation rules, even though supply made without consideration.
- This will be beneficial if the receiver is Registered Dealer under GST (as he can avail ITC if shown as supply by supplier)
Alternate View:
- Incase where gifts are provided because of fulfillment of Contractual Obligation of specified purchase, then it should not be considered as Supply without Consideration.
- Eg.: Suppose there is scheme introduced by Company, if the distributer sells goods worth Rs.1 Crores then he'll get a TV as gift.
- In above example we can say that the cost of TV is already included in the Sale consideration (i.e. Rs.1 Crore) received by Company.
- Hence, it is in continuation of earlier obligation, hence not supply without consideration.
CONCLUSION:
DISCLAIMER: - The above details are gathered from GST Act and also with help from various articles and blogs. I have tried my best to compile all the required data in simple and bullet wise format.
The views given above are of author's as per his interpretation.
The author can also be reached at capratikp@gmail.com








 CAclubindia
