Overview
The Supreme Court's judgment in State of Bihar vs. Phulpari Kumari (2 November 2026) has clarified an important misconception about gold jewellery held by married women. The commonly believed 500-gram gold limit under CBDT Instruction No. 1916 is only a guideline for non-seizure during income tax searches and does not automatically establish the legitimate source of the jewellery. The Court held that taxpayers must still explain how the gold was acquired, even when the quantity falls within the prescribed limit. The article explains the legal position on gold received through marriage, gifts and inheritance, tax implications under Section 56(2)(x), capital gains on jewellery sales, and the importance of maintaining purchase invoices, gift records and inheritance documents. It also highlights the Schedule AL disclosure requirement for taxpayers with income exceeding ₹50 lakh.
Arjuna (Fictional Character): Krishna, in every Indian home, gold is a mother’s blessing, a bride’s pride and the family’s security. And every taxpayer believes one thing: “A married woman can keep 500 grams of gold, so nobody can question it.” Is that true?
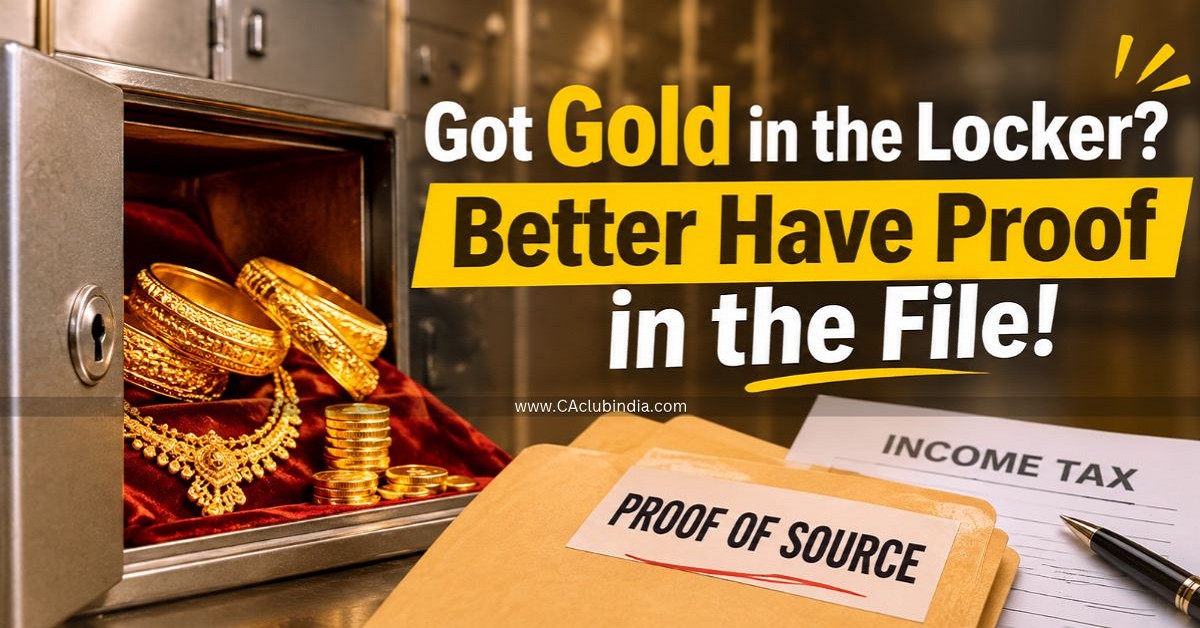
Krishna (Fictional Character): Arjuna, this belief was recently tested before the Supreme Court, and it did not survive! On 2nd November 2026, in State of Bihar vs Phulpari Kumari, the Court held that being permitted to hold gold and being able to explain its source are two very different things.
Arjuna (Fictional Character): Krishna, what was the case about?
Krishna (Fictional Character): Arjuna, in 2015 a disproportionate assets case was registered against a public servant in Bihar. She approached the Patna High Court, relying on CBDT Instruction No. 1916 dated 11th May 1994 and the Finance Ministry Press Release dated 1st December 2016, which allow a married woman to hold 500 grams of gold. The High Court agreed and quashed the case. But the Supreme Court called this reasoning totally untenable. It held that showing a circular does not amount to explaining how the gold was acquired, and sent the case back for trial. The accused can still raise other defences, but the “500 gram shield” is gone.
Arjuna (Fictional Character): Krishna, then what do these circulars really say?
Krishna (Fictional Character): Arjuna, they are only guidelines for officers conducting a search under Section 132 of the Income Tax Act. During a search, gold up to 500 grams per married woman, 250 grams per unmarried woman and 100 grams per male member is ordinarily not seized. The 2016 Press Release further clarified that jewellery bought from disclosed income, exempt income such as agricultural income, reasonable household savings or inheritance is not taxable, whatever the quantity. So the limit protects gold from seizure, not from questions.
Arjuna (Fictional Character): Krishna, what about gold received as gifts or inherited, and gold sold later?
Krishna (Fictional Character): Arjuna, under Section 56(2)(x), gold received from relatives, on the occasion of marriage, or through inheritance is fully exempt. But gold from a non-relative on any other occasion becomes taxable if its value exceeds Rs. 50,000 in a year. When jewellery is sold after 24 months, the gain is taxed as long term capital gain at 12.5%; within 24 months, it is taxed at slab rates. In both situations, the bill or valuation report decides how smoothly the taxpayer can prove the cost and source.
Arjuna (Fictional Character): So what should a taxpayer keep ready?
Krishna (Fictional Character): Arjuna, every gram needs its paper trail: jeweller’s invoices with bank payment proof, gift letters and wedding photographs for wedding gold, and a will or valuation report for inherited jewellery. Taxpayers with income above Rs. 50 lakh must also report jewellery in Schedule AL of the ITR.
Take Mrs. A, who holds 400 grams, received at her wedding and bought from her salary, with gift letters and invoices in place. She can face any officer calmly. Mrs. B holds the same gold with no papers and simply says “the circular allows it.” After this judgment, that answer will not work.
Arjuna (Fictional Character): Krishna, what is the lesson to remember?
Krishna (Fictional Character): Arjuna, a circular may keep gold safe in the locker, but only proof keeps the taxpayer safe in the file. So this wedding season, buy gold with joy, but collect the bill with equal care. In the eyes of the law, it is not the weight of the gold that counts, but the weight of the proof behind it!
You have reached your daily limit of 2 Free Articles
Subscribe to CCI PRO for unlimited access
Why Upgrade to CCI PRO?
- No Ads
- WhatsApp Community
- Daily E-Newsletter
- Unlimited Articles Access
- Profile Visitors
- Link Social Profiles
- Featured Job Posts
- Pro Badge
- Expert GST Guidance
- Unlimited Forum Replies
- Download Content in PDF
Already a PRO member? Login here for an ad-free experience. 07941056694









 CAclubindia
