
Quick Summary
Non Applicability
- Government ownership in the entity
- Government grants for which value cannot be ascertained
- Government grants covered under Ind AS 41
- Government grants with respect to which infrastructure development for irrirgation, communication or transport for a local community.
- Government grants for which benefits are available in the form of income tax liability calculation and whose benefits are available in determining taxable profits or taxable losses.
Recognition criteria
When there is reasonable assurance that:
- Grants will be received
- Entity will comply with the conditions attached to the receipt of government grant
- Receipt of government grant is not conclusive evidence for recognition.
Grants related to income and expenditure
Income
- To be disclosed separately in the statement to profit and loss as Other Income
- If expenditure is already incurred, then it can be deducted from the related expense and shown as net income
- If expenditure is yet to be incurred, then the government grant receipt is to be disclosed as a liability. The same to be reversed as and when expenditure is incurred.
Non Monetary Grant and non-depreciable asset
Non Monetary Grant
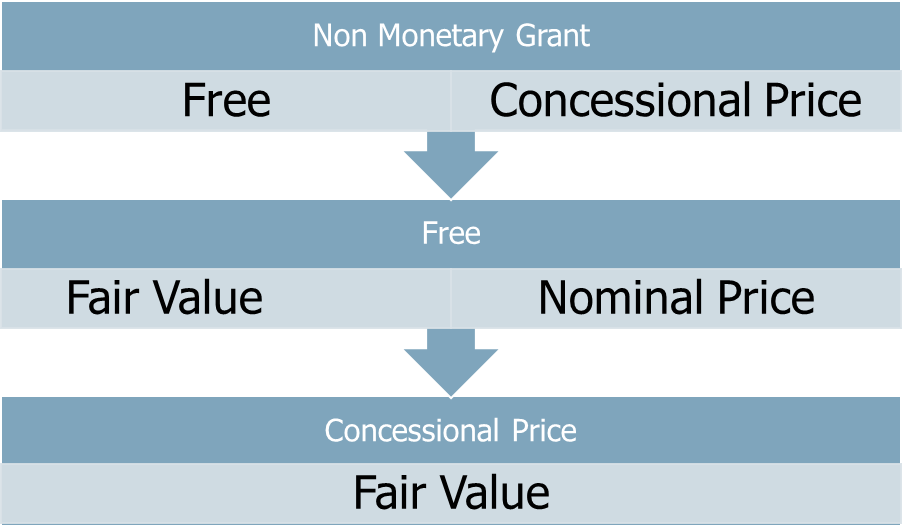
Accounting entry
- Asset A/c Dr
- To Bank A/c
- To Fair value gain a/c
A. If conditions are attached
Fair value gain to be amortized over the period over which conditions attached are being fulfilled.
B. If conditions are not attached
Fair value gain in such a case should be charged off to P&L immediately.
Depreciable Assets
Option I
Deduct the amount of government grant from the cost of the asset
Option II
- Create a deferred government grant account in the Balance Sheet as a deferred income.
- To be recognized in the statement to profit and loss account in a systematic basis over the useful life of the asset.
Loans at less than market value of interest
To be recognized and measured as per Ind AS 109.
- Cash flows to be determined based on reduced interest rate and repayment terms
- Discounting to be done based on market interest rate.
- Government grant income to be charged to P&L as and when conditions are met.
Entry
- Bank a/c Dr
- To Loan a/c
- To government grant a/c
Forgivable loans
- If conditions are already met, then immediately transfer it to P&L
- If conditions are required to be complied on a continuous basis then over the period over which the conditions are to be complied.
Refund of government grants
To be accounted for as a change in accounting estimate and treated in accordance with Ind AS 8.
- if deducted from cost of asset => add bank
- If deferred government grant is created => Reverse the same.
- If credited to P&L => charge it to P&L
Source ICAI








 CAclubindia
