
The author in this article covers the following topics -
A. Companies Act, 2013 Perspective
B. Income Tax Act, 1961
Companies Act, 2013 Perspective
Applicability of CSR
Section 135 of Companies Act, 2013
Every company including foreign company whose
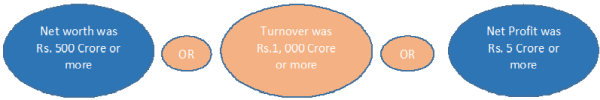
In the preceding financial year.
Meaning of CSR
Corporate Social Responsibility in simple terms means a company's responsibility to contribute towards society. Many big business houses were already involved in doing CSR voluntarily, however, with the introduction with Section 135, it was made mandatory for those companies who fulfil the criteria mentioned therein.
The purpose behind introduction of said section was to encourage businesses to work actively for social causes. Businesses should integrate considerations for environmental safety, climate concerns, human rights & combating corruptions.
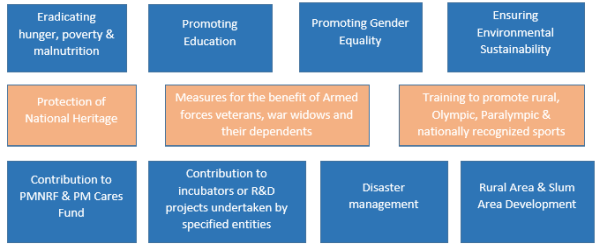
Activities as specified in Schedule VII of the Companies Act, 2013 are covered under CSR.
A glimpse of same is given below
Consequences of Non Compliance
For Company:
- Fine ranging from Rs. 50,000 to Rs.25 Lakhs
For Every Officer:
- Imprisonment up to 3 years OR
- Fine Rs. 50,000 to Rs. 5 Lakh OR
- Both
Income Tax Act, 1961 Perspective
Meaning of CSR
Meaning or definition of CSR has not been specified in Income Tax Act, 1961
So How do we determine whether expenses considered as CSR in books of account is CSR from the perspective of Income Tax also.
To understand this, let’s have a look at Explanation 2 to Section 37(1) of the Income Tax Act, 1961:
Explanation: 2- It is declared that for the purpose of subsection (1) any expenditure incurred by an assessee on the activities relating to corporate social responsibility referred to section 135 of the Companies Act, 2013 shall not be deemed to be an expenditure incurred by the assessee for the purpose of business or profession
In light of the above, it is clear that any expenditure which is by virtue of Section 135 of Companies Act,2013 CSR has been taken into books of account shall be considered as CSR expenditure for the purpose of Income Tax also.
Allowability of CSR Expenditure
Considering Explanation 2 to Section 37(1) of the Income Tax Act, 1961 that we have just read above, any CSR expenditure incurred shall not be allowed as deduction in Income Tax Act.
The same can be further understood from FINANCE (NO. 2) BILL, 2014 - MEMORANDUM - PROVISIONS RELATING TO DIRECT TAXES.
The relevant extract of same is given below
Under the existing provisions of the Act expenditure incurred wholly and exclusively for the purposes of the business is only allowed as a deduction for computing taxable business income. CSR expenditure, being an application of income, is not incurred wholly and exclusively for the purposes of carrying on business. Moreover, the objective of CSR is to share burden of the Government in providing social services by companies having net worth/turnover/profit above a threshold. If such expenses are allowed as tax deduction, this would result in subsidizing of around one-third of such expenses by the Government by way of tax expenditure.
The existing provisions of section 37(1) of the Act provide that deduction for any expenditure, which is not mentioned specifically in section 30 to section 36 of the Act, shall be allowed if the same is incurred wholly and exclusively for the purposes of carrying on business or profession. As the CSR expenditure (is not incurred for the purposes of carrying on business, such expenditures cannot be allowed under the existing provisions of section 37 of the Income-tax Act.
However, the CSR expenditure which is of the nature described in section 30 to section 36 of the Act shall be allowed deduction under those sections subject to fulfilment of conditions, if any, specified therein.(Note – We shall have a detailed analysis of this in the next article)
You have reached your daily limit of 2 Free Articles
Subscribe to CCI PRO for unlimited access
Why Upgrade to CCI PRO?
- No Ads
- WhatsApp Community
- Daily E-Newsletter
- Unlimited Articles Access
- Profile Visitors
- Link Social Profiles
- Featured Job Posts
- Pro Badge
- Expert GST Guidance
- Unlimited Forum Replies
- Download Content in PDF
Already a PRO member? Login here for an ad-free experience. 07941056694







 CAclubindia
