The Central Board of Indirect Taxes and Customs (CBIC) has appointed the Principal Commissioner or Commissioner of Customs, Hyderabad, as the common adjudicating authority for a long-pending show cause notice issued to Tirupati Udyog Limited, Kottur.
The appointment has been notified by the Ministry of Finance, Department of Revenue, through Notification No. 78/2026-Customs (N.T.) dated September 23, 2026, issued under S.O. 5239(E).
Details of the Show Cause Notice
According to the notification, the matter relates to Show Cause Notice No. VIII/26/23/2008-HRU dated November 6, 2008.
The notice was issued by the Additional Director General (ADG), Directorate of Revenue Intelligence (DRI), Zonal Unit, Chennai.
The proceedings concern Tirupati Udyog Limited, Kottur, and the CBIC has now specified the common adjudicating authority responsible for adjudicating the notice.
Hyderabad Customs Authority Appointed
The notification appoints the Principal Commissioner or Commissioner of Customs, Hyderabad, as the common adjudicating authority for the matter.
The authority is based at: GST Bhavan, Lal Bahadur Stadium Road, Basheerbagh, Hyderabad – 500004.
The appointed authority will exercise the powers and discharge the duties that have been conferred or imposed on the Commissioner of Customs and Central Excise, Hyderabad-IV Commissionerate, Hyderabad , for the purpose of adjudicating the show cause notice.
Notification Issued Under Customs Act, 1962
CBIC issued the notification in exercise of powers under Section 4 read with Section 3 and sub-sections (1) and (1A) of Section 5 of the Customs Act, 1962.
The notification also clarifies that it will come into force from the date of its publication in the Official Gazette.
Why the Notification Matters
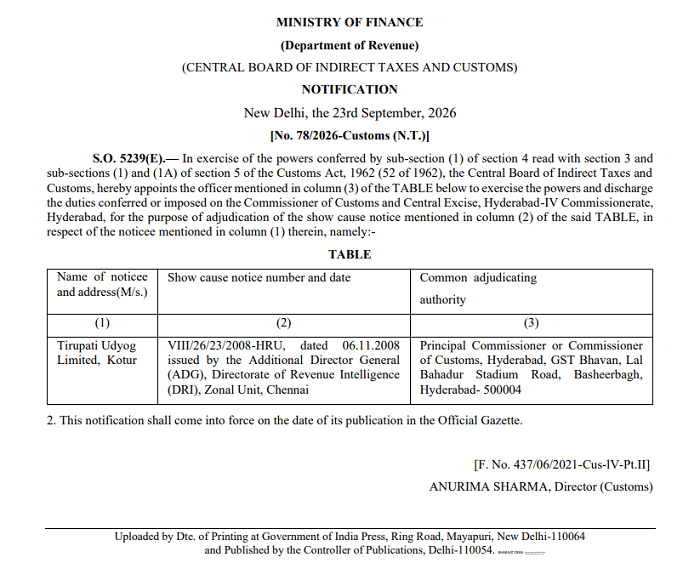
The latest CBIC notification formally identifies the authority that will handle the adjudication of the 2008 show cause notice involving Tirupati Udyog Limited.
By designating a common adjudicating authority, the notification provides clarity on the officer responsible for exercising the relevant statutory powers and carrying forward the adjudication proceedings.
The development is particularly relevant for businesses, tax professionals and customs practitioners tracking legacy customs proceedings and adjudication matters.









 CAclubindia
