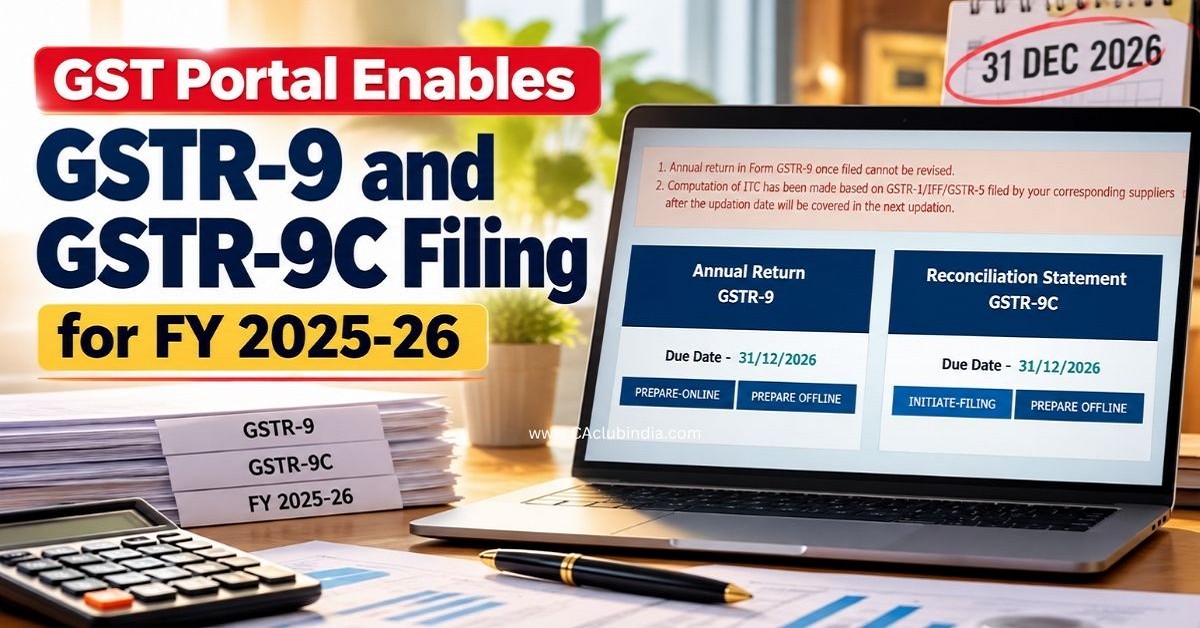
The Goods and Services Tax Network (GSTN) has made the annual return filing facility available on the GST portal for FY 2025-26. Taxpayers covered by the applicable provisions can now access the forms and begin preparing their annual GST returns.
The development is particularly relevant for businesses that need to reconcile their books of accounts with GST returns filed during the financial year. Starting the process early can help taxpayers identify reporting differences, verify ITC claims and avoid last-minute filing issues.
What Are GSTR-9 and GSTR-9C?
- GSTR-9 is the annual return filed by eligible registered taxpayers. It consolidates information relating to outward and inward supplies, tax paid, ITC availed, reversals and other details reported during the financial year.
- GSTR-9C is a reconciliation statement that compares the turnover and other relevant figures reported in the annual return with the corresponding figures in the taxpayer's audited financial statements or books of accounts, as applicable. It is required for taxpayers whose aggregate turnover exceeds the prescribed threshold.
Both forms help provide a consolidated view of a business's GST compliance for the financial year.
GSTR-9 and GSTR-9C Due Date for FY 2025-26
Under Section 44 of the Central Goods and Services Tax (CGST) Act, 2017, read with Rule 80 of the CGST Rules, 2017, the annual return is generally due by December 31 following the end of the relevant financial year, unless the due date is extended.
For FY 2025-26, the GST portal displays December 31, 2026, as the due date.
Taxpayers should complete the reconciliation and filing process well before the deadline to reduce the risk of errors, portal-related delays and late fees.
Who Needs to File GSTR-9 and GSTR-9C?
The filing requirements depend on the taxpayer's registration status, aggregate turnover and applicable exemptions.
- GSTR-9: Registered taxpayers required to furnish the annual return under Section 44 of the CGST Act must file it, subject to applicable exemptions. Notification No. 15/2025-Central Tax dated September 17, 2025, exempts taxpayers having aggregate turnover of up to ₹2 crore from filing GSTR-9, subject to the terms of the notification.
- GSTR-9C: Registered taxpayers whose aggregate turnover exceeds ₹5 crore are required to furnish the reconciliation statement along with the annual return, as applicable under the relevant provisions.
Taxpayers should verify their eligibility and the applicable requirements before proceeding with filing.









 CAclubindia
