The All India MSME and Tax Professionals Association (AIMTPA) has requested the Government to rationalise the income-tax compliance calendar for Assessment Year (AY) 2026-27, citing the limited time available between non-audit return filing and tax audit compliance.
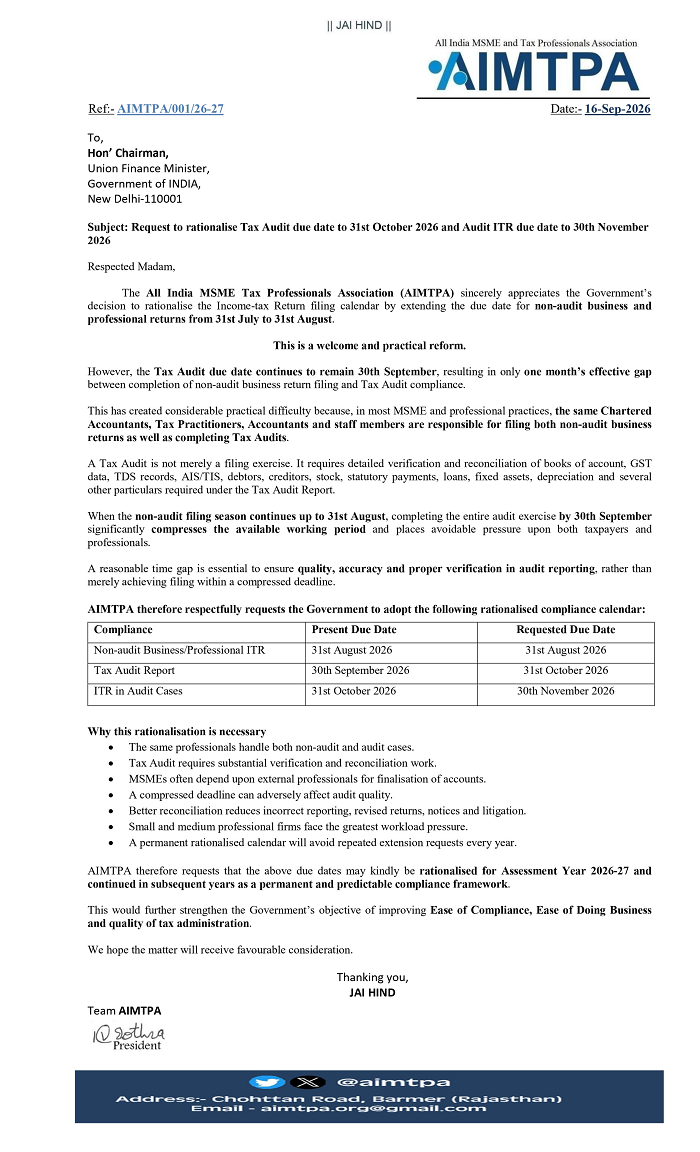
In a letter dated 16 September 2026 addressed to the Union Finance Minister, AIMTPA proposed shifting the tax audit report due date from 30 September 2026 to 31 October 2026 and the ITR filing deadline for audit cases from 31 October 2026 to 30 November 2026.
The association has also requested that the revised timeline be adopted as a permanent compliance framework for subsequent years.
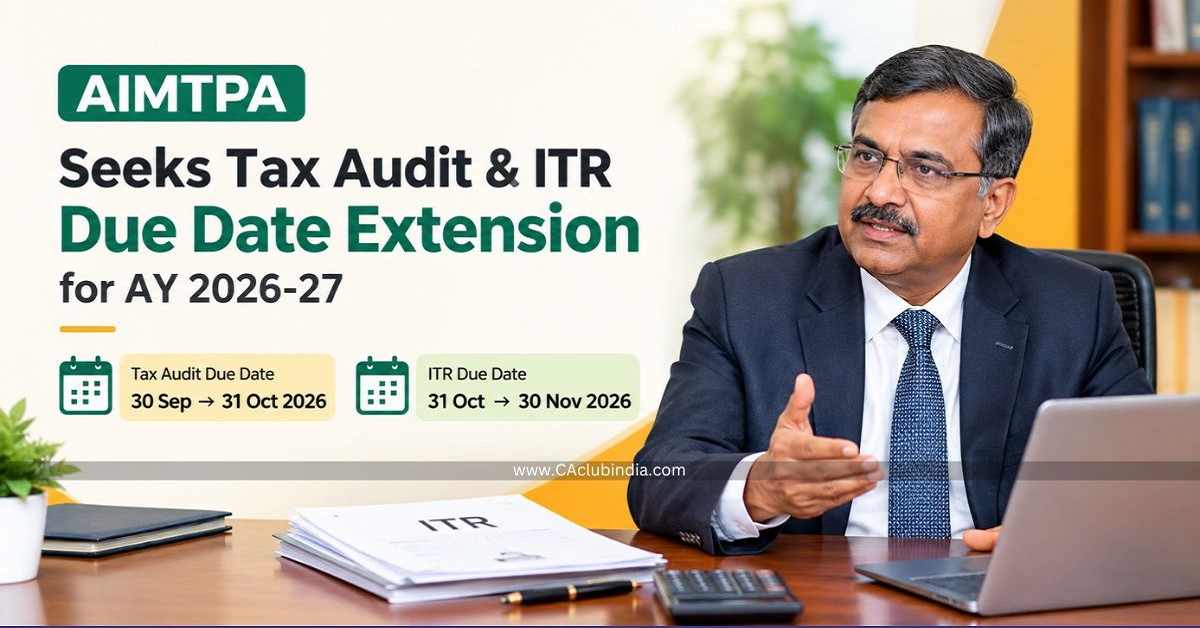
AIMTPA's Proposed Compliance Calendar
According to the representation, the proposed changes are:
| Compliance | Existing Due Date | AIMTPA's Requested Due Date |
|---|---|---|
| Non-audit Business/Professional ITR | 31 August 2026 | 31 August 2026 |
| Tax Audit Report | 30 September 2026 | 31 October 2026 |
| ITR in Audit Cases | 31 October 2026 | 30 November 2026 |
The Income Tax Department currently states that the tax audit report for AY 2026-27 is due on 30 September 2026, while the audit-case ITR deadline is generally linked to the applicable return due date.
Why AIMTPA Has Requested More Time
AIMTPA pointed out that many Chartered Accountants, tax practitioners, accountants and their staff handle both non-audit return filings and tax audit assignments. With the non-audit filing deadline falling on 31 August, professionals have only one month to complete the audit process before the existing 30 September deadline.
The association said tax audit work involves considerably more than filing a report. It requires verification and reconciliation of areas such as:
- Books of account
- GST data
- TDS records
- AIS/TIS information
- Debtors and creditors
- Stock and inventory
- Statutory payments
- Loans and borrowings
- Fixed assets and depreciation
- Other information required for the tax audit report
According to AIMTPA, completing these activities within a compressed period may put additional pressure on professionals and taxpayers, particularly MSMEs that depend on external accounting and tax professionals.
Association Seeks a Permanent Calendar
AIMTPA has requested that the proposed dates be considered not only for AY 2026-27, but also for subsequent years. The association said a predictable compliance calendar could reduce the need for repeated requests for extensions and provide professionals and taxpayers with more time for verification and reconciliation.
The request is a representation to the Government and does not itself change the statutory due dates. Taxpayers should continue to follow officially notified deadlines unless the Government announces any change.
What Taxpayers and Professionals Should Note
For AY 2026-27, the Income Tax Department has confirmed that the tax audit for FY 2025-26 continues under the Income Tax Act, 1961, with Forms 3CA/3CB and Form 3CD applicable as prescribed. The Department currently lists 30 September 2026 as the tax audit report due date for AY 2026-27.
Therefore, AIMTPA's requested dates should be viewed as a proposal pending consideration by the Government, rather than an extension already granted.









 CAclubindia
