Two fresh writ petitions filed in the Madhya Pradesh High Court have intensified the debate around the upcoming September 30 tax audit deadline, leaving tax professionals across the state on high alert.
With time running out for AY 2026-27 (FY 2025-26), Chartered Accountants and tax consultants argue that the compliance schedule has left them severely constrained. Because non-audit Income Tax Returns (ITRs) closed on August 31, professionals were left with only a single month to reconcile accounts, handle system updates, process high volumes of client books, and submit Forms 3CA, 3CB, and 3CD.
Key Details of the Filed Petitions
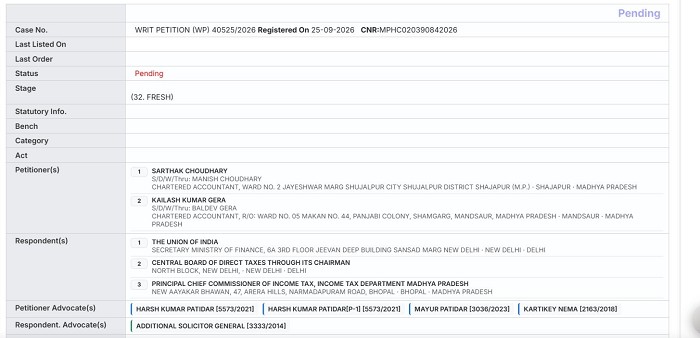
I. WP/40525/2026 (Sarthak Choudhary vs. Union of India): Asks the High Court to intervene following a lack of official extension notification from the Central Board of Direct Taxes (CBDT). The plea highlights major operational bottlenecks, including delayed utility releases, complex reconciliation needs, concurrent GST/TDS filing deadlines, and potential portal crashes during peak usage.
II. WP No. 40462/2026 (Madhya Pradesh Tax Consultants Association): Escalates a representation previously sent to the Finance Ministry directly to the courtroom. The MPTCA is requesting the tax audit report deadline be pushed to November 30, 2026 and the audited ITR deadline to December 31, 2026.
The Broader Legal and Industry Context
The petitions follow a pattern seen in previous assessment cycles, where last-minute pressure from various High Courts led to administrative relief from the CBDT. Professional organizations across India from Jalandhar to Bhilwara have raised similar demands, generally requesting a deadline shift to October 31.
As it stands, statutory timelines remain unchanged for ordinary Section 44AB cases:
| Compliance Item | Current Due Date |
| Tax Audit Reports (Forms 3CA/3CB & 3CD) | September 30, 2026 |
| ITR for Audited Assessees | October 31, 2026 |
| Transfer Pricing Cases | Later specified dates |
What is at Stake for Taxpayers and CAs?
Non-compliance carries financial consequences under Section 271B, which imposes a penalty of 0.5% of total turnover or gross receipts (capped at Rs 1.5 lakh). Beyond direct fines, tax professionals caution that rushed audits increase the probability of errors in Form 3CD disclosures, potentially triggering future tax notices and unnecessary litigation.
The MPTCA emphasized in its submission that extending the audit window does not alter or delay tax revenue collections, as advance tax liabilities, self-assessment tax and applicable statutory interest under Sections 234A, 234B and 234C remain fully intact.








 CAclubindia
