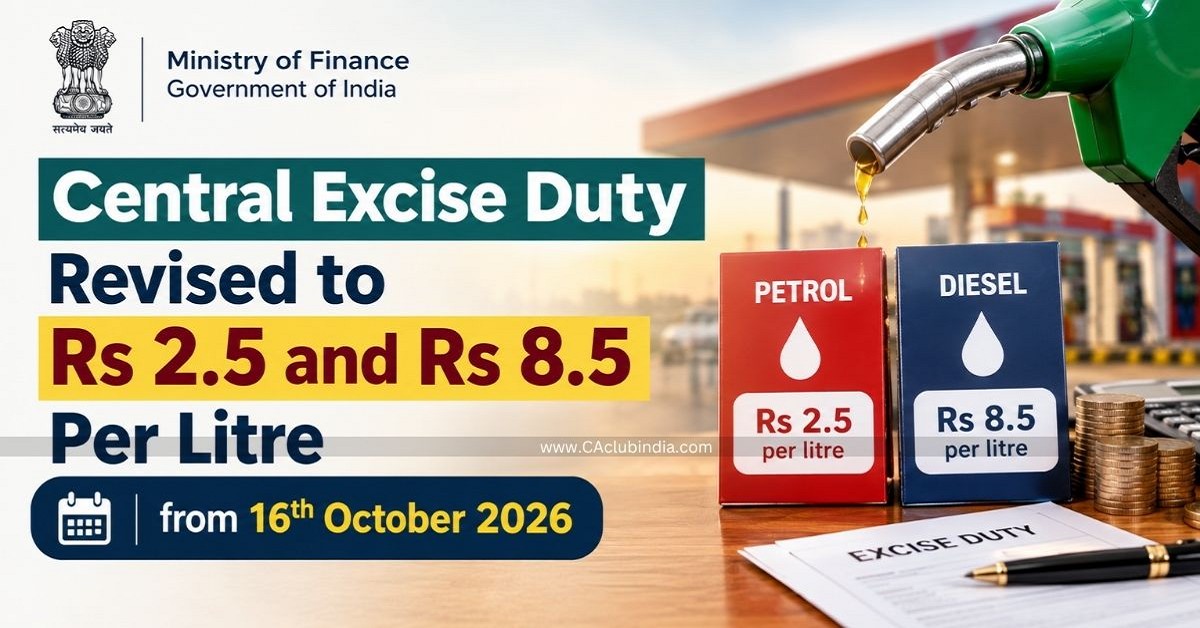
The Ministry of Finance has revised the specified per-litre entries under the Central Excise duty notification through Notification No. 54/2026-Central Excise, dated 15 October 2026. The revised rates will come into effect from 16 October 2026.
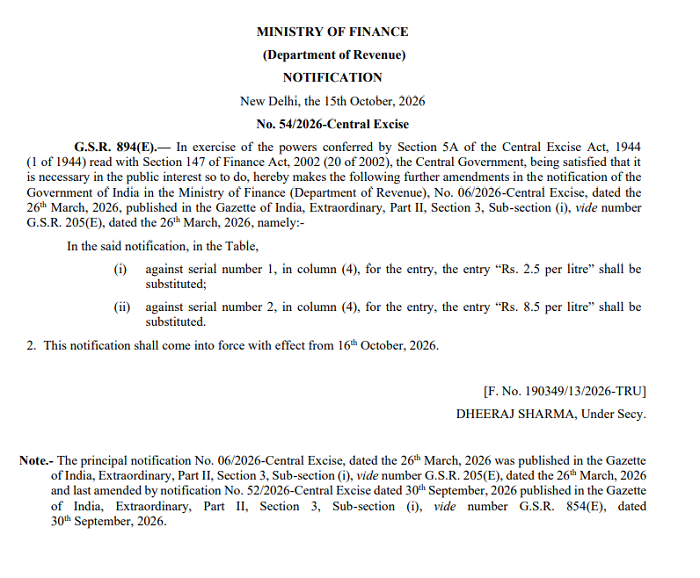
Issued by the Department of Revenue, the notification amends the earlier Notification No. 06/2026-Central Excise, dated 26 March 2026, by substituting the existing entries against serial numbers 1 and 2 in the relevant table.
Revised Central Excise Rates
Under the latest notification, the following entries have been substituted:
- Serial Number 1: The applicable rate is revised to ₹2.5 per litre.
- Serial Number 2: The applicable rate is revised to ₹8.5 per litre.
These changes have been made under the powers conferred by Section 5A of the Central Excise Act, 1944, read with Section 147 of the Finance Act, 2002.
Effective Date of the Amendment
The revised rates will take effect from 16 October 2026. Businesses and other stakeholders dealing with the products covered under the relevant notification should review the amended entries and ensure that applicable duty calculations and compliance procedures reflect the revised rates from the effective date.
Background of the Notification
Notification No. 54/2026-Central Excise further amends Notification No. 06/2026-Central Excise, originally issued on 26 March 2026. The principal notification was subsequently amended by Notification No. 52/2026-Central Excise, dated 30 September 2026.
The latest amendment has been issued in the public interest by the Central Government and published by the Ministry of Finance, Department of Revenue.
Notification Details
- Notification Number: 54/2026-Central Excise
- Date of Issue: 15 October 2026
- Effective Date: 16 October 2026
- Issuing Authority: Ministry of Finance, Department of Revenue
- Reference: G.S.R. 894(E)
Stakeholders should refer to the official notification and the relevant entries in the principal notification to identify the products covered by the revised rates and determine their applicability.








 CAclubindia
