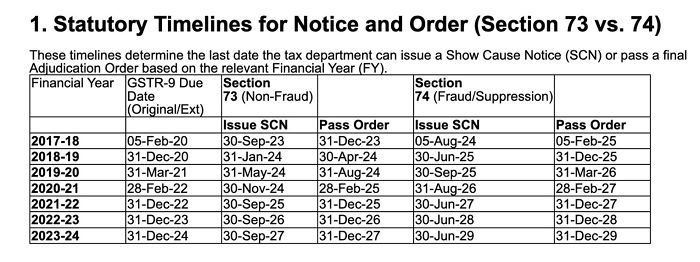
GST Penalty Provisions under Section 73 vs Section 74

Penalties vary significantly depending on whether the case involves bona fide errors (Section 73) or intentional fraud/suppression (Section 74).
Replies (2)
Quick Summary
GST penalty provisions differ under Sections 73 and 74. Section 73 covers genuine errors without fraud and usually attracts lower penalties, while Section 74 applies to fraud or suppression cases with much higher penalties. Early payment and timely response can significantly reduce penalty exposure.

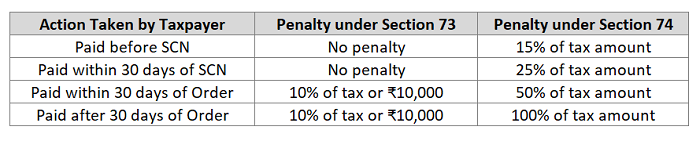
Section 73 applies when tax was unpaid due to a genuine mistake, no fraud involved: the demand can be settled at 10% penalty if you pay before the notice. Section 74 is for fraud or deliberate suppression and carries 100% penalty, but even under 74, if you pay before the SCN is issued you pay zero penalty.

The key is responding quickly once you get a notice, because the penalty percentage goes up at each stage. Check the notice header carefully as it will mention which section is being invoked.

Leave a Reply

Your are not logged in . Please login to post replies

Click here to Login / Register  

Company
05 October 2026
Senior Accountant

Vision IT Peripherals Pvt Ltd

Mumbai

B.Com

View Details
Company
10 October 2026
Accounts Associate Level 1

Abic and Mani Chartered Accountants

Kottayam

B.Com

View Details
Company
17 September 2026
Chartered Accountant

Dass Gupta & Associates

Gurgaon

CA

View Details
Company
ARTICLESHIP 01 October 2026
Articled Assistant

KPSN & Associates LLP

Chennai

CA Inter

View Details
Company
15 September 2026
Client-site CA associate

Aditya Muley and Co

Mumbai

CA

View Details
Company
ARTICLESHIP 07 October 2026
Article Trainee/ CMA Trainee

RMA And Associates LLP

New Delhi

CA Inter

View Details

Company
18 September 2026
Accounts & Finance Specialist

ULTRA CHEMICAL WORKS

Thane

CA Final

View Details
Company
08 October 2026
SALES TELECALLER

HIRE NOVA

Lucknow

Graduate (Any)

View Details