Transfer pricing:
• Selection criteria for TP audits - Aggregate value of international transactions is INR 15 Crores or more
• Cases with international transactions amounting to lower than this threshold are picked up on the basis of judgment of the Indian Revenue Authorities (‘IRA’)
• TP cases handled by specialised officers designated as TPO’s as against AO who handle Corporate tax matters
International transactions consists of Goods, services, Loans and intangibles
What is Transfer Pricing
• Transfer pricing refers to the pricing of cross-border transactions between two associated entities
• When two related entities enter into any cross-border transaction, the price at which they undertake the transaction is ‘transfer price’
• Due to the special relationship between related companies, the transfer price may be different than the price that would have been agreed between unrelated companies
• Price between unrelated parties in uncontrolled conditions is known as the “arm’s length” price (ALP)
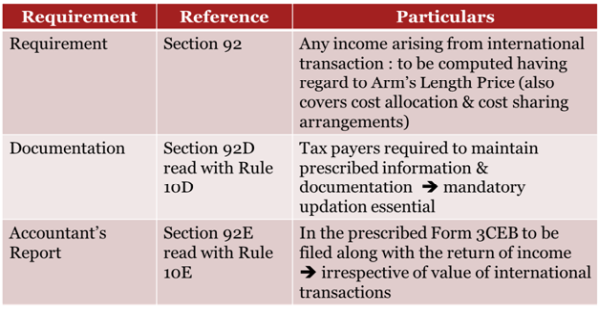
Compliance requirements
 ​
Relevant provisions
• 92: Computation of income from international transaction as per ALP
• 92(2A): Domestic TP: allowance for expenditure, interest, cost or expense or income in relation to SDT to be computed having regard to ALP
• 92A: Meaning of associated enterprise
• 92B: Meaning of international transaction èAmended by Finance Act 2014 to apply TP rules to transactions with a domestic unrelated party under specified conditions
• 92BA: Meaning of Specified Domestic Transaction
• 92C: Computation of arm’s length price
• 92CA: Reference to Transfer Pricing Officer
• 92CB: Power to make Safe Harbor Rules
• 92CC: Advance Pricing Agreement (APA) èAmended by Finance Act 2014 to include roll back provisions
• 92CD: Effect to Advance Pricing Agreement
• 92D: Maintenance of information & documents
• 92E: Accountant’s report
• 92F: Definition section
RULES
• 10A: Meaning of expressions used in computation of arm’s length price
• 10AB: Other method for determination of arm’s length price
• 10B: Determination of arm’s length price u/s 92C
• 10C: Most appropriate method
• 10D: information and documents to be kept and maintained u/s 92D
• 10E: Report from an accountant to be furnished u/s 92E
• 10F to 10T: APA Rules
• 10TA to 10TG: Safe Harbour rules
Others
• Base erosion is the important principle for attraction of TP provisions
• Provisions not to apply where ALP computation has effect of reducing income chargeable to tax or increasing loss
• No deduction available for TP adjustments after scrutiny by the AO under Sec. 10A, 10AA, 10B or Chapter VI-A as per proviso to Section 92CA(4)






 CAclubindia
