A small payment notice at a local grocery shop has caught attention online, highlighting a concern that many small retailers may face as India prepares to introduce new charges on certain UPI merchant transactions.
The sign, shared by journalist Arvind Sharma on X, appears to show a grocery shop adding a small charge for digital payments. While the notice is from an individual shop, it has sparked a wider conversation about who ultimately bears the cost when digital payment charges are introduced.
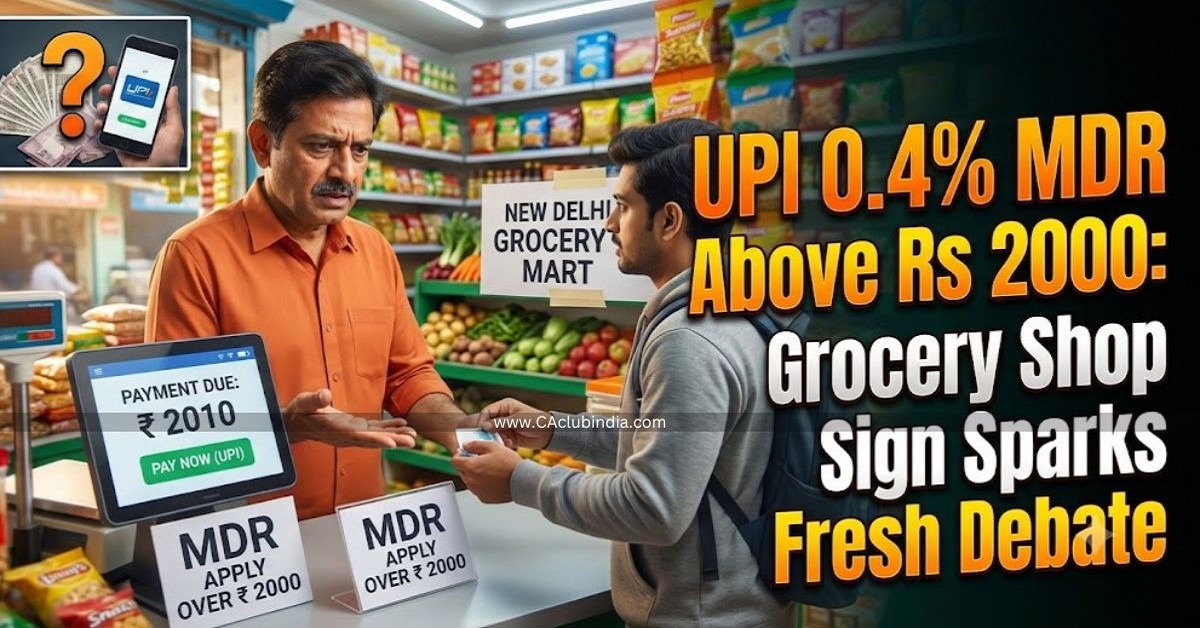
The discussion comes at a time when the government is preparing to introduce a 0.4% Merchant Discount Rate (MDR) on specified UPI person-to-merchant transactions above Rs 2000 from October 15, 2026.
What Is Changing in UPI Payments?
Under the new framework, a 0.4% MDR will apply to eligible UPI merchant transactions above Rs 2,000.
Importantly, the charge is a merchant-side payment cost, not a new tax or a fee that the government will directly collect from customers.
For eligible transactions, the MDR will be shared among participants in the payment ecosystem. The charge will be capped at Rs 300 for transactions of Rs 75,000 and above.
The changes do not apply to every UPI payment. Person-to-person transactions will continue to remain free, while merchant transactions of Rs 2,000 or below will also remain outside the new MDR structure.
चीनी
— Arvind Sharma (@sarviind) September 18, 2026
नगद : 60 रुपए
UPI : 61
क्रेडिट कार्ड : 62
अब बताओ; यह वसूली किससे हो रही है? pic.twitter.com/RJG8raGe9R
Small merchants receiving up to Rs 1 lakh per month through UPI QR payments will also continue to remain under the zero-MDR framework.
Why Are Small Grocery Shops Concerned?
For a large retailer, a small payment charge may appear manageable. For a neighbourhood grocery store operating on thin margins, however, every additional expense can matter.
A shopkeeper selling everyday products such as sugar, rice, pulses or other household essentials may make only a limited margin on individual items. When a significant portion of customers pay digitally, transaction-related costs can become another expense to consider.
That is why the grocery shop sign has resonated with many people.
It represents a very practical question for small businesses: if the cost of accepting digital payments increases, should the merchant absorb it or find another way to recover the expense?
Can Merchants Charge Customers for UPI Payments?
This is where the distinction between the MDR and a customer surcharge becomes important.
The new MDR is designed as a cost on the merchant side. The Finance Ministry has stated that banks have been advised to ensure that merchants do not pass the MDR on to customers.
Therefore, the introduction of MDR does not automatically mean that customers should be charged an additional amount simply for choosing UPI.
However, concerns remain about how individual businesses may respond in practice, particularly where profit margins are already narrow.
Will UPI Become More Expensive for Customers?
For most everyday UPI users, the immediate impact is expected to be limited because transactions of Rs 2000 or below remain outside the new MDR structure.
The government has also stated that around 96% of UPI person-to-merchant transactions will remain unaffected by the new pricing framework.
The bigger question concerns larger merchant payments and how businesses manage their costs.
A merchant could potentially decide to absorb the expense as part of operating costs. Others may reconsider their payment preferences or adjust their overall pricing strategy. Such responses would depend on the merchant, transaction value and business margins.
This is particularly relevant for small retailers, where even a seemingly small payment cost can add up over hundreds of transactions.
Why Cash is Still Appealing to Some Small Merchants
India's shift towards digital payments has made UPI an everyday part of retail life. A customer can scan a QR code and pay for groceries within seconds, without carrying cash.
But convenience for the customer does not necessarily mean zero cost for the business.
For a small shopkeeper, cash does not involve the same type of payment processing charge. As a result, some merchants may continue to prefer cash, especially for transactions where the profit margin is already low.
This creates an interesting push-and-pull in India's digital payment journey.
Customers increasingly expect UPI to be available everywhere, while merchants have to consider the economics of accepting different payment methods.
UPI's Changing Payment Landscape
The debate surrounding the grocery shop sign is therefore bigger than one payment notice.
UPI has grown into one of India's most widely used digital payment systems, particularly for small-value everyday purchases. The introduction of MDR for selected higher-value merchant transactions marks a change in how parts of the payment ecosystem are funded.
The government has maintained that the new framework is intended to support the sustainability of the UPI ecosystem while keeping the majority of everyday transactions unaffected.
For consumers, the key point is that UPI payments are not generally becoming subject to a blanket customer fee. For merchants, however, eligible transactions above Rs 2000 will introduce a new cost that businesses will need to account for.
As October 15 approaches, the real test will be how merchants respond on the ground and whether the new payment economics influence the way India's neighbourhood shops accept digital payments.







 CAclubindia

