The Tamil Nadu Government has brought significant changes to its State Goods and Services Tax (SGST) Act into effect from November 1, 2026, with the objective of simplifying GST compliance, improving cash flow for businesses and facilitating faster refunds for eligible taxpayers.
The amendments, introduced through the Tamil Nadu Goods and Services Tax (Second Amendment) Act, 2026, cover three important provisions: Sections 15, 34 and 54 of the Tamil Nadu GST Act, 2017.
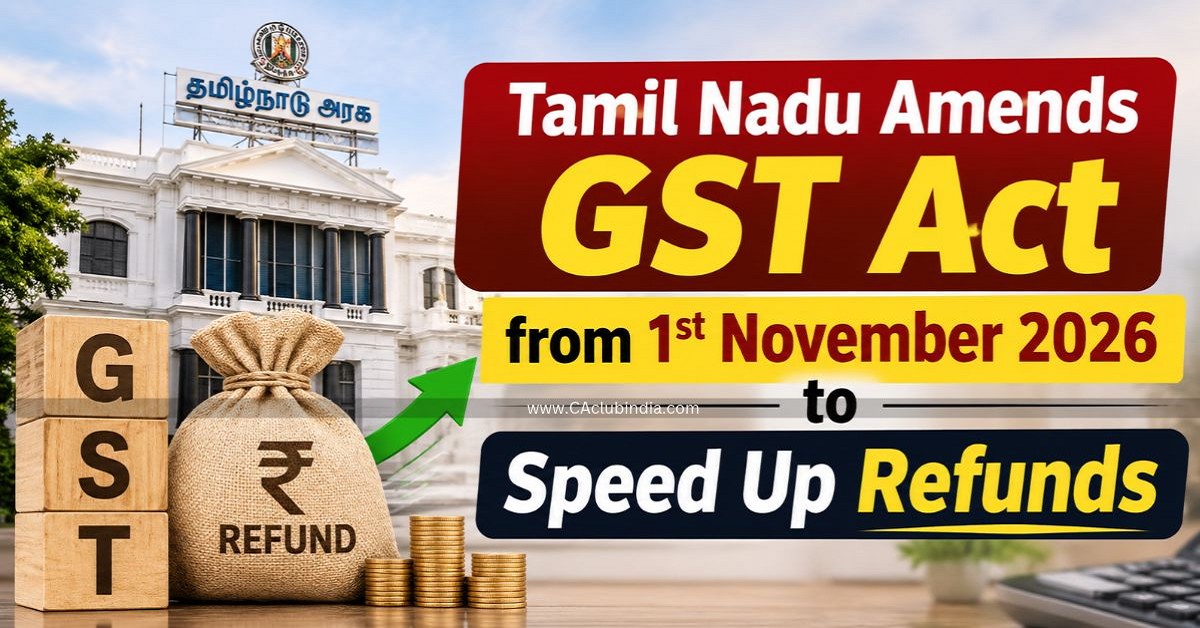
The Commercial Taxes and Registration Department issued a Gazette notification on October 27, 2026 , notifying November 1, 2026, as the effective date for these changes.
The amendments are particularly relevant for manufacturers, exporters and businesses that offer discounts after completing sales or accumulate Input Tax Credit (ITC) due to an inverted duty structure.
1. Post-Supply Discounts Can Now Be Excluded from Taxable Value
One of the important changes relates to the treatment of discounts offered by suppliers after the supply of goods or services.
Under the amended Section 15 of the Tamil Nadu GST Act, suppliers can exclude post-supply discounts from the taxable value by issuing credit notes, subject to the recipient reversing the corresponding Input Tax Credit attributable to such discounts.
Earlier, businesses had to satisfy specific conditions to exclude post-supply discounts from the taxable value. These included having an agreement entered into before or at the time of supply and linking the discount to relevant invoices.
The amendment removes these requirements, providing greater flexibility to businesses in structuring their post-sale discount arrangements.
However, the recipient must reverse the ITC attributable to the discount for the supplier to obtain the corresponding reduction in taxable value.
2. Section 34 Recognises Post-Supply Discounts for Issuing Credit Notes
Alongside the change in Section 15, the Government has amended Section 34 of the Tamil Nadu GST Act to formally recognise post-supply discounts as a valid basis for issuing GST credit notes.
This amendment brings the credit note provisions in line with the revised valuation rules and provides statutory clarity for businesses making price adjustments after completing a sale.
Consequently, businesses can account for eligible post-sale discounts through credit notes without having to meet the earlier requirement of a pre-existing agreement linked to specific invoices, subject to the applicable ITC reversal condition.
3. 90% Provisional GST Refund Extended to Inverted Duty Structure Cases
The amendment to Section 54 brings relief to eligible businesses facing an inverted duty structure.
An inverted duty structure arises when the GST paid on inputs or raw materials is higher than the GST charged on the finished products. This often results in an accumulation of unutilised ITC, affecting the working capital of businesses.
Under the amended provision, the facility of a 90% provisional refund has been extended to eligible unutilised ITC arising from an inverted duty structure, subject to prescribed conditions.
This will allow eligible businesses to receive a substantial portion of their refund upfront rather than waiting for the entire refund claim to be processed.
The measure is expected to improve liquidity and reduce the amount of working capital blocked in accumulated tax credits.
4. ₹1,000 Minimum Refund Threshold Removed for Exporters
Another significant change introduced through the amendment to Section 54 concerns GST refund claims for exported goods.
Earlier, a minimum refund threshold of ₹1,000 applied to refund claims. The amendment removes this minimum threshold for refund claims relating to goods exported outside India with payment of tax.
This means exporters can now claim eligible GST refunds even where the refund amount is below ₹1,000.
The change is expected to make the refund mechanism more accessible, particularly for exporters handling smaller transactions or low-value consignments.
5. Textile and Automobile Component Industries Expected to Benefit
The amendments are expected to provide practical relief to several manufacturing and export-oriented sectors in Tamil Nadu.
Businesses operating in the textile hubs of Tiruppur and Karur, along with automobile component manufacturers in Chennai, could benefit from improved cash flow and reduced working capital requirements.
The extension of provisional refunds will help eligible businesses unlock accumulated ITC, while the revised provisions on post-supply discounts will simplify commercial price adjustments.
Removing the minimum refund threshold for eligible export claims will also benefit exporters dealing with smaller refund amounts.
According to a senior Commercial Taxes Department official quoted by DT Next, these changes are expected to simplify tax procedures and reduce the money businesses have locked up in taxes.
Key Tamil Nadu GST Amendments Effective from November 1, 2026
|
GST Provision |
Key Amendment |
Expected Benefit |
|---|---|---|
|
Section 15 |
Post-supply discounts can be excluded from taxable value through credit notes, subject to ITC reversal |
Greater flexibility in discount arrangements |
|
Section 34 |
Post-supply discounts recognised as grounds for issuing credit notes |
Greater clarity in GST compliance |
|
Section 54 |
90% provisional refund extended to eligible unutilised ITC arising from inverted duty structure |
Improved working capital |
|
Section 54 |
₹1,000 minimum refund threshold removed for eligible export claims involving payment of tax |
Easier access to export refunds |
What These Changes Mean for Businesses
The Tamil Nadu GST amendments represent an important step towards simplifying tax administration and improving liquidity for businesses.
The changes offer three major advantages:
-
Simplified discount compliance: Businesses can issue credit notes for eligible post-supply discounts without the earlier requirement of a pre-existing agreement linked to specific invoices.
-
Faster access to refunds: Eligible taxpayers facing an inverted duty structure can benefit from a 90% provisional refund facility.
-
Relief for exporters: Removal of the ₹1,000 minimum refund threshold makes eligible export refund claims more accessible.
Businesses should review their credit note practices, ensure appropriate ITC reversals by recipients and assess their eligibility for provisional refunds under the amended provisions.
With effect from November 1, 2026, these changes are expected to reduce tax-related working capital pressure and make GST compliance more business-friendly for manufacturers and exporters operating in Tamil Nadu.








 CAclubindia
