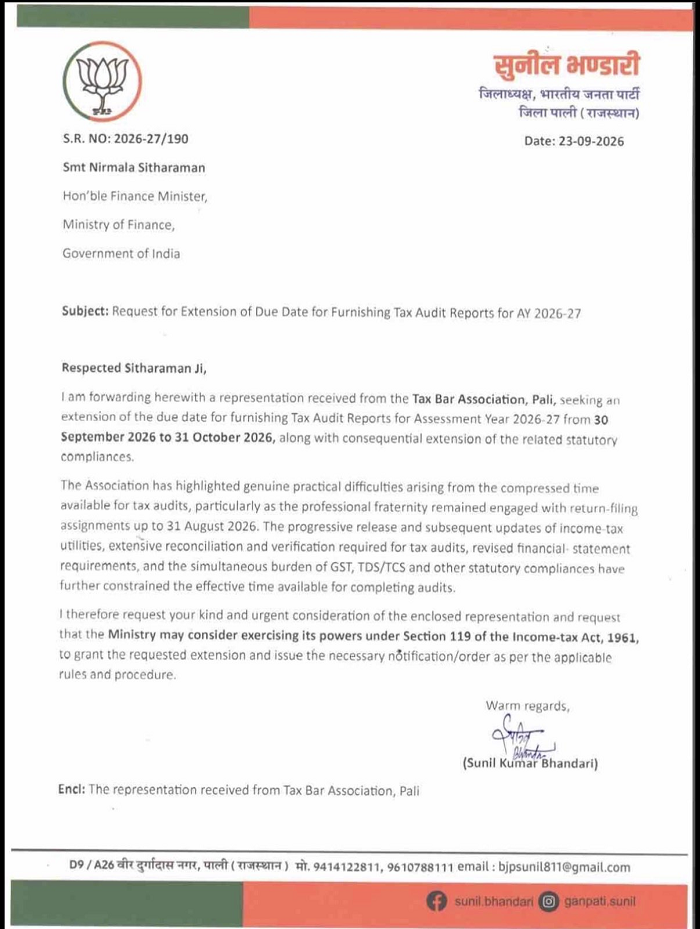
The demand for an extension of the tax audit due date for AY 2026-27 has reached the Ministry of Finance, with BJP Pali district president Sunil Kumar Bhandari forwarding a representation from the Tax Bar Association, Pali, to Union Finance Minister Nirmala Sitharaman.
In a letter dated September 23, 2026, Bhandari requested the Finance Ministry to consider extending the deadline for furnishing tax audit reports from September 30, 2026, to October 31, 2026. He also sought a consequential extension of the related statutory compliance deadlines.
Tax professionals cite compressed timeline for audits
The representation highlights the limited time available to tax professionals to complete tax audits this year. According to the letter, professionals remained occupied with return-filing assignments until August 31, 2026, leaving a relatively short window for completing the remaining audit work.
The representation also points to the progressive release and subsequent updates of income-tax utilities, along with the extensive reconciliation and verification required during tax audits.
Additional challenges mentioned include revised financial statement requirements and the simultaneous compliance burden involving GST, TDS, TCS and other statutory requirements.
Request made under Section 119 of the Income Tax Act
Bhandari has requested the Finance Ministry to examine the representation and consider exercising its powers under Section 119 of the Income-tax Act, 1961, to grant the requested extension.
The letter specifically asks the Ministry to issue the necessary notification or order in accordance with the applicable rules and procedures.
Demand for extension of tax audit deadline
The representation adds to the ongoing requests from professional and tax practitioner bodies seeking additional time for completing tax audit reports for AY 2026-27.
For taxpayers covered by tax audit provisions, the September 30 deadline is significant because several subsequent compliance requirements are linked to the completion of the audit process. Any extension granted by the government would therefore provide additional time for professionals and taxpayers to complete the related compliances.
As of the letter dated September 23, 2026, the document represents a request for an extension; it does not itself constitute an extension of the statutory deadline. The final decision rests with the competent authorities.









 CAclubindia
