Doubt of GSTR1 Filing

Hello,

I have been filing GST Returns for Few Months and I have this Doubt.

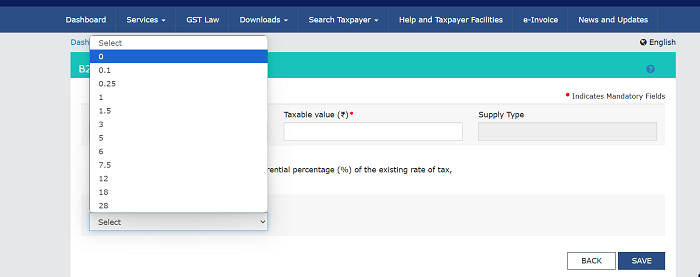
There is a seperate Table for "Nil Rated, Exempted and Non-GST Supplies",

In the Table

1)"4A, 4B, 6B, 6C - B2B, SEZ, DE Invoices" And

2) "7 - B2C (Others)" 

There is an option for entering 0% Sales.

In Which Situvation we will fill this coloumn,

Why they are providing this when we have seperate table for "Nil Rated, Exempted and Non-GST Supplies".

In "4A, 4B, 6B, 6C - B2B, SEZ, DE Invoices" Table.
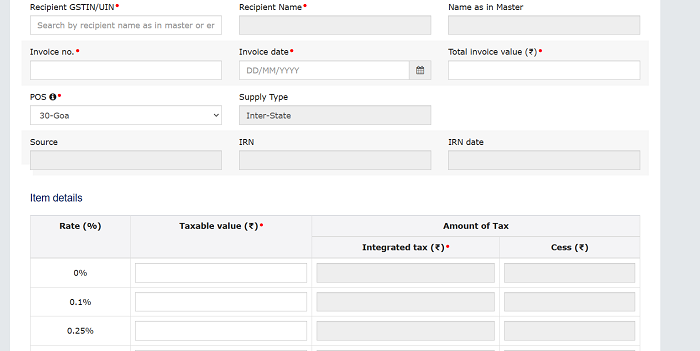
 

In "7 - B2C (Others)" Table. 


Replies (2)
Quick Summary
This discussion clarifies the distinction between Nil Rated, Exempted, and Non-GST supplies within GSTR1 filing. It explains why these categories are reported separately, particularly in Tables 4A, 4B, 6B, 6C (B2B) and Table 7 (B2C). The key difference lies in their impact on Input Tax Credit (ITC) calculation and aggregate turnover, with nil-rated supplies being taxable at 0% and exempt supplies requiring ITC reversal.

"Zero" rated supplies means supplies of goods and services or both to

a) Export of goods or services or both: or

b) Supplies to Specinal Economic Zone Developer or to a Special Economic Zone units.

The distinction in GSTR-1 Table 8 between these three categories matters for ITC calculation and aggregate turnover:

- Nil Rated (0% GST): Taxable supply where GST rate is 0%. Buyer cannot claim ITC from nil-rated purchases. Examples: food grains, salt.
- Exempt Supply: Supply notified as exempt under Section 11 of CGST Act. No GST applicable. ITC on inputs used for exempt supply must be reversed under Rule 42/43. Examples: fresh vegetables, healthcare services.
- Non-GST Supply: Outside the scope of GST entirely (not covered by the Act). Must be reported in GSTR-1 Table 8 for aggregate turnover but no GST applies. Examples: alcohol for human consumption, petroleum products, electricity.

Why it matters practically: If you have exempt supplies, you must reverse ITC proportionately (Rule 42/43). If you have nil-rated supplies, no ITC reversal is needed since nil-rated is still a taxable supply. The classification directly affects how much ITC you can retain.

For QRMP filers, this table is filed in the IFF only for B2B transactions, B2C nil/exempt/non-GST is reported in the quarterly GSTR-1.

This [GST filing blocked and ITC mismatch guide](https://taxgarden.in/blog/gst-filing-blocked-3-year-cutoff-bank-mismatch-2026) covers related GSTR-1 classification and ITC scenarios in detail.

Leave a Reply

Your are not logged in . Please login to post replies

Click here to Login / Register  

Company
12 October 2026
Chartered Accountant - Internal Audit

HKC | Chartered Accountants & Business Advisors

Ludhiana

CA

View Details
Company
15 October 2026
Senior Accountant

Continental Belting Pvt Ltd

Mumbai

B.Com

View Details
Company
19 October 2026
Accountants/Articles (Freshers/Experienced)

ADY & CO.

New Delhi

Graduate (Any)

View Details
Company
14 October 2026
Accountant

Rize.farm

Bengaluru

B.Com

View Details
Company
ARTICLESHIP 07 October 2026
Article Assistant

Malhotra Rajesh & Associates

New Delhi

B.Com

View Details
Company
ARTICLESHIP 07 October 2026
Article assistant

S.K.Bajpai & Co.

Noida

B.Com

View Details
Company
13 October 2026
Accountant

Zerdi & Co. Chartered Accountants

Pune

B.Com

View Details
Company
ARTICLESHIP 30 September 2026
CA Article Assistant

CA Suraj Garg & Associates

New Delhi

CA Final

View Details