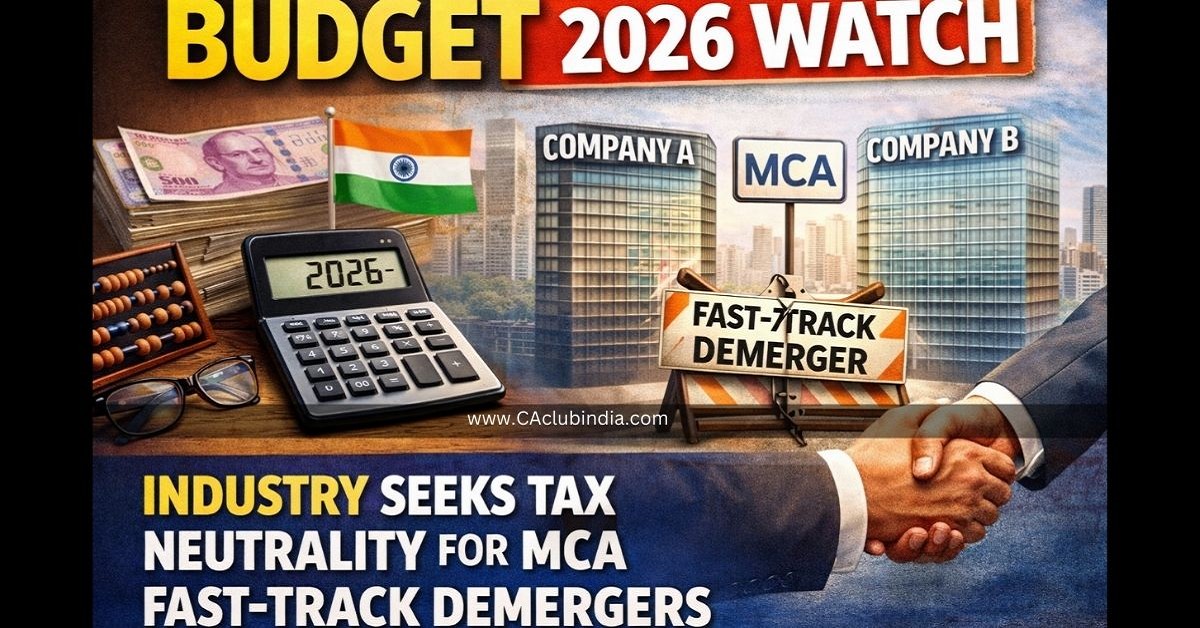
The Ministry of Corporate Affairs' move to introduce fast-track demergers was meant to mark a turning point in India's corporate restructuring landscape. By allowing companies to bypass the National Company Law Tribunal (NCLT) for certain demergers, the reform promised faster execution, lower costs and reduced regulatory friction. However, unresolved tax issues are now threatening to dilute these benefits, say tax and legal experts.
Effective from September 4, 2025, the MCA permitted companies to undertake demergers under Section 233 of the Companies Act, 2013, subject to approvals from shareholders, creditors and the regional director. The intent was to reserve the NCLT route for complex or contested matters, while routine intra-group reorganisations could proceed without prolonged tribunal oversight.
Under the conventional tribunal process, even straightforward demergers typically involve months of hearings, compliance filings and professional fees. For unlisted companies and promoter-led groups, these delays often act as a deterrent to timely business restructuring, particularly when entities are carved out for fundraising, regulatory segregation or strategic focus.
Fast-track demergers were designed to address exactly these challenges. By eliminating tribunal involvement where there are no objections, the process was expected to align India's restructuring framework more closely with global best practices.
Yet, while corporate law now provides a simplified route, the Income Tax Act, 2025 has not kept pace.
The tax law extends tax neutrality only to demergers approved by the NCLT, leaving fast-track demergers outside its scope. As a result, transactions that are commercially identical to tribunal-approved demergers may now trigger significant tax costs solely due to the procedural route chosen.
Experts point out that this creates an uneven playing field. Companies opting for fast-track demergers could face capital gains tax ranging from 12.5% to 20% on asset transfers. Shareholders may be exposed to even higher tax outflows if the transaction is characterised as a deemed dividend, potentially attracting tax of up to 36%.
"The absence of tax neutrality defeats the very purpose of introducing a fast-track mechanism," a tax expert said. "These restructurings do not alter beneficial ownership, yet they are being taxed as if value is being extracted."
The impact is most pronounced for unlisted and closely held companies, which were the intended beneficiaries of the reform. Listed entities, on the other hand, continue to prefer the NCLT route where tax certainty is well-established.
Legal professionals believe the issue stems from a legislative mismatch rather than policy intent. While the Companies Act recognises fast-track demergers, the definition of "demerger" under the tax law does not reference Section 233, effectively excluding such transactions from tax relief.
"There is a strong case for aligning tax provisions with the MCA framework," an expert said. "A clarification or amendment in the Union Budget 2026 could restore confidence and encourage wider adoption of fast-track demergers."
Cross-border demergers face an even tougher environment. Outbound demergers involving foreign entities generally trigger capital gains tax in India, tax implications for shareholders receiving overseas shares, and restrictions on carrying forward losses, making such structures commercially unattractive.
Unless these tax concerns are addressed, experts warn that companies may continue to rely on the slower tribunal-led process, undermining the government's broader objective of making corporate restructuring more efficient and business-friendly.







 CAclubindia

