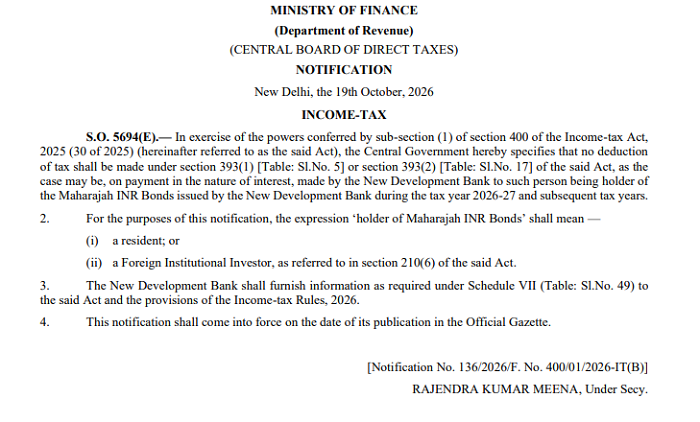
The Central Government has exempted interest payments made by the New Development Bank (NDB) to holders of Maharajah INR Bonds from Tax Deducted at Source (TDS) for the tax year 2026-27 and subsequent tax years. The exemption has been notified by the Ministry of Finance under Notification No. 136/2026, dated 19 October 2026.
The notification, issued by the Central Board of Direct Taxes (CBDT), has been made under Section 400(1) of the Income-tax Act, 2025. It provides that tax shall not be deducted at source on qualifying interest payments covered by Section 393(1), Table Sl. No. 5, or Section 393(2), Table Sl. No. 17, of the Act, as applicable.
Who Can Claim the TDS Exemption?
The notification specifies that the exemption applies to interest payments made by the New Development Bank to holders of Maharajah INR Bonds during the tax year 2026-27 and subsequent tax years.
For this purpose, the expression "holder of Maharajah INR Bonds" includes the following categories:
- Residents: Individuals or entities qualifying as residents under the applicable provisions.
- Foreign Institutional Investors (FIIs): FIIs referred to in Section 210(6) of the Income-tax Act, 2025.
The notification identifies these two categories as eligible holders for the purpose of the specified TDS exemption.
New Development Bank Required to Furnish Information
While providing relief from TDS on the specified interest payments, the notification also places an information-reporting requirement on the New Development Bank.
The bank must furnish the information prescribed under Schedule VII, Table Sl. No. 49, of the Income-tax Act, 2025, along with the applicable requirements under the Income-tax Rules, 2026.
This reporting obligation will continue to apply in accordance with the relevant provisions, even though qualifying interest payments are exempt from TDS under the notification.
When Does the Notification Come into Effect?
Notification No. 136/2026, bearing File No. 400/01/2026-IT(B), was issued by the Ministry of Finance on 19 October 2026. It will come into force from the date of its publication in the Official Gazette.
The specified TDS exemption covers qualifying interest payments during the tax year 2026-27 and subsequent tax years.
Key Takeaway
The CBDT notification provides TDS relief on interest payments made by the New Development Bank to eligible holders of Maharajah INR Bonds from tax year 2026-27 onwards. The exemption covers residents and Foreign Institutional Investors referred to under Section 210(6) of the Income-tax Act, 2025.
However, the New Development Bank must continue to comply with the prescribed information-furnishing requirements under Schedule VII and the Income-tax Rules, 2026.









 CAclubindia
