The Central Board of Direct Taxes (CBDT) has clarified that ex-gratia compensation received by employees of Bharat Sanchar Nigam Limited (BSNL) and Mahanagar Telephone Nigam Limited (MTNL) under the Voluntary Retirement Scheme (VRS), 2019, falls under Section 10(10C) of the Income-tax Act, 1961, and not Section 10(10B), which deals with retrenchment compensation.
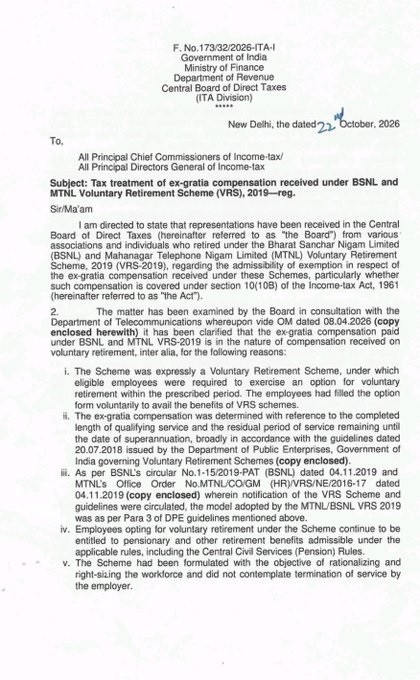
In a communication dated October 22, 2026, addressed to all Principal Chief Commissioners of Income-tax and Principal Directors General of Income-tax, the Board set out its position following representations from employees and associations seeking exemption under Section 10(10B).
The clarification is significant for VRS-2019 retirees who have claimed, or are considering claiming, tax exemption by treating the compensation received as retrenchment compensation.
Why Has CBDT Issued the Clarification?
The tax treatment of ex-gratia payments made under BSNL and MTNL VRS-2019 has been a subject of dispute. While the schemes were introduced as part of the government's workforce-restructuring initiative, some retirees sought to classify the payments as retrenchment compensation rather than voluntary retirement benefits.
The CBDT examined the representations in consultation with the Department of Telecommunications (DoT). Referring to the department's communication dated April 8, 2026, the Board concluded that the compensation received under the schemes was in the nature of voluntary retirement compensation.
Accordingly, it clarified that Section 10(10C), rather than Section 10(10B), applies to the payments.
CBDT's Reasons for Treating the Payments as VRS Compensation
The Board cited several features of the 2019 schemes to support its conclusion:
- Voluntary participation: The schemes expressly provided for voluntary retirement, and eligible employees submitted their option forms within the prescribed period.
- Method of calculating compensation: The ex-gratia amount was determined with reference to completed qualifying service and the period remaining until superannuation, broadly following the Department of Public Enterprises' guidelines dated July 20, 2018.
- Scheme documentation: BSNL's circular and MTNL's office order, both dated November 4, 2019, set out the respective schemes and their implementation guidelines.
- Retirement benefits: Employees opting for the schemes continued to be entitled to pensionary and other retirement benefits under the applicable rules, including the Central Civil Services (Pension) Rules.
- Workforce restructuring: The schemes were designed to rationalise and right-size the workforce and were not intended to terminate employees' services through retrenchment.
On the basis of these factors, the CBDT maintained that the payments should be treated as compensation received on voluntary retirement.
CBDT Distinguishes the Hindustan Photo Film Case
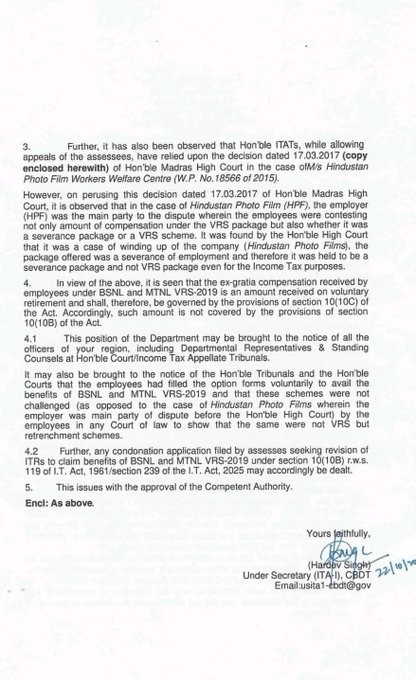
The Board also addressed the reliance placed by some Income Tax Appellate Tribunals (ITATs) on the Madras High Court's decision dated March 17, 2017, in the case of Hindustan Photo Film Workers Welfare Centre.
According to the CBDT, the facts of that case were materially different from those of BSNL and MTNL VRS-2019.
The earlier dispute arose in the context of the company's winding up. Questions had been raised regarding the nature and amount of compensation, including whether the payment represented a severance package or compensation under a voluntary retirement scheme. The Madras High Court treated the package as severance compensation rather than a VRS package.
In contrast, the CBDT observed that employees of BSNL and MTNL had voluntarily exercised their options under the 2019 schemes. It also noted that the employees had not challenged the schemes before a court to establish that they were retrenchment schemes rather than voluntary retirement schemes.
The Board has therefore distinguished the earlier judicial decision while setting out its position on the tax treatment of the payments.
Directions to Income-Tax Authorities and Courts
The CBDT has directed that its clarification be brought to the attention of income-tax officers across the country, including departmental representatives and standing counsel appearing before courts and Income Tax Appellate Tribunals.
The communication also calls for the relevant facts concerning the voluntary nature of the schemes and the distinction from the Hindustan Photo Film case to be placed before the appropriate judicial forums.
The Board has further addressed applications seeking condonation of delay for revising income-tax returns to claim exemption under Section 10(10B), read with Section 119 of the Income-tax Act, 1961, or Section 239 of the Income-tax Act, 2025. Such applications are to be dealt with in accordance with the position set out in the clarification.
What Does the Clarification Mean for BSNL and MTNL Retirees?
The clarification establishes the CBDT's position that compensation received under BSNL and MTNL VRS-2019 is governed by Section 10(10C) and cannot be claimed as exempt under Section 10(10B) merely by treating it as retrenchment compensation.
However, the applicability of the relevant exemption and any other tax relief must be assessed under the applicable statutory provisions and the facts of the individual case. The clarification should not be read as declaring the entire ex-gratia amount tax-free.
Retirees who have claimed exemption under Section 10(10B), or are involved in related tax proceedings, may need to review their claims in light of the communication and obtain appropriate professional advice.







 CAclubindia
