The Goods and Services Tax (GST) Council has recommended a series of compliance reforms aimed at reducing paperwork, speeding up refunds and minimising unnecessary litigation for businesses and taxpayers. The recommendations emerged from the 57th GST Council meeting held on October 8, 2026, with a focus on simplifying GST procedures and making compliance more efficient.
Despite several technology-driven initiatives, businesses continue to face practical challenges, including delays in refunds, input tax credit (ITC) reversals, portal-related issues and demanding filing deadlines. The proposed changes are expected to ease some of these difficulties, particularly for small businesses and professionals managing GST compliance.
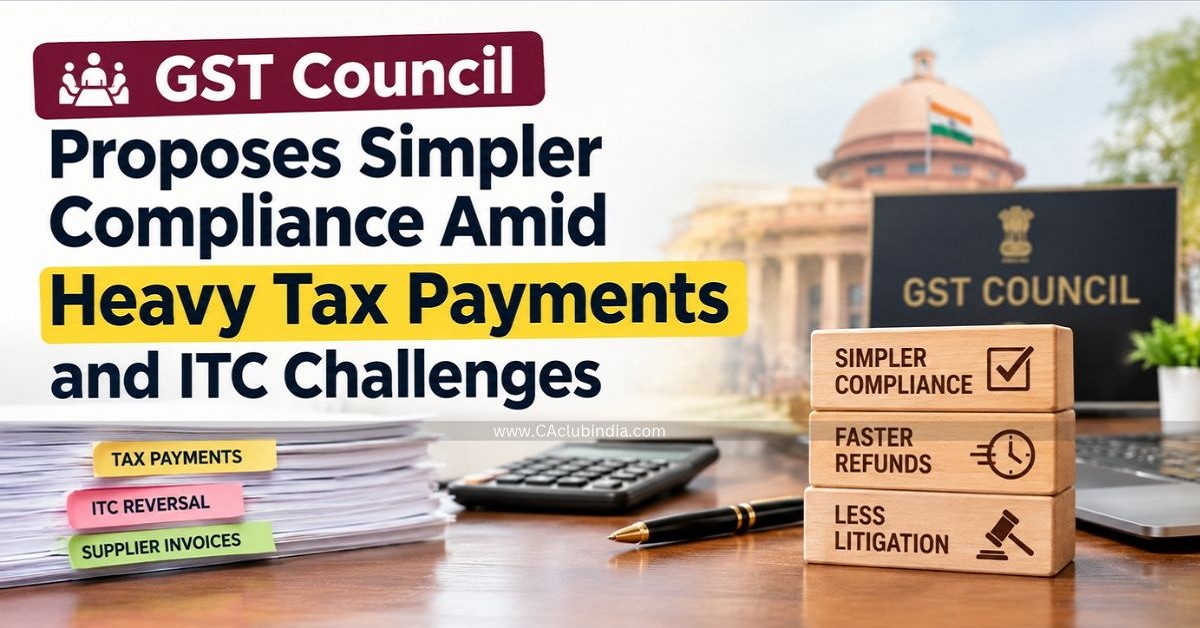
GST Council Recommends Measures to Simplify Compliance
The GST Council has proposed measures intended to make registration, refund processing and return filing more straightforward. These recommendations seek to reduce repetitive documentation and improve the overall taxpayer experience.
Key proposals include:
- Automatic GST registration: A simplified registration mechanism to reduce delays and make it easier for eligible businesses to obtain registration.
- Faster GST refunds: Measures to accelerate refund processing, including a proposed provisional refund facility for eligible taxpayers.
- Reduced penalties and litigation: Changes aimed at making enforcement more proportionate and reducing avoidable disputes.
- Simplified return filing: Greater use of system-generated information to reduce manual data entry and reconciliation work.
These measures are intended to make GST administration more predictable for businesses while improving the efficiency of tax authorities.
Heavy GST Payments Create Challenges for Businesses
GST compliance can create significant cash-flow and administrative pressure, particularly when businesses face tax payments that do not appear to align with their understanding of their taxable activities.
For instance, some businesses have reported paying substantial GST amounts, including cases involving payments of around ₹2.3 lakh despite having overseas revenue. Such situations highlight the importance of understanding the nature of the underlying transactions, their place of supply, applicable GST provisions and the availability of export-related benefits.
However, overseas revenue does not automatically mean that a transaction is exempt from GST. The tax treatment depends on the facts and the applicable legal requirements, including whether the transaction qualifies as an export of services.
Businesses should therefore review their contracts, invoices, place-of-supply conditions and supporting documents before determining their GST liability.
ITC Reversals Due to Missing Supplier Invoices
Input tax credit remains one of the most challenging areas of GST compliance. Businesses may face difficulties when supplier invoices are missing from system-generated records or when suppliers fail to report transactions correctly.
These discrepancies can lead to reconciliation problems, disputes over ITC eligibility and potential credit reversals, affecting working capital.
Tax professionals recommend regular reconciliation of purchase registers with GSTR-2B, timely follow-ups with suppliers and proper documentation of eligible credit. Businesses should also monitor differences between their books and GST portal records well before filing returns.
The proposed compliance reforms may help reduce the administrative burden, but taxpayers will still need to maintain accurate records and satisfy the applicable statutory conditions for claiming ITC.
Auto-Population of GSTR-9 Data May Ease Annual Filing
Professionals have welcomed initiatives aimed at auto-populating information in GSTR-9, the annual GST return. Greater automation could reduce repetitive data entry and help taxpayers identify discrepancies more efficiently.
System-generated information can also support reconciliation between periodic returns, books of accounts and annual disclosures. Nevertheless, auto-populated data should not be accepted without verification.
Taxpayers must review the figures carefully, investigate mismatches and ensure that the information reported in the annual return is consistent with their records and applicable GST provisions.
GST Portal Glitches and Tight Deadlines Remain Concerns
Even as the government moves towards greater automation, technical issues and compressed compliance timelines continue to concern businesses and tax professionals.
Portal glitches can disrupt return filing, reconciliation and payment processes, particularly when multiple statutory deadlines fall close together. Businesses with high transaction volumes may face additional pressure in verifying data and resolving discrepancies before filing.
Professionals have therefore stressed the need for reliable portal performance, sufficient time for compliance and clear guidance on procedural changes.
What Businesses and Tax Professionals Should Do
Until the recommendations are implemented through the relevant notifications, rules or other applicable legal instruments, taxpayers should continue to follow the existing GST framework.
Businesses can prepare by taking the following steps:
- Reconcile purchase registers with GSTR-2B and investigate missing supplier invoices.
- Review ITC claims and reversals to identify potential discrepancies.
- Verify GST liabilities on overseas transactions based on the nature of the supply and applicable provisions.
- Check annual return data against books of accounts before filing GSTR-9.
- Monitor official GST notifications and portal advisories for implementation details.
Conclusion
The GST Council's recommendations signal a continued push towards simpler registration, faster refunds, reduced compliance burdens and greater automation. If implemented effectively, these measures could help businesses spend less time on procedural formalities and more time on their core operations.
However, the success of these reforms will depend on smooth portal functioning, clear implementation guidelines and adequate time for taxpayers to adapt. For businesses and GST professionals, accurate reconciliation and timely monitoring of official updates will remain essential.







 CAclubindia

