Goods and Services Tax (GST) Council has recommended easing restrictions on Input Tax Credit (ITC) for several categories of business expenses, potentially providing relief to businesses facing higher tax costs and working capital pressures. The recommendations were discussed at the 57th GST Council meeting held earlier this month and aim to reduce tax cascading while making GST compliance more practical for businesses.
However, businesses should note that these recommendations are not automatically effective. The proposed changes will require the necessary amendments to the GST law and relevant notifications before they can be implemented.
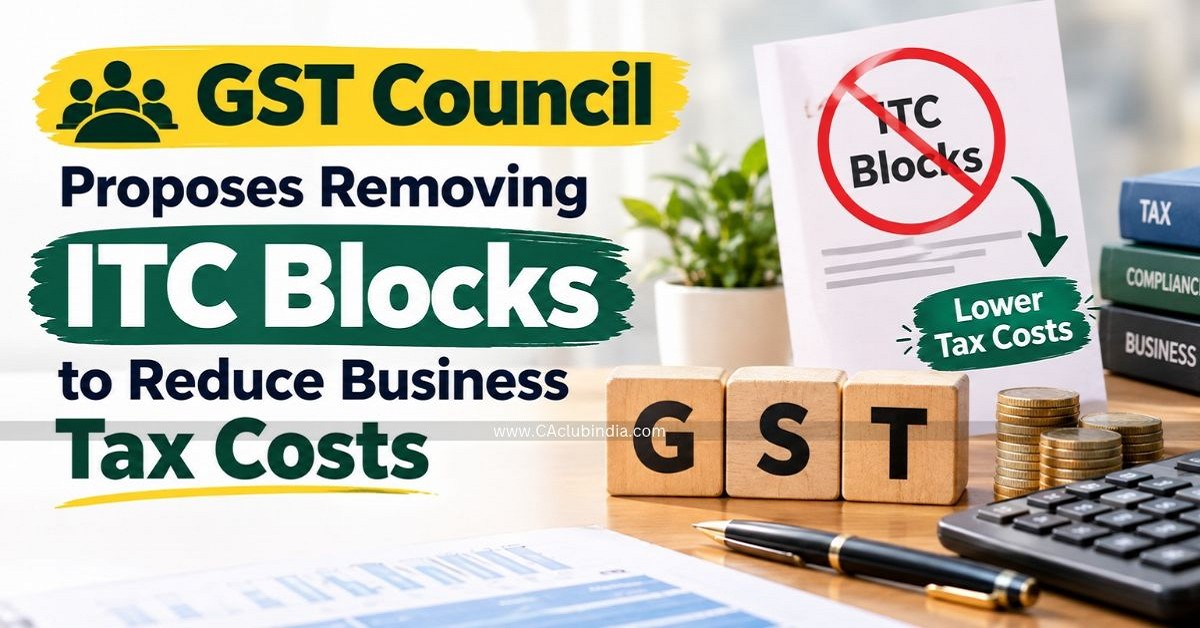
GST Council Recommends Relaxation of ITC Restrictions
Input Tax Credit allows eligible businesses to offset GST paid on purchases against their GST liability on sales. Restrictions on ITC can increase the effective cost of doing business, particularly where expenses are incurred for operational purposes but credit is not permitted under the existing provisions.
The GST Council has recommended removing or easing certain ITC restrictions covering expenses and goods such as:
- Health insurance: Proposed relaxation of restrictions relating to input tax credit on health insurance expenses.
- Telecom towers: Relief concerning ITC restrictions on telecom towers used in business operations.
- Pipelines outside factory premises: Proposed changes relating to credit restrictions on pipelines laid outside factory premises.
- Free samples: Review of ITC restrictions associated with goods distributed as free samples.
- Goods destroyed as required by law: Proposed relief concerning ITC restrictions on goods destroyed in accordance with legal requirements.
These recommendations are intended to address practical difficulties faced by businesses and reduce situations where GST becomes an additional cost instead of remaining a creditable tax.
The precise scope and eligibility conditions will depend on the final legal amendments and notifications.
How the Proposed ITC Changes Could Benefit Businesses
The proposed changes could have a positive impact on businesses across different sectors by reducing the tax costs associated with eligible expenses.
1. Reduced Tax Cascading: When businesses cannot claim eligible input tax credits, the GST paid on certain expenses becomes part of their costs. Relaxing restrictions could help reduce this cascading effect and improve tax efficiency.
2. Improved Working Capital: Businesses may benefit from lower embedded tax costs and better utilisation of eligible credits, potentially freeing up funds for day-to-day operations and business expansion.
3. Greater Clarity in GST Compliance: Changes to ITC restrictions could help resolve recurring interpretational issues and reduce disputes between taxpayers and tax authorities.
4. Relief for Capital-Intensive Sectors: Businesses investing in infrastructure, telecom facilities and related operational assets may benefit if the proposed changes permit credits that are currently restricted under the applicable provisions.
The actual financial benefit will depend on the final amendments, the nature of the expenses and the conditions prescribed under GST law.
Fake ITC Claims Remain a Major Concern
While the proposed relaxations could make GST compliance easier for genuine businesses, fraudulent Input Tax Credit claims remain a significant concern.
Reported figures indicate that the value of fake ITC claims increased from approximately ₹24,140 crore in 2022 to more than ₹74,000 crore in 2025. This trend highlights the continuing challenges faced by tax authorities in detecting fraudulent transactions and preventing revenue leakage.
The need to distinguish genuine credit claims from fraudulent transactions remains central to the GST framework. Easing restrictions on eligible business expenses does not mean that documentation requirements or verification procedures can be ignored.
Businesses should ensure that every ITC claim is supported by valid records and complies with the applicable legal provisions.
Documents Businesses Should Maintain for ITC Claims
As GST authorities continue to scrutinise suspicious credit claims, businesses should strengthen their documentation and reconciliation processes.
Important records include:
- Tax invoices: Ensure that invoices contain the prescribed particulars and correspond with genuine business transactions.
- GSTR-2B reconciliation: Regularly reconcile purchase records and eligible ITC with the relevant auto-drafted statement, while addressing mismatches appropriately.
- E-way bills: Retain applicable e-way bills and supporting transportation records to establish the movement of goods.
- Payment and supplier records: Maintain purchase orders, payment evidence and supplier details wherever relevant.
- Stock and destruction records: Preserve appropriate evidence for free samples, destroyed goods and other transactions requiring specific treatment.
- GST returns: Ensure that eligible credits are correctly reported in the relevant returns and that reversals or adjustments are made wherever required.
Maintaining these records can help businesses substantiate genuine ITC claims during departmental scrutiny, audits and investigations.
GSTR-3B Compliance: Businesses Must Track Upcoming Deadlines
Alongside the proposed ITC reforms, taxpayers must continue to comply with existing GST return-filing requirements. For certain taxpayers, the GSTR-3B filing deadline falls on October 24, 2026.
The applicable due date depends on the taxpayer's category and filing frequency. Businesses should verify the deadline applicable to their registration and ensure that tax liabilities, eligible ITC and reversals are accurately reported.
Taxpayers should not assume that the Council's recommendations change existing filing obligations. Until the relevant amendments and notifications take effect, the applicable GST provisions and compliance requirements continue to govern ITC claims.
What Businesses Should Do Next
Businesses should review their current ITC positions, identify expenses potentially covered by the proposed relaxations and assess the possible impact on their tax costs and working capital.
At the same time, they should avoid claiming credits solely on the basis of the Council's recommendations. The final amendments, notifications and prescribed conditions must be examined before making changes to ITC treatment.
For finance teams, accountants and tax professionals, the immediate priorities remain timely return filing, accurate reconciliation, adequate documentation and monitoring of official GST updates.
Conclusion
The GST Council's recommendations to ease selected Input Tax Credit restrictions could offer meaningful relief to businesses by reducing tax cascading, improving working capital management and addressing practical compliance challenges. Proposed changes concerning health insurance, telecom towers, pipelines outside factory premises, free samples and legally destroyed goods are particularly relevant to businesses reviewing their ITC positions.
Nevertheless, the success of these reforms will depend on their final implementation through appropriate legal amendments and notifications. With fraudulent ITC claims continuing to concern tax authorities, businesses must balance the potential benefits of the proposed relaxations with careful documentation and strict compliance.







 CAclubindia

