The Ministry of Finance has issued two important notifications dated October 31, 2026, revising the Central Excise duty entries applicable to specified products. Through Notification Nos. 55/2026-Central Excise and 56/2026-Central Excise, the Central Government has amended two earlier notifications issued on March 26, 2026.
The amendments modify the duty rates mentioned against specific serial numbers in the respective notification tables. Both changes take effect from the date of publication in the Official Gazette.
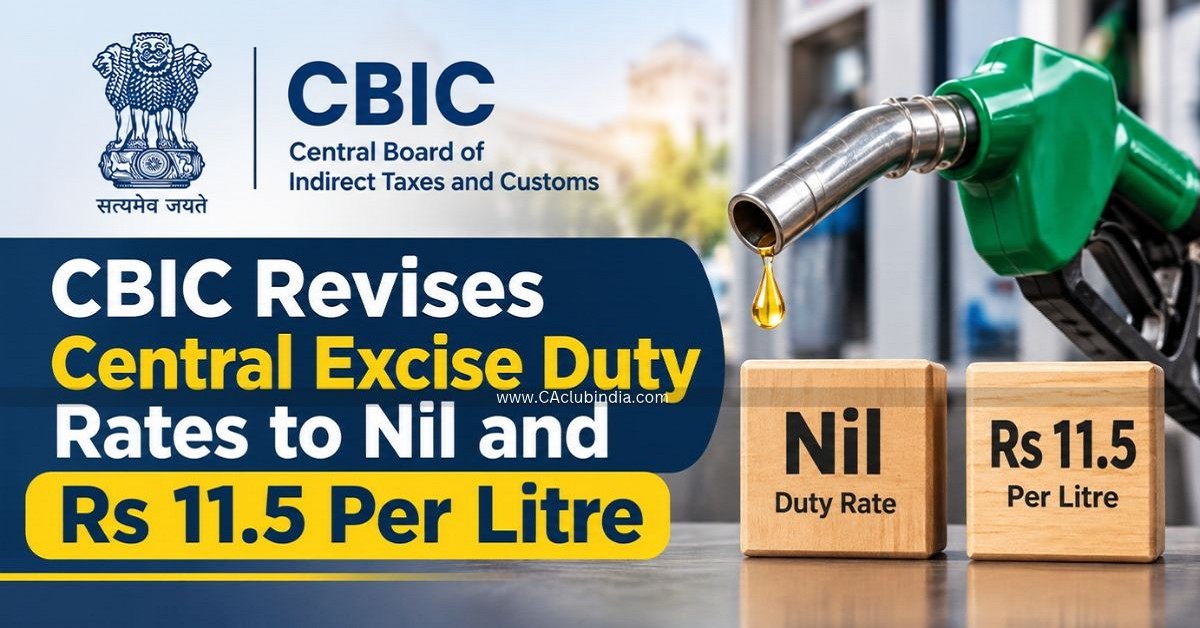
1. Notification No. 55/2026-Central Excise dated October 31, 2026
The Ministry of Finance, Department of Revenue, issued Notification No. 55/2026-Central Excise vide G.S.R. 963(E) dated October 31, 2026.
The notification amends the earlier Notification No. 06/2026-Central Excise dated March 26, 2026.
Under the amendment, the entries appearing in Column (4) of the notification table have been revised as follows:
|
Serial Number |
Revised entry in Column (4) |
|---|---|
|
1 |
Nil |
|
2 |
₹11.5 per litre |
Accordingly, the earlier entries against Serial Numbers 1 and 2 have been replaced with the revised duty entries.
Effective Date: The amendment comes into force from October 31, 2026, being the date of publication in the Official Gazette.
The original Notification No. 06/2026-Central Excise was published on March 26, 2026, and was last amended through Notification No. 54/2026-Central Excise dated October 15, 2026.
2. Notification No. 56/2026-Central Excise dated October 31, 2026
The Government has also issued Notification No. 56/2026-Central Excise, vide G.S.R. 964(E), dated October 31, 2026.
This notification amends the principal Notification No. 08/2026-Central Excise dated March 26, 2026.
The amendment specifically revises the entry appearing against Serial Number 1 in Column (4) of the relevant table.
|
Serial Number |
Revised entry in Column (4) |
|---|---|
|
1 |
₹11 per litre |
The revised entry replaces the earlier rate specified against the concerned serial number.
Effective Date: This amendment also comes into force from October 31, 2026, the date of its publication in the Official Gazette.
The original Notification No. 08/2026-Central Excise was published on March 26, 2026, and was last amended through Notification No. 53/2026-Central Excise dated September 30, 2026.
3. Key Changes at a Glance
The following table summarises the changes introduced through both notifications:
|
Particulars |
Notification No. 55/2026 |
Notification No. 56/2026 |
|---|---|---|
|
Notification date |
October 31, 2026 |
October 31, 2026 |
|
G.S.R. Number |
963(E) |
964(E) |
|
Principal notification amended |
06/2026 |
08/2026 |
|
Serial No. 1 |
Nil |
₹11 per litre |
|
Serial No. 2 |
₹11.5 per litre |
Not amended |
|
Effective date |
October 31, 2026 |
October 31, 2026 |
4. Legal Provisions Under Which the Notifications Are Issued
Both notifications have been issued by the Central Government in exercise of the powers conferred under:
- Section 5A of the Central Excise Act, 1944.
- Section 147 of the Finance Act, 2002.
The Government has stated that the amendments are being made in the public interest.
5. What Should Businesses and Tax Professionals Note?
Businesses and professionals dealing with products covered under the respective Central Excise notifications should take note of the revised entries.
The key compliance points are:
- Review the amendments to Notifications No. 06/2026 and 08/2026.
- Apply the revised duty entries from October 31, 2026.
- Update relevant duty calculations and internal records, wherever applicable.
- Refer to the original notifications along with the latest amendments to determine the applicable duty treatment.
Since the amendments are limited to specified entries in the notification tables, the revised rates should be read in conjunction with the corresponding original notifications.
Conclusion
Through Notifications No. 55/2026-Central Excise and 56/2026-Central Excise, dated October 31, 2026, the Central Government has revised specified Central Excise duty entries under two existing notifications.
While Notification No. 55/2026 substitutes the entries against Serial Numbers 1 and 2 with Nil and ₹11.5 per litre respectively, Notification No. 56/2026 revises the entry against Serial Number 1 to ₹11 per litre.
Both amendments are effective immediately from their publication in the Official Gazette.








 CAclubindia
