ITC reversal when ITC wrongly claimed
A restaurant business mistakenly claimed input tax credit (ITC) on an invoice with a 5% GST, which is not eligible for ITC under GST regulations. Please advise on how to reverse this ITC, and whether interest and penalties will apply? Please provide relevant sections for reference.
Replies (5)
Quick Summary

If ITC is wrongly claimed (e.g., on restaurant supplies not eligible under Section 17(5)), it must be reversed in GSTR-3B under ITC reversal. Interest under Section 50 may apply, and penalty under Section 122 may apply if there is wilful misstatement. Proper disclosure is required in returns.

A common mistake! Reversal of ITC To reverse the incorrectly claimed ITC, the restaurant business should:

1. *Identify the incorrect ITC claim*: Verify the invoice and GST return (GSTR-3B) to confirm the incorrect ITC claim. 

2. *Calculate the incorrect ITC amount*: Determine the amount of ITC incorrectly claimed. 

3. *Reverse the ITC in GSTR-3B*: In the next GSTR-3B return, reverse the incorrect ITC amount by reporting it as a negative entry in Table 4 (Reversal of ITC). 

4. *Pay the tax and interest*: Pay the tax amount corresponding to the reversed ITC, along with interest, if applicable. Interest and Penalties Interest and penalties may apply, depending on the circumstances:

 1. *Interest*: Interest may be applicable on the incorrect ITC amount, as per Section 50 of the CGST Act, 2017.

 2. *Penalties*: Penalties may be imposed under Section 122 of the CGST Act, 2017, if the incorrect ITC claim is deemed to be a deliberate attempt to evade tax. Relevant Sections 1. *Section 16(2)*: ITC can be availed only if the supplier has complied with the provisions of the Act. 2. *Section 17(5)*: ITC is not available on certain goods and services, including food and beverages served in restaurants.

3. *Section 42*: Procedure for reversal of ITC. 

4. *Section 50*: Interest on delayed payment of tax.

 5. *Section 122*: Penalties for certain offenses.


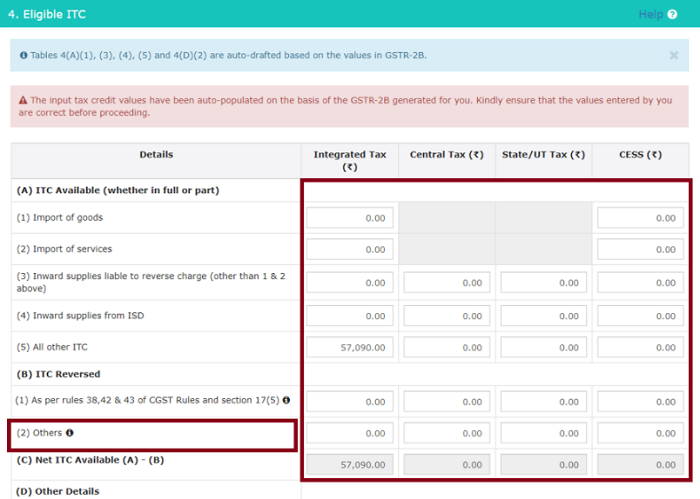
You may report the reversal in Table 4(B)(2) of GSTR-3B under "ITC Reversed – Others"

Wrongly claimed ITC needs to be reversed in the current period GSTR-3B through Table 4(B)(2). Here is the step-by-step:

Step 1: Identify the exact ITC amount wrongly claimed and the period in which it was claimed.

Step 2: In your NEXT GSTR-3B (or the current unfiled return if still within the period), go to Table 4, then sub-table 4(B)(2) - Reversal of ITC under Rule 42/43 and other provisions. Report the reversal amount here.

Step 3: Interest applies at 18% per annum from the date the wrong ITC was utilised till the date of reversal. Calculate this and pay it via challan before filing.

Step 4: If the wrong ITC was due to a vendor invoice mismatch with GSTR-2B, the reversal may fall under Rule 37A (vendor non-filing) instead of Rule 42. Check which rule applies to your situation.

No penalty is levied for voluntary reversal, only interest. Do not delay as the interest meter runs daily.

For a full walkthrough of the GSTR-3B tables including the reversal section with screenshots, this [GSTR-3B filing guide](https://taxgarden.in/blog/gst-login-gstr-3b-filing-step-by-step-guide-screenshots-2026) is useful.

Reversal and consequences:

• Basis: a restaurant at 5% (non-specified premises) is under a rate notification condition that no ITC is taken (Notf 11/2017-CT(R) as amended). Any ITC claimed is ineligible.

• Reverse in GSTR-3B Table 4(B)(2) (or pay through DRC-03 if it relates to past periods), along with interest.

• Interest: 18% under Sec 50(3) only if the ineligible ITC was availed and utilised (i.e. used to pay output tax). Calculate from the date of utilisation (Rule 88B). If the ITC has sat unused in the credit ledger, no interest is payable.

• Penalty: if paid with interest before a show cause notice under Sec 73 (non-fraud cases), no penalty is levied (Sec 73(5)). After an SCN, payment within 60 days of issue reduces it. From FY 2024-25 the same principle applies under Sec 74A.

• Going forward: ensure the purchase register does not auto-claim ITC. Keep a reconciliation showing nil ITC for audit, since the rate entry condition can disqualify the 5% rate itself if ITC is retained.

Reverse the ineligible ITC in the period in which the error is identified, by reducing the ITC in GSTR-3B (generally Table 4(B)(1) if treated as permanent/non-reclaimable). If the relevant return has already been filed, make the adjustment in a subsequent GSTR-3B; do not amend the filed return. Keep the invoice and workings supporting the reversal.

  • Interest: Under section 50(3) of the CGST Act, interest at the prescribed rate applies only if the wrongly availed ITC was also utilised. If it was reversed before utilisation, interest is generally not payable. The prescribed rate is 24% p.a.; the utilisation and calculation rules are in Rule 88B(3) of the CGST Rules.
  • Penalty: A voluntary correction, before proceedings are initiated, does not automatically attract a penalty. If ITC was wrongly availed and utilised, sections 73 or 74 may apply depending on whether fraud, wilful misstatement or suppression is alleged; section 73 provides for tax, interest and applicable penalty, while section 74 has higher penalty consequences. For periods covered by the amended regime, section 74A may be relevant. The applicable provision depends on the tax period and facts.
  • Eligibility: Confirm that the restaurant supply is indeed subject to the 5% rate without ITC and that the credit was not attributable to a separately eligible supply or activity.

This reversal should be reconciled with the electronic credit ledger and return records, with any interest paid through DRC-03 where required. Correct classification of the restaurant’s supplies and the period of availment will determine the treatment.

Managing reversals alongside return reconciliations is a routine GST control workflow. Manual practice work can be difficult, and automation reduces repetitive checks while keeping professional judgment in control. At Jir AI, our 2,000+ AI agents and 650+ integrations streamline GST, ITR, TDS, TCS and other compliance workflows, helping reduce manual workload by up to 70%. For help exploring this workflow, connect with us on WhatsApp: https://wa.me/message/3HVOZ7HIY4ESC1

Leave a Reply

Your are not logged in . Please login to post replies

Click here to Login / Register  

Company
12 November 2026
Auditor

Oz Taxation

Vijayawada

Graduate (Any)

View Details
Company
ARTICLESHIP 23 October 2026
Articled Trainee

J Y & CO

Hyderabad

CA Inter

View Details
Company
ARTICLESHIP 25 October 2026
Article Intern (CA Articleship)

Arpan Bohra & Co

Hyderabad

CA Inter

View Details
Company
ARTICLESHIP 29 October 2026
Article Assistant (CA Inter / CMA Inter) - Thrissur

Varma Raja & Associates

Thrissur

CA Inter

View Details
Company
21 October 2026
CA INTER/ BCOM WITH EXPERIENCE

CA S KUMAR GUPTA & CO

Amritsar

CA Inter

View Details
Company
Featured 17 November 2026
Chartered Accountant

M/s. A V C & Co.

New Delhi

CA

View Details
Company
ARTICLESHIP 07 November 2026
Article Assisstant

DPV & Associates

Chennai

CA Inter

View Details
Company
14 November 2026
Manager - Indirect Tax (GST)

Westbridge Consulting LLP

New Delhi

CA

View Details