TDS Short Deduction Interest on Form 26QB

While submitting Form 26QB, I made two mistakes

  1. I made a rounding error which caused a short deduction of Rs 0.47
  2. I entered incorrect Date of Payment in the challan which gave impression that I had filed the TDS late.

For this, I received a notice from TDS CPC which mentioned  Short Deduction, Interest on Late Payment & Late Filing Levy.

Then I submitted a request for correction of Date of Payment in Form 26QB through TRACES portal. This request got approved after verification of all documents & transactions. Unfortunately, I did not do anything about Short Deduction.

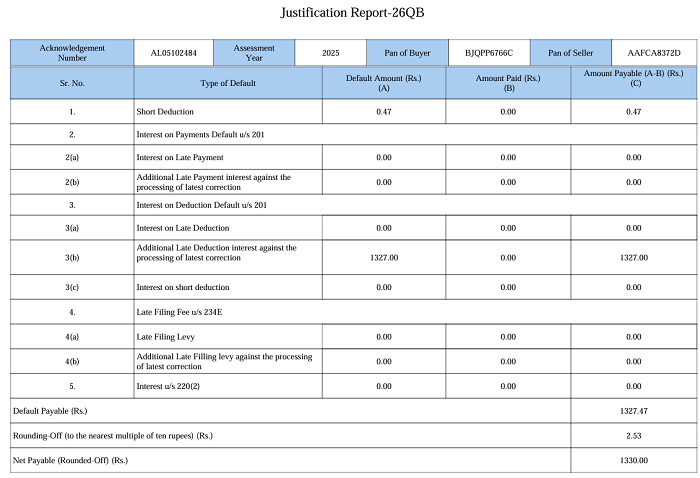
After the correction got approved, I received another notice in which there is a demand Rs. 1,327 for Late Deduction interest against the processing of latest correction. Apparently this amount is 1% of Total Amount for which I had paid TDS.
Is paying the demand my only option now? Any guidance would be appreciated.

 

Replies (5)
Quick Summary
This discussion addresses issues arising from errors made when submitting Form 26QB, specifically a rounding error leading to a short TDS deduction and an incorrect payment date. The user received notices for short deduction, interest on late payment, and late filing. While the payment date error was corrected via TRACES, the short deduction resulted in an interest demand. Options discussed include paying the demand, filing a rectification request, or submitting a revised return. The conversation also touches upon the documents needed for correction requests and clarifies the calculation of interest for short deductions under Section 194IA (now Section 441).

Firstly, it's great that you've already corrected the Date of Payment in the challan through the TRACES portal.

However, the short deduction of Rs 0.47 is still pending. Regarding the demand notice for Rs. 1,327, you have a few options: - *Pay the Demand*: You can pay the demand amount, but this might not be the best option, considering you've already corrected one mistake. -

*File a Rectification Request*: You can file a rectification request online to correct the short deduction error. This might help you avoid paying the demand amount.¹

 - *Submit a Revised Return*: If you're not comfortable with the rectification request process, you can submit a revised return to correct the errors.

Before proceeding, ensure you: 1. *Verify the Demand Notice*: Double-check the demand notice to ensure it's accurate and not a result of another error.

2. *Gather Supporting Documents*: Collect all relevant documents, including the corrected challan and proof of TDS payment. 3. **Consult

Hi Akhilesh,

I'm trying to get the date of payment corrected on my 26QB. Do you mind sharing the documents you needed to get verified? 

I'd submitted the following and my request was rejected for missing documents. Wondering if you had additional documents?

  1. Indemnity Bond Notarised 
  2. Copy of Challan & Form 26QB originally filed 
  3.  Bank Statement Reflecting the Transaction of 26qb payment.
  4. Copy of PAN and Aadhaar
  5. Form 26QB Correction Acknowledgment


In my case, Income Tax Officer asked for following documents

1. Copy of Sale Deed/Agreement.
2. Copy of PAN of the seller.
3. Bank account statement containing the amount(s) of all payments of sale consideration paid to the seller.
4. Copies of all Receipts issued by the seller.

Short deduction on Form 26QB attracts interest at 1% per month (or part of month) from the date TDS was due to be deducted to the date it was actually deducted, and 1.5% per month from the date of deduction to the date of payment to the government. Both periods run simultaneously if you have not paid yet.

To correct the short deduction:
1. File a revised Form 26QB on the TIN-NSDL portal (tin.tin.nsdl.com/oltas/26qbonline.html) for the balance amount
2. Pay the differential TDS along with interest using challan 26QB
3. The seller can then see the updated credit in their Form 26AS and AIS

Two common reasons for short deduction to watch for: calculating TDS on the sale price only when the stamp duty value is higher (TDS should be on the higher of the two), and rounding down below 1% of consideration.

For the TDS rate and section reference under the new Income Tax Act 2025, the old Section 194IA is now Section 441. The rate remains 1% on amounts above Rs 50 lakh.

This [TDS compliance guide](https://taxgarden.in/blog/tds-on-insurance-commission-section-194d-393-guide-india) shows how old-to-new TDS section renaming works, which is useful if you are using any compliance software still referencing old section numbers.

Form 26QB demand after correction – how to close it:
• First download the Justification Report from TRACES (login as taxpayer with PAN). It shows exactly which dates TRACES used. Interest u/s 201(1A) is 1% per month or part from date of payment/credit to seller till date of deduction, and 1.5% per month or part from deduction till deposit. A demand of about 1% of the TDS amount usually means one month's late-deduction interest, i.e. the date of payment/credit in the corrected 26QB is still earlier than the date shown as deduction.
• If the dates in the statement are still wrong, file one more online correction on TRACES (with the AO's approval where needed) instead of paying. If the dates are right, the interest is payable.
• One correction to the earlier replies: the balance is not paid through a fresh/revised 26QB or by filing a "revised return". Pay the outstanding demand (short deduction ₹0.47, rounded up, plus interest) from the TRACES demand / e-Pay Tax option on the e-filing portal; 26QB itself is now filed on incometax.gov.in.
• For purchases from 1 April 2026, TDS on property falls under Sec 393(1) (Table Sl. 3(i)) of the Income-tax Act, 2025, not Sec 441; the 1% rate and ₹50 lakh threshold continue.


Leave a Reply

Your are not logged in . Please login to post replies

Click here to Login / Register  

Company
Featured 29 October 2026
Accounts Executive

Synergy Keystone

Chennai

B.Com

View Details
Company
31 October 2026
Accountants

sankaran and krishnan

New Delhi

B.Com

View Details
Company
14 November 2026
Manager - Indirect Tax (GST)

Westbridge Consulting LLP

New Delhi

CA

View Details
Company
ARTICLESHIP 23 October 2026
CA Articleship / Article Assistant

M N Rao & Associates LLP

Vijayawada

CA Inter

View Details
Company
ARTICLESHIP 14 November 2026
Articleship Assistant

B Thejas and Associates

Bengaluru

CA Foundation

View Details
Company
10 November 2026
FP&A Executive

Gujarat Guardian

Ankleshwar

CA Final

View Details
Company
23 October 2026
Sr. Accountant

SANKARAN & KRISHNAN

New Delhi

B.Com

View Details
Company
ARTICLESHIP 25 October 2026
Article Intern (CA Articleship)

Arpan Bohra & Co

Hyderabad

CA Inter

View Details



