Sir,
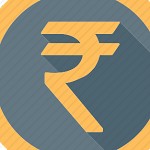
One of my client has received a sum of ₹35,00,000 towards Extinguishment of Rights and he invests this amount in a new business. What is the journal entry to be passed?
Sir,
One of my client has received a sum of ₹35,00,000 towards Extinguishment of Rights and he invests this amount in a new business. What is the journal entry to be passed?


Shyam S Gupta and Company
New Delhi
CA Inter
View Details CCI
Pro




 CAclubindia
